By Dhirendra Tripathi
Investing.com – BHP Billiton (NYSE:BBL) ADR traded 1.8% lower in Monday’s premarket on concerns that the company may not make the clean break with fossil fuels that many investors had hoped for.
BHP said overnight it's in talks with Woodside Petroleum (OTC:WOPEY) over a potential sale. One of the possibilities under consideration would include an all-share transaction in which BHP would distribute Woodside shares to its investors – an alternative that few BHP investors would prefer.
Reports peg the value of the deal at $15 billion. Under the likely terms, Woodside will issue its own equity to BHP shareholders as consideration for buying the mining giant’s petroleum business.
Such a deal would leave BHP shareholders with shares of a pure fossil fuel player, shares that they would be forced to sell immediately due to their investment mandates. Shareholders are usually happier with a cash-deal that would help the company pay them dividends or fund a buyback program.
BHP has got rid of many of its polluting assets and the sale of the petroleum business would bring it close to an exit from all such sectors.
A report last week by a UN panel warned of dire consequences as it said the climate is getting warmer at a pace faster than estimated earlier.
For Woodside, an acquisition of BHP's oil and gas assets would roughly double its annual underlying earnings to around $8 billion. For BHP, a petroleum exit would strip out just 5% of underlying earnings, according to Reuters
Woodside share closed 4.5% lower in today’s trading.
Related Articles
BHP Falls on Worry Woodside Deal Isn’t a Clean Break From Fossil Fuels
U.S banks walk tightrope of encouraging, but not mandating vaccines
Sydney Airport rejects improved $16.8 billion buyout bid, open to higher offer
(Bloomberg) — BHP Group is in talks over a potential merger of its oil and gas unit with Woodside Petroleum Ltd. to accelerate a retreat from fossil fuels amid increasing pressure to curb emissions.
Options being discussed include a distribution of Woodside shares to BHP holders to allow the Australian energy firm to add operations spanning Australia to the Gulf of Mexico, the companies said in separate statements. BHP’s unit could be valued at more than $15 billion, a person familiar with the details said last month.
The petroleum division “simply no longer fits within BHP’s portfolio or future-facing strategy,” said Saul Kavonic, an analyst at Credit Suisse Group AG. Having missed opportunities to sell thermal coal assets at higher prices, “BHP should know it’s better to exit petroleum sooner rather than later,” he said.
BHP, which generates the bulk of profits from iron ore and copper, is reviewing its portfolio as energy supermajors grapple with global pressure from investors and governments over climate action, in some cases by shrinking core production and adding renewable energy assets. Chief Executive Officer Mike Henry has already signaled plans to focus the world’s biggest miner on materials tied to renewable energy and electrification.
Woodside declined as much as 4.5% in Sydney trading Monday and was 4.4% lower as of 3:39 p.m. local time. BHP fell 0.9%.
“BHP confirms that we have initiated a strategic review of our petroleum business to re-assess its position and long-term strategic fit,” the company said. While talks with Woodside “are currently progressing, no agreement has been reached on any such transaction,” it said.
Though BHP has said it expects oil and gas demand to remain strong for at least another decade, and recently announced $800 million of investments in growth options, the company is wary of becoming stuck with assets that’ll become more difficult to exit as the world attempts to curb consumption of fossil fuels.
The talks with Woodside come a week after environmental campaign group Market Forces tabled a proposal on behalf of about 100 small investors that calls on BHP to wind down oil, gas and coal production in line with international targets to cut greenhouse gas emissions. A deal that would see investors take on Woodside shares risks undercutting BHP’s climate pledge, according to campaigner Will van de Pol.
“We know that investors have clearly signed up to the goal of net zero by 2050,” he said. “They’re increasingly understanding what that means, and it means no expansion of the oil & gas sector. So for investors to be lumped with shares in a company that is trying to expand its oil and gas production, I don’t think it’s going to sit that well.”
Asset Sales
Output in BHP’s oil and gas unit, which includes operations in Australia’s Bass Strait and North West Shelf, the U.S. Gulf of Mexico and in Trinidad and Tobago, declined 6% in the year to June 30. BHP is a partner in the projects with firms including BP Plc, Exxon Mobil Corp. and Woodside.
BHP sold the majority of its shale unit to BP in 2018 for about $10.5 billion, and is advancing plans to exit its final thermal coal mine and some metallurgical coal operations. Those divestments would leave the company with only a handful of fossil fuels assets, a collection of mines in Queensland that supply coal to steelmakers.
Last month, Bloomberg News reported BHP was considering plans to quit oil and gas. Woodside and BHP are in advanced talks over a deal worth about A$20 billion ($14.7 billion), the Australian Financial Review reported on Sunday, citing people familiar with the matter.
Melbourne-based BHP is scheduled to report annual results Tuesday.
(Updates with analyst comment in third paragraph.)
More stories like this are available on bloomberg.com
Subscribe now to stay ahead with the most trusted business news source.
©2021 Bloomberg L.P.
In this article, we will be looking at 10 Russell 2000 basic materials dividend stocks to buy. To skip our detailed analysis of the basic materials sector, you can go directly to see the 5 Russell 2000 Basic Materials Dividend Stocks to Buy.
The basic materials sector is one that is typically considered to be less exciting or gripping than others, like say the technology sector. However, it is a sector that can be considered among the winners of the market in 2021. There are a couple of reasons for this, most notably the fact that President Biden's administration and its focus on a greener and more environmentally friendly America would lead to a greater focus on the production of green technology, and electric vehicles (EVs) in particular. How this may affect the basic materials sector is the next, and most natural question, and is easily answered when one considers that metals produced and refined by this sector, such as copper, lithium, and others, are among the few most vital elements required in the production of EVs and green electricity.
However, this is not the only reason why the materials sector can be expected to become a not-so-boring sector this year. Rather there are a number of factors contributing to the rising popularity of basic materials stocks like Rio Tinto Group (NYSE: RIO), Freeport-McMoRan Inc. (NYSE: FCX), LyondellBasell Industries N.V. (NYSE: LYB), and International Paper Company (NYSE: IP).
Before considering other factors, let's look at the one mentioned above first. According to a Fidelity report on outlook for the basic materials sector in 2021, particularly in relation to the rising sales and production of EVs in the US and the growing demand for green electricity, we can see that there are positive prospects for the sector in the US. EV sales in the country are expected to rise by almost 12% between 2010 and 2050, to almost 2 million such vehicles being sold in the US alone. According to this report, as the EV market is reliant on batteries that in turn are dependent on lithium, cobalt, and nickel, it can be expected that companies involved in the production and handling of these metals within the materials sector are set to profit in the coming 2 decades. In fact, the Fidelity report has estimated that the rising demand for lithium and similar commodities has already risen so much that by the mid-2020s we may already be facing a supply crunch for these materials. On the same note, the report has estimated that by 2030, over 80% of the total demand for lithium is expected to come from the EV sector, with the metal seeing an eye-popping double-digit annual growth in its demand.
Apart from the above, a Stansberry Investor report from this July has also mentioned that the basic materials sector has, quite surprisingly for some, been able to jump by about 25% from January to May 2021. The gain has easily overtaken the return of the S&P 500 as well, being almost double the benchmark's index's return over the same timeframe. It has also been estimated that this sector in particular has managed to yield stable and positive returns at least since as far back as 2000, with a 7% annual return being quoted since then. This demonstrates not only a positive performance on part of this sector, to the joy of investors, but also a consistently positive performance, for the most part. Adding on to this is the fact that it has been reportedly stated by Bloomberg that the S&P 500 Materials Index has been able to perform well enough to earn it the title of the best sector on the market, just after the energy sector, as of this March. With shares soaring during the first few months of 2021 and commodity prices rising during the pandemic, the index went up by about 98%. In any case, the sector's performance is increasingly becoming hard to doubt.
While the basic materials sector soars, the entire hedge fund industry is still feeling the reverberations of the changing financial landscape. Its reputation has been tarnished in the last decade, during which its hedged returns couldn’t keep up with the unhedged returns of the market indices. On the other hand, Insider Monkey’s research was able to identify in advance a select group of hedge fund holdings that outperformed the S&P 500 ETFs by more than 124 percentage points since March 2017. Between March 2017 and July 2021, our monthly newsletter’s stock picks returned 186.1%, vs. 100.1% for the SPY. Our stock picks outperformed the market by more than 124 percentage points (see the details here). That’s why we believe hedge fund sentiment is an extremely useful indicator that investors should pay attention to. You can subscribe to our free newsletter on our homepage to receive our stories in your inbox.

Let's now look at the 10 Russell 2000 basic materials dividend stocks.
Our Methodology
We have used Insider Monkey's data of about 866 hedge funds alongside the Russell 2000 index to select small-cap basic materials dividend stocks that are more popular among hedge funds this year. The stocks also have mostly positive analysts' ratings and robust fundamentals, demonstrating their financial strength. Finally, we have mentioned the dividend yields and the number of hedge fund holders for each stock as well, ranking them from the lowest to the highest dividend yield.
Russell 2000 Basic Materials Dividend Stocks
10. FutureFuel Corp. (NYSE: FF)
Number of Hedge Fund Holders: 9 Dividend Yield: 2.4%
FutureFuel Corp. (NYSE: FF) is a manufacturer and seller of diversified chemical, bio-based fuel, and bio-based specialty chemical products in the US. The company ranks 10th on our list of Russell 2000 basic materials dividend stocks and operates through its Chemicals and Biofuels segments.
In the second quarter of 2021, FutureFuel Corp. (NYSE: FF) had an EPS of $0.08. The company's revenue of $ 74.12 million was up 56.3% year over year and beat the previous quarter's revenue of $41.52 million.
By the end of the first quarter of 2021, 9 hedge funds out of the 866 tracked by Insider Monkey held stakes in FutureFuel Corp. (NYSE: FF) worth roughly $60.7 million. This is compared to 10 hedge funds in the previous quarter with a total stake value of approximately $54.4 million.
Like Rio Tinto Group (NYSE: RIO), Freeport-McMoRan Inc. (NYSE: FCX), LyondellBasell Industries N.V. (NYSE: LYB), and International Paper Company (NYSE: IP), FutureFuel Corp. (NYSE: FF) is a good stock to invest in.
9. Cabot Corporation (NYSE: CBT)
Number of Hedge Fund Holders: 23 Dividend Yield: 2.6%
Cabot Corporation (NYSE: CBT) is a specialty chemicals and performance materials company. It ranks 9th on our list of Russell 2000 basic materials dividend stocks and operates through its Reinforcement Materials, Performance Chemicals, and Purification Solutions segments.
This July, JPMorgan's Jeffrey Zekauskas upgraded shares of Cabot Corporation (NYSE: CBT) from Neutral to Overweight. The analyst also has a $62 price target on the stock.
In the fiscal third quarter of 2021, Cabot Corporation (NYSE: CBT) had an EPS of $1.35, beating estimates by $0.17. The company's revenue of $917 million was up 77.03% year over year and beat estimates by $112.30 million. Cabot Corporation (NYSE: CBT) has gained 10.69% in the past 6 months and 24.50% year to date.
By the end of the first quarter of 2021, 23 hedge funds out of the 866 tracked by Insider Monkey held stakes in Cabot Corporation (NYSE: CBT) worth roughly $111 million. This is compared to 20 hedge funds in the previous quarter with a total stake value of approximately $106 million.
Like Rio Tinto Group (NYSE: RIO), Freeport-McMoRan Inc. (NYSE: FCX), LyondellBasell Industries N.V. (NYSE: LYB), and International Paper Company (NYSE: IP), Cabot Corporation (NYSE: CBT) is a good stock to invest in.
8. Oil-Dri Corporation of America (NYSE: ODC)
Number of Hedge Fund Holders: 4 Dividend Yield: 2.9%
Oil-Dri Corporation of America (NYSE: ODC) is a developer of sorbent products in the US and globally. The company operates through its Retail and Wholesale Products Group and Business to Business Products Group segments. It ranks 8th on our list of Russell 2000 basic materials dividend stocks.
In the fiscal third quarter of 2021, Oil-Dri Corporation of America (NYSE: ODC) had an EPS of $0.30. The company's revenue of $76.26 million was up 8.86% year over year and beat the previous quarter's revenue of $74.50 million. Oil-Dri Corporation of America (NYSE: ODC) has gained 3.44% year to date and 0.92% in the past year.
By the end of the first quarter of 2021, 4 hedge funds out of the 866 tracked by Insider Monkey held stakes in Oil-Dri Corporation of America (NYSE: ODC) worth roughly $29.5 million. This is compared to 4 hedge funds in the previous quarter with a total stake value of approximately $30.6 million.
Like Rio Tinto Group (NYSE: RIO), Freeport-McMoRan Inc. (NYSE: FCX), LyondellBasell Industries N.V. (NYSE: LYB), and International Paper Company (NYSE: IP), Oil-Dri Corporation of America (NYSE: ODC) is a good stock to invest in.
7. SunCoke Energy, Inc. (NYSE: SXC)
Number of Hedge Fund Holders: 22 Dividend Yield: 3.2%
SunCoke Energy, Inc. (NYSE: SXC) is an independent producer of coke in the US and Brazil. The company ranks 7th on our list of Russell 2000 basic materials dividend stocks and operates through three segments, namely the Domestic Coke, Brazil Coke, and Logistics segments. It provides metallurgical and thermal coal alongside handling and mixing services to its steel, coke, electric utility, coal producing, and other related customers.
Lucas Pipes, an analyst at B. Riley, this July raised his price target on shares of SunCoke Energy, Inc. (NYSE: SXC) from $9 to $10. The analyst also reiterated a Buy rating on the shares.
In the second quarter of 2021, SunCoke Energy, Inc. (NYSE: SXC) had an EPS of -$0.11, missing estimates by $0.20. The company's revenue of $364.30 million was up 7.78% year over year and beat estimates by $44.85 million. SunCoke Energy, Inc. (NYSE: SXC) has gained 18.21% in the past 6 months and 59.48% in the past year.
By the end of the first quarter of 2021, 22 hedge funds out of the 866 tracked by Insider Monkey held stakes in SunCoke Energy, Inc. (NYSE: SXC) worth roughly $87 million. This is compared to 19 hedge funds in the previous quarter with a total stake value of approximately $66 million.
Like Rio Tinto Group (NYSE: RIO), Freeport-McMoRan Inc. (NYSE: FCX), LyondellBasell Industries N.V. (NYSE: LYB), and International Paper Company (NYSE: IP), SunCoke Energy, Inc. (NYSE: SXC) is a good stock to invest in.
6. Glatfelter Corporation (NYSE: GLT)
Number of Hedge Fund Holders: 8 Dividend Yield: 3.4%
Glatfelter Corporation (NYSE: GLT) is a manufacturer of engineered materials for sale across the globe. The company has two segments, Composite Fibers, and Airlaid Materials. It ranks 6th on our list of Russell 2000 basic materials dividend stocks.
BMO Capital just this July upgraded shares of Glatfelter Corporation (NYSE: GLT) from Market Perform to Outperform. Analyst Mark Wilde, who pushed the upgrade, also holds an unchanged $17 price target on Glatfelter Corporation (NYSE: GLT) shares.
In the second quarter of 2021, Glatfelter Corporation (NYSE: GLT) had an EPS of $0.18, beating estimates by $0.04. The company's revenue of $244.91 million was up 13.29% year over year and beat estimates by $2.91 million.
By the end of the first quarter of 2021, 8 hedge funds out of the 866 tracked by Insider Monkey held stakes in Glatfelter Corporation (NYSE: GLT) worth roughly $30.7 million. This is compared to 7 hedge funds in the previous quarter with a total stake value of approximately $21.6 million.
Like Rio Tinto Group (NYSE: RIO), Freeport-McMoRan Inc. (NYSE: FCX), LyondellBasell Industries N.V. (NYSE: LYB), and International Paper Company (NYSE: IP), Glatfelter Corporation (NYSE: GLT) is a good stock to invest in.
Click to continue reading and see the 5 Russell 2000 Basic Materials Dividend Stocks to Buy.
Suggested articles:
Disclosure: None. 10 Russell 2000 Basic Materials Dividend Stocks to Buy is originally published on Insider Monkey.
CMP earnings call for the period ending June 30, 2021.
Here at Zacks, we focus on our proven ranking system, which places an emphasis on earnings estimates and estimate revisions, to find winning stocks. But we also understand that investors develop their own strategies, so we are constantly looking at the latest trends in value, growth, and momentum to find strong companies for our readers.
Of these, perhaps no stock market trend is more popular than value investing, which is a strategy that has proven to be successful in all sorts of market environments. Value investors use fundamental analysis and traditional valuation metrics to find stocks that they believe are being undervalued by the market at large.
Luckily, Zacks has developed its own Style Scores system in an effort to find stocks with specific traits. Value investors will be interested in the system's "Value" category. Stocks with both "A" grades in the Value category and high Zacks Ranks are among the strongest value stocks on the market right now.
One stock to keep an eye on is Rio Tinto (RIO). RIO is currently holding a Zacks Rank of #2 (Buy) and a Value grade of A. The stock holds a P/E ratio of 5.23, while its industry has an average P/E of 7.32. Over the past year, RIO's Forward P/E has been as high as 10.05 and as low as 5.02, with a median of 7.62.
Investors should also recognize that RIO has a P/B ratio of 1.70. The P/B is a method of comparing a stock's market value to its book value, which is defined as total assets minus total liabilities. RIO's current P/B looks attractive when compared to its industry's average P/B of 4. Within the past 52 weeks, RIO's P/B has been as high as 2.28 and as low as 1.58, with a median of 1.89.
Value investors will likely look at more than just these metrics, but the above data helps show that Rio Tinto is likely undervalued currently. And when considering the strength of its earnings outlook, RIO sticks out at as one of the market's strongest value stocks.
Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Rio Tinto PLC (RIO): Free Stock Analysis Report
To read this article on Zacks.com click here.
The Mosaic Company MOS recently announced sales volumes and revenues for July 2021 by business unit.
The Potash Segment recorded sales volume of 629,000 tons in May, down 15% from 743,000 tons in the year-ago period. Sales revenues were $191 million, up around 24% from $154 million in the prior-year period.
The Mosaic Fertilizantes segment’s sales volume inched down 0.3% to 1,197,000 tons from 1,201,000 tons last year. Sales revenues increased around 52% to $585 million from $385 million recorded last year.
The Phosphates segment recorded sales volume of 597,000 tons, down around 11.6% from 676,000 tons a year ago. Sales revenues in the segment were $407 million, up around 75% year over year from $233 million a year ago.
Shares of Mosaic have gained 88% in the past year compared with 53.6% rise of the industry.

Image Source: Zacks Investment Research
The company, in its last earnings call, stated that it expects strong agricultural trends to continue through the second half of 2021, driving demand for fertilizers. Grower economics remain attractive in most global growing regions on strong crop demand, affordable inputs and favorable weather, the company noted.
The company forecasts $90-$100 per ton improvement in average realized price in the Phosphates segment, sequentially, in the third quarter. For the Potash segment, $25-$35 per ton improvement in average realized prices is expected in the third quarter.
The Mosaic Company Price and Consensus

The Mosaic Company price-consensus-chart | The Mosaic Company Quote
Zacks Rank & Other Key Picks
Mosaic currently flaunts a Zacks Rank #1 (Strong Buy).
Some other top-ranked stocks in the basic materials space are Nucor Corporation NUE, Dow Inc. DOW and Cabot Corporation CBT.
Nucor has a projected earnings growth rate of around 489.2% for the current year. The company’s shares have surged 172.1% in a year. It currently flaunts a Zacks Rank #1. You can see the complete list of today’s Zacks #1 Rank stocks here.
Dow has an expected earnings growth rate of around 403.01% for the current year. The company’s shares have gained 43.2% in the past year. It currently carries a Zacks Rank #2 (Buy).
Cabot has an expected earnings growth rate of around 138.5% for the current fiscal. The company’s shares have rallied 37.6% in the past year. It currently holds a Zacks Rank #2.
Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Nucor Corporation (NUE): Free Stock Analysis Report
Dow Inc. (DOW): Free Stock Analysis Report
The Mosaic Company (MOS): Free Stock Analysis Report
Cabot Corporation (CBT): Free Stock Analysis Report
To read this article on Zacks.com click here.
By Melanie Burton and Kate Lamb
MELBOURNE (Reuters) – Australia's mining industry is bracing for a government inquiry that is expected to shed light on sexual harassment in the country's mineral-rich west, as the sector struggles with a dire skills shortage and low female representation.
Conditions at Western Australia's mining camps have worsened sexual harassment, critics say, and the issue has prompted the industry to take a stand against a culture they say has to change.
Major miners including BHP Group, Rio Tinto and Fortescue are among those expected to make submissions to the state government inquiry, which will make recommendations to West Australia's parliament in April 2022. Submissions close on Friday and become public next week.
Workers typically live at isolated "fly-in, fly-out" (FIFO) camps for a fortnight at a time in Western Australia's mining belt, the source of much of the country's economic prosperity.
Women make up roughly one in five FIFO workers and critics say recreation facilities have become hubs for drinking alcohol and created poor camp cultures that miners need to address.
"There are certain geographic and other issues that make FIFO camps a particular high risk area – part of that is the demographics that are on site," said Owen Whittle, a spokesperson for UnionsWA, which represents 30 workers groups and will make a submission to the inquiry.
Whittle says miners and contractors need to invest in site facilities and health and safety practices, particularly at smaller camps. He said sexual harassment needs to be seen as a systemic issue, rather than a series of unrelated incidents for the police to deal with.
"Often these (smaller) camps are poorly managed, the facilities are very poor. You might have little more than a wet mess and a rundown gym in terms of recreation facilities on site," he said, referring to mess facilities that serve alcohol.
"We need to put a duty on the camp operators and the miners and all the resource companies to…prevent harm in these workplaces."
In a 2020 report, the Australian Human Rights Commission inquiry into sexual harassment found that 74% of women in the mining industry had experienced some form of sexual harassment in the past five years, partly due to the gender imbalance.
CULTURAL ISSUES
A young woman formerly employed at one of Australia’s largest mining companies told Reuters that while her team was "welcoming, sensitive and conscious," that attitude was not always replicated underground.
"If you are a new employee and there are already about 8-10 male miners down there, you tend to sort of accept a few things here or there that you usually wouldn't," said the woman, who declined to be named. "Like swearing, or throwing the c-word around like it's nothing."
In her experience her male colleagues were largely respectful to her but she said when there is a group of them that "culture perpetuates."
Australia's three biggest miners, BHP, Rio Tinto and Fortescue, did not have an immediate response to requests for further comment but have previously spoken about measures they are taking to address the issues, including efforts to increase women in their workforces.
BHP has been targeting a 50-50 gender split by 2025. The percentage of women has risen to 26.5% up from 17.6% since mid-2016.
Rio is striving to increase the representation of women by 2 percentage points each year. It rose by 0.9% to 21.0% in the first half, hiring 1,270 women, 32% of all hires. It has also launched an initiative to address sexual harassment and help it retain women.
"As an industry, we must and can do more to ensure we have a diverse workforce that is reflective of our community and foster a workplace culture that truly embraces diversity and inclusiveness," Elizabeth Gaines, Fortescue Chief Executive, said last week.
At the mining industry's biggest annual conference in the outback town of Kalgoorlie last week, Gaines noted she had improved the event's gender diversity: women made up four out of 56 speakers, up from the three last year.
"It is clear that the industry still has some work to do in this regard," she said at the conference.
(Reporting by Melanie Burton; Editing by Sam Holmes)
By Sonali Paul and Melanie Burton
MELBOURNE (Reuters) – Expectations are growing that BHP Group Ltd will deliver a verdict on the future of its petroleum business at its results next week, as it comes under increasing pressure to cut its fossil fuel footprint.
The world's biggest miner has been facing calls to detail how and when it will exit fossil fuels, with activist investor Market Forces filing a resolution on the topic this week for annual meetings in October and November.
BHP's decision this month to approve $802 million in development spending on oil projects in the U.S. Gulf of Mexico – just days before a new report that issued dire warnings about human contribution to climate change – has only ratcheted up pressure from some investors.
"It's clear something is brewing," said Simon Mawhinney, Chief Investment Officer at Allan Gray Australia.
BHP declined to comment on market speculation.
Analysts value BHP's petroleum business, made up of assets in Australia, the Gulf of Mexico, Trinidad and Tobago and Algeria, at $10 billion to $17 billion. The division contributed 5% of BHP's underlying earnings of $14.7 billion in the first half to end-December, compared with 70% for iron ore.
Investors are split on their fit within BHP's portfolio, especially as the company focuses on new economy materials such as copper, nickel and potash.
An exit from petroleum would constitute "a major shift" in BHP's environmental, social and governance (ESG) credentials and overall strategy towards fossil fuels, Morgan Stanley analyst Rahul Anand said in a recent note.
AUSTRALIA AND THE REST
BHP's late-life, mainly low-return energy assets in Australia are seen as particularly ripe for a sale amid high oil and gas prices.
"For BHP, if you look at its Australian (energy) assets, if they could exit those in a meaningful way for something approximating value, that would be a good outcome," said Brenton Saunders, a portfolio manager with shareholder Pendal Group.
Credit Suisse and Citi value the Australian energy assets – including the Bass Strait, Northwest Shelf LNG and the Scarborough gas field – at $3 billion to $5 billion.
Woodside Petroleum Ltd is seen as the most logical buyer as they would boost its free cash flow and increase its stakes in key projects, although not all investors favour such a tie-up given the asset mix and likely need for an equity raising.
Woodside declined to comment.
BHP would also have to take a discount on any sale given some heavy decommissioning liabilities, said Credit Suisse analyst Saul Kavonic, although a sale could boost its ESG rating and attract new shareholders.
"BHP could sell these for discounts but still increase share value though a re-rating on the rest of their business," he said.
Elsewhere, investors say BHP's petroleum assets are more attractive.
The most valuable are its stakes in oil fields in the Gulf of Mexico, valued at $10.4 billion by Wood Mackenzie, which made up about 25% of the company's 103 million barrels of oil equivalent output the year to June 2021.
"The rest of the portfolio, there are parts that are high growth, high returning. They've done a lot of work on them and shareholders have had to wear some of the bad times. They are good assets," said Pendal Group's Saunders.
BHP is due to deliver its annual results on Tuesday at 0700 GMT.
(Reporting by Melanie Burton and Sonali Paul; editing by Richard Pullin)
Edmonton, Alberta–(Newsfile Corp. – August 13, 2021) – Grizzly Discoveries Inc. (TSXV: GZD) (OTCQB: GZDIF) (FSE: G6H) ("Grizzly" or the "Company") is pleased to announce the results of the Company's annual general and special meeting of shareholders held on August 9, 2021 in Edmonton, Alberta (the "Meeting").
The total number of votes represented at the Meeting was 32,877,764, being 35.24% of the total issued and outstanding common shares of the Company. Shareholders voted in favour of all matters considered at the Meeting. All matters considered at the Meeting are described in more detail in the Company's management information circular dated July 2, 2021, which was mailed to shareholders of the Company and is available on SEDAR at www.sedar.com.
Included in the business of the Meeting, shareholders authorized amended and restated by-laws of the Company that had been approved by the Board of Directors on July 2, 2021, replacing the Company's previous by-laws.
More information about the business of the Meeting is available in the Company's Management Information Circular dated July 2, 2021, and a copy of the amended and restated by-laws of the Company are available on SEDAR.
ABOUT GRIZZLY DISCOVERIES INC.
Grizzly is a diversified Canadian mineral exploration company with its primary listing on the TSX Venture Exchange, with 90 million shares issued, focused on developing its over 156,000 acres of precious and base metals properties in southeastern British Columbia. Grizzly is run by a highly experienced junior resource sector management team, who have a track record of advancing exploration projects from early exploration stage through to feasibility stage.
On behalf of the Board,
GRIZZLY DISCOVERIES INC.
Brian Testo, CEO, President
Tel: 780 693 2242
For further information, please visit our website at www.grizzlydiscoveries.com or contact:
Chris Beltgens
Corporate Development
Tel: 604 347 9535
Email: cbeltgens@grizzlydiscoveries.com
Neither the TSX Venture Exchange nor its Regulation Services Provider (as that term is defined in the policies of the TSX Venture Exchange) accepts responsibility for the adequacy or accuracy of this release.

To view the source version of this press release, please visit https://www.newsfilecorp.com/release/93121
Compass Minerals (CMP) came out with a quarterly loss of $0.49 per share versus the Zacks Consensus Estimate of a loss of $0.06. This compares to earnings of $0.04 per share a year ago. These figures are adjusted for non-recurring items.
This quarterly report represents an earnings surprise of -716.67%. A quarter ago, it was expected that this minerals producer would post earnings of $0.72 per share when it actually produced earnings of $0.95, delivering a surprise of 31.94%.
Over the last four quarters, the company has surpassed consensus EPS estimates just once.
Compass, which belongs to the Zacks Chemical – Diversified industry, posted revenues of $199.4 million for the quarter ended June 2021, surpassing the Zacks Consensus Estimate by 10.44%. This compares to year-ago revenues of $256.1 million. The company has topped consensus revenue estimates just once over the last four quarters.
The sustainability of the stock's immediate price movement based on the recently-released numbers and future earnings expectations will mostly depend on management's commentary on the earnings call.
Compass shares have added about 11.5% since the beginning of the year versus the S&P 500's gain of 18.8%.
What's Next for Compass?
While Compass has underperformed the market so far this year, the question that comes to investors' minds is: what's next for the stock?
There are no easy answers to this key question, but one reliable measure that can help investors address this is the company's earnings outlook. Not only does this include current consensus earnings expectations for the coming quarter(s), but also how these expectations have changed lately.
Empirical research shows a strong correlation between near-term stock movements and trends in earnings estimate revisions. Investors can track such revisions by themselves or rely on a tried-and-tested rating tool like the Zacks Rank, which has an impressive track record of harnessing the power of earnings estimate revisions.
Ahead of this earnings release, the estimate revisions trend for Compass was unfavorable. While the magnitude and direction of estimate revisions could change following the company's just-released earnings report, the current status translates into a Zacks Rank #4 (Sell) for the stock. So, the shares are expected to underperform the market in the near future. You can see the complete list of today's Zacks #1 Rank (Strong Buy) stocks here.
It will be interesting to see how estimates for the coming quarters and current fiscal year change in the days ahead. The current consensus EPS estimate is $0.21 on $205 million in revenues for the coming quarter and $2.15 on $1.2 billion in revenues for the current fiscal year.
Investors should be mindful of the fact that the outlook for the industry can have a material impact on the performance of the stock as well. In terms of the Zacks Industry Rank, Chemical – Diversified is currently in the top 48% of the 250 plus Zacks industries. Our research shows that the top 50% of the Zacks-ranked industries outperform the bottom 50% by a factor of more than 2 to 1.
Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Compass Minerals International, Inc. (CMP) : Free Stock Analysis Report
To read this article on Zacks.com click here.
Zacks Investment Research
For those looking to find strong Basic Materials stocks, it is prudent to search for companies in the group that are outperforming their peers. Has BHP Group Limited Sponsored (BHP) been one of those stocks this year? A quick glance at the company's year-to-date performance in comparison to the rest of the Basic Materials sector should help us answer this question.
BHP Group Limited Sponsored is a member of the Basic Materials sector. This group includes 251 individual stocks and currently holds a Zacks Sector Rank of #4. The Zacks Sector Rank includes 16 different groups and is listed in order from best to worst in terms of the average Zacks Rank of the individual companies within each of these sectors.
The Zacks Rank is a proven system that emphasizes earnings estimates and estimate revisions, highlighting a variety of stocks that are displaying the right characteristics to beat the market over the next one to three months. BHP is currently sporting a Zacks Rank of #2 (Buy).
Over the past 90 days, the Zacks Consensus Estimate for BHP's full-year earnings has moved 12.52% higher. This means that analyst sentiment is stronger and the stock's earnings outlook is improving.
According to our latest data, BHP has moved about 19.18% on a year-to-date basis. At the same time, Basic Materials stocks have gained an average of 16.73%. This means that BHP Group Limited Sponsored is performing better than its sector in terms of year-to-date returns.
Looking more specifically, BHP belongs to the Mining – Miscellaneous industry, a group that includes 47 individual stocks and currently sits at #207 in the Zacks Industry Rank. This group has gained an average of 17.48% so far this year, so BHP is performing better in this area.
BHP will likely be looking to continue its solid performance, so investors interested in Basic Materials stocks should continue to pay close attention to the company.
Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
BHP Group Limited Sponsored ADR (BHP) : Free Stock Analysis Report
To read this article on Zacks.com click here.
TAMPA, FL / ACCESSWIRE / August 12, 2021 / The Mosaic Company (NYSE:MOS) announced its July 2021 sales revenue and volumes by business unit.
|
Potash(1) |
July 2021 |
July 2020 |
||||||
|
Sales volumes in thousands of tonnes(2) |
629 |
743 |
||||||
|
Sales revenue in millions |
$ |
191 |
$ |
154 |
||||
|
Mosaic Fertilizantes(1) |
July 2021 |
July 2020 |
||||||
|
Sales volumes in thousands of tonnes(2) |
1,197 |
1,201 |
||||||
|
Sales revenue in millions |
$ |
585 |
$ |
385 |
||||
|
Phosphates(1) |
July 2021 |
July 2020 |
||||||
|
Sales volumes in thousands of tonnes(2) |
597 |
676 |
||||||
|
Sales revenue in millions |
$ |
407 |
$ |
233 |
||||
(1)The revenue and tonnes presented are sales as recognized in the month and do not reflect current market conditions due to the delays between pricing and revenue recognition.
(2)Tonnes = finished product tonnes
About The Mosaic Company
The Mosaic Company is one of the world's leading producers and marketers of concentrated phosphate and potash crop nutrients. Mosaic is a single source provider of phosphates and potash fertilizers and feed ingredients for the global agriculture industry. More information on the company is available at www.mosaicco.com.
|
The Mosaic Company Contacts |
|
|
Media: |
Investors: |
|
Ben Pratt, 813-775-4206 |
Laura Gagnon, 813-775-4214 or |
|
Paul Massoud, 813-775-4260 |
|
SOURCE: The Mosaic Company
View source version on accesswire.com:
https://www.accesswire.com/659543/Mosaic-Announces-July-2021-Sales-Revenue-and-Volumes
Aug 12 (Reuters) – The following are the top stories in the Financial Times. Reuters has not verified these stories and does not vouch for their accuracy.
Headlines
– BHP urged to run down not sell its fossil fuel assets https://on.ft.com/3AuLENC
– UK government urged to aid universities struggling with record student numbers https://on.ft.com/3lWfx5q
– Johnson poised to backtrack on mid-2030s gas boiler ban https://on.ft.com/3jOCXY0
– Germany arrests Briton on suspicion of spying for Russia https://on.ft.com/2Xp7Pa5
Overview
– BHP Group Plc has been urged to run down rather than divest its fossil assets by shareholder activist group Market Forces, to meet the goals of the Paris climate agreement.
– Education leaders have called on the UK government for more support to universities, as higher education institutions are struggling to accommodate a larger number of students following a surge in top A-level marks.
– Prime Minister Boris Johnson is set to cut down plans to ban the sale of new gas boilers in the UK from mid-2030, over concerns from ministers and Conservative Party lawmakers about the cost to consumers of transitioning to net zero emissions.
– German prosecutors on Wednesday said that they have arrested a British man working at the UK embassy in Berlin on suspicion of passing documents to the Russian intelligence service.
(Compiled by Bengaluru newsroom)
CF Industries Holdings, Inc. CF recently announced a memorandum of understanding (MOU) with Mitsui & Co. to jointly explore the development of blue ammonia projects in the United States.
Per the MOU, the companies will carry out various preliminary feasibility studies on blue ammonia production in the United States. The areas of exploration include establishing blue ammonia supply and supply chain infrastructure, transportation and storage of carbon dioxide, expected environmental impacts, and blue ammonia economics and its probable marketing opportunities in Japan and other countries.
CF Industries noted that both companies share the common belief that blue ammonia is a key element in boosting transition to clean energy across the globe and the demand for the clean energy source will grow in the near future. The collaboration will leverage the outstanding expertise of both companies to explore the development of the capacity of blue ammonia and meet the growing demand.
Shares of CF Industries have rallied 38.1% over a year, underperforming the industry’s 55.3% rise.

Image Source: Zacks Investment Research
In the second quarter, the company recorded earnings of $1.14 per share, missing the Zacks Consensus Estimate of $1.64 per share. Its net sales of $1,588 million increased 32% from the year-ago quarter, but missed the Zacks Consensus Estimate of $1,718.7 million.
CF Industries expects nitrogen pricing to be positive as higher economic activities, the need to replenish coarse grains stocks globally and increased energy prices in Europe and Asia are expected to sustain a tighter global nitrogen supply and demand balance into 2023. The global demand for nitrogen is also strong, the company noted. It expects strong global demand for coarse grains to contribute to sustained low global stocks into 2022, supporting strong nitrogen demand in the upcoming years. Higher economic activities have also contributed to the rise in industrial consumption of nitrogen products.
CF Industries Holdings, Inc. Price and Consensus

CF Industries Holdings, Inc. price-consensus-chart | CF Industries Holdings, Inc. Quote
Zacks Rank & Stocks to Consider
Currently, CF Industries carries a Zacks Rank #3 (Hold).
Better-ranked stocks in the basic materials space include Intrepid Potash, Inc. IPI, The Mosaic Company MOS and LyondellBasell Industries N.V. LYB, each sporting a Zacks Rank #1 (Strong Buy). You can see the complete list of today’s Zacks #1 Rank stocks here.
Intrepid has a projected earnings growth rate of 287.5% for the current year. The company’s shares have shot up 231.9% over a year.
Mosaic has a projected earnings growth rate of 413% for the current year. The company’s shares have risen 96% over a year.
LyondellBasell has an expected earnings growth rate of around 254.6% for the current year. The company’s shares have gained roughly 54% in the past year.
Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
CF Industries Holdings, Inc. (CF) : Free Stock Analysis Report
The Mosaic Company (MOS) : Free Stock Analysis Report
LyondellBasell Industries N.V. (LYB) : Free Stock Analysis Report
Intrepid Potash, Inc (IPI) : Free Stock Analysis Report
To read this article on Zacks.com click here.
VANCOUVER, BC, Aug. 11, 2021 /CNW/ – Trading resumes in:
Company: Sego Resources Inc.
TSX-Venture Symbol: SGZ
All Issues: Yes
Resumption (ET): 12:15 PM
IIROC can make a decision to impose a temporary suspension (halt) of trading in a security of a publicly-listed company. Trading halts are implemented to ensure a fair and orderly market. IIROC is the national self-regulatory organization which oversees all investment dealers and trading activity on debt and equity marketplaces in Canada.
SOURCE Investment Industry Regulatory Organization of Canada (IIROC) – Halts/Resumptions
“Cision”
Cision
View original content: http://www.newswire.ca/en/releases/archive/August2021/11/c2876.html
When a single insider purchases stock, it is typically not a major deal. However, when multiple insiders purchase stock, like in BHP Group's (ASX:BHP) instance, it's good news for shareholders.
Although we don't think shareholders should simply follow insider transactions, we would consider it foolish to ignore insider transactions altogether.
Check out our latest analysis for BHP Group
BHP Group Insider Transactions Over The Last Year
The Independent Non-Executive Director Xiaoqun Clever made the biggest insider purchase in the last 12 months. That single transaction was for AU$68k worth of shares at a price of AU$34.05 each. Even though the purchase was made at a significantly lower price than the recent price (AU$52.52), we still think insider buying is a positive. Because the shares were purchased at a lower price, this particular buy doesn't tell us much about how insiders feel about the current share price.
Happily, we note that in the last year insiders paid AU$70k for 2.04k shares. But insiders sold 16.00 shares worth AU$820. Overall, BHP Group insiders were net buyers during the last year. The chart below shows insider transactions (by companies and individuals) over the last year. If you want to know exactly who sold, for how much, and when, simply click on the graph below!

BHP Group is not the only stock that insiders are buying. For those who like to find winning investments this free list of growing companies with recent insider purchasing, could be just the ticket.
Have BHP Group Insiders Traded Recently?
There was only a small bit of insider buying, worth AU$2.1k, in the last three months. Overall, we don't think these recent trades are particularly informative, one way or the other.
Does BHP Group Boast High Insider Ownership?
Another way to test the alignment between the leaders of a company and other shareholders is to look at how many shares they own. I reckon it's a good sign if insiders own a significant number of shares in the company. Insiders own 0.03% of BHP Group shares, worth about AU$77m. This level of insider ownership is good but just short of being particularly stand-out. It certainly does suggest a reasonable degree of alignment.
So What Does This Data Suggest About BHP Group Insiders?
Insider purchases may have been minimal, in the last three months, but there was no selling at all. That said, the purchases were not large. On a brighter note, the transactions over the last year are encouraging. Overall we don't see anything to make us think BHP Group insiders are doubting the company, and they do own shares. While we like knowing what's going on with the insider's ownership and transactions, we make sure to also consider what risks are facing a stock before making any investment decision. At Simply Wall St, we've found that BHP Group has 2 warning signs (1 doesn't sit too well with us!) that deserve your attention before going any further with your analysis.
Of course BHP Group may not be the best stock to buy. So you may wish to see this free collection of high quality companies.
For the purposes of this article, insiders are those individuals who report their transactions to the relevant regulatory body. We currently account for open market transactions and private dispositions, but not derivative transactions.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.
(Bloomberg) — BHP Group, the world’s top miner, should abandon plans for multi-billion dollar sales of fossil fuels assets and instead responsibly close down the operations, according to an environmental campaign group.
A proposal tabled on behalf of about 100 small investors by Market Forces, which coordinates groups of shareholders on climate issues, calls on the company to wind down production in line with international targets to cut greenhouse gas emissions, and to focus on helping communities to find alternative jobs.
“By providing a leading example of responsibly managing down fossil fuel assets, BHP can preserve and realize the genuine value that exists in these assets, align with global climate goals, and support its workers in the transition to a decarbonized economy,” the group said in a statement. Market Forces and the BHP investors have tabled resolutions to be considered at the company’s annual meeting in Australia later this year.
BHP’s board will set out a response ahead of the meeting, the company said in a statement Wednesday. The investors hold less than 0.01% of BHP’s Australia-listed entity and about 0.006% of the combined group, which includes the miner’s London-traded shares, according to the statement.
BHP is considering an exit from the oil and gas sector and reviewing options including a trade sale, people familiar with the matter said last month. The producer in June agreed to sell its one-third share in a Colombian coal mine and is also progressing plans to offload a thermal coal operation and some metallurgical coal assets in Australia.
Activists who previously had urged the biggest miners and oil majors to rid their portfolios of fossil fuels operations are increasingly changing approach, in recognition that assets are often sold to smaller producers or government-backed firms that operate with far less transparency and typically seek to boost volumes.
While shareholder resolutions seldom win large support, they’re among tools being used by small campaign groups to pressure companies. Lawsuits have been effective too, with Royal Dutch Shell Plc ordered to slash emissions faster than planned in a recent ruling and Australia’s government instructed to consider climate change in mine approvals.
“There’s an increasingly deep and sophisticated understanding of the steps big companies and their investors need to take to play their part in bringing down emissions,” said Will van de Pol, a campaigner at Australia-based Market Forces. “Companies and investors can no longer get away with green-washing and shirking their responsibilities.”
Read more: BP Cleans Image With Oil Asset Sales While Emissions Stay Behind
BP Plc is among firms that have faced criticism for pursuing divestment deals that will help the company meet its own net-zero goals, though likely won’t result in lower emissions from the assets that have been sold.
“While divestment addresses stranded asset risk exposure, it fails to manage the reputational risk associated with avoiding responsibility for employee transition support and site rehabilitation,” Market Forces said in its statement.
More stories like this are available on bloomberg.com
Subscribe now to stay ahead with the most trusted business news source.
©2021 Bloomberg L.P.
VANCOUVER, British Columbia, Aug. 11, 2021 (GLOBE NEWSWIRE) — Search Minerals Inc. (TSXV: SMY | OTCQB: SHCMF) (“Search” or the “Company”) is pleased to announce that it has entered into a non-binding letter of intent (“LOI”) to purchase a 2.5% Net Smelter Royalty (“NSR”) from B&A Minerals Limited (“B&A”) for 15,000,000 common shares in the share capital of the Company. The transaction will also include some property transfers between the interested parties. The 15,000,000 common shares will be restricted and released over 24 months, with 25% being released every 6 months following the signing of the definitive agreement. The parties will now start negotiating a definitive agreement for the proposed transactions which, once signed, will supersede the LOI.
Net Smelter Royalty
B&A current holds a 3% NSR Royalty (“Royalty”) over the licenses contained in a large portion of the Company’s Critical Rare Earth Element District in SE Labrador. Upon closing of the transactions contemplated in the LOI, B&A will retain 0.5% NSR on the remaining consolidated 3 licenses including the Foxtrot project, along with our prospects of Fox Meadow, Silver Fox, Awesome Fox and up to 20 other prospects. The Company had the option to purchase 2% of the Royalty for $2,000,000 as per the 2009 B&A Mining Option Agreement (“Option Agreement”). Pursuant to the terms of the LOI Search will exercise that right along with the purchase of an additional 0.5% of the Royalty.
Also, for greater certainty, the 2009 Mining Option Agreement between B&A and Search will, once the definitive agreement is signed, be fully discharged without any further existing or future contractual obligations.
Property Transfers
As part of the Royalty purchase, B&A and Search have agreed to transfer some licenses between the interested parties. Please see attached map which shows the claims to be transferred to each applicable party.
B&A and associates will transfer the following Licenses which are in the proximity of the Company’s Fox Meadow prospect: Fox Meadow area (027318M, 032539M, part of 027599M and part of 027429M) and Deep Fox area (027447M). These licenses will be included in the updated NSR registration and be subject to the existing 0.5% NSR. Search will grant B&A the quarry/gem rights on the above 4 licenses transferred in the Fox Meadow area only after Search has explored/developed those licenses in exchange for a 3% NSR or similar form of royalty.
Search will transfer license 024083M to B&A and receive a 0.5% NSR royalty. This license does not form any part of our Critical Rare Earth Element District.
Greg Andrews, President and CEO states: “We believe the reduction of the Royalty, will provide flexibility with our future discussions regarding offtake agreements and funding for the projects. Our immediate goal remains to advance our Critical Rare Earth Element District to production. This will require (a) advancing our DEEP FOX project to a measured and indicated resource, (b) provide engineering and economic studies such as Preliminary Economic Assessments (“PEA”) and Feasibility Studies and (c) develop and submit an Environmental Assessment report to initiate the environmental and permitting process for DEEP FOX and FOXTROT. The reduction of the NSR will be included in the upcoming PEA.”
Corporate Developments:
On April 12, 2021, the Company put into effect a blackout on trading of the Company’s shares for the management and board of directors of the Company and InCoR Holdings (the Company’s controlling shareholder). This blackout is now lifted.
About Search Minerals Inc.
Led by a proven management team and board of directors, Search is focused on finding and developing Critical Rare Earths Elements (CREE), Zirconium (Zr) and Hafnium (Hf) resources within the emerging Port Hope Simpson – St. Lewis CREE District of South East Labrador. The Company controls a belt 63 km long and 2 km wide and is road accessible, on tidewater, and located within 3 local communities. Search has completed a preliminary economic assessment report for FOXTROT, and a resource estimate for DEEP FOX. Search is also working on three exploration prospects along the belt which include: FOX MEADOW, SILVER FOX and AWESOME FOX.
Search has continued to optimize our patented Direct Extraction Process technology with the generous support from the Department of Tourism, Culture, Industry and Innovation, Government of Newfoundland and Labrador, and from the Atlantic Canada Opportunity Agency. We have completed two pilot plant operations and produced highly purified mixed rare earth carbonate concentrate and mixed REO concentrate for separation and refining.
For further information, please contact:
Greg Andrews
President and CEO
Tel: 604-998-3432
E-mail: info@searchminerals.ca
Neither the TSX Venture Exchange nor its Regulation Services Provider (as that term is defined in the policies of the TSX Venture Exchange) accepts responsibility for the adequacy or accuracy of this release.
Cautionary Statement Regarding “Forward-Looking” Statements:
Except for the statements of historical fact, this news release contains "forward-looking information" within the meaning of the applicable Canadian securities legislation that is based on expectations, estimates and projections as at the date of this news release. "Forward-looking information" in this news release includes information about the Company’s proposed exploration programs described herein, and other forward-looking information. Factors that could cause actual results to differ materially from those described in such forward-looking information include, but are not limited to, the inability to obtain the necessary resources to complete the exploration programs and poor exploration results.
The forward-looking information in this news release reflects the current expectations, assumptions and/or beliefs of the Company based on information currently available to the Company. In connection with the forward-looking information contained in this news release, the Company has made assumptions about the Company's financial condition and development plans do not change as a result of unforeseen events, and that the Company will receive all required regulatory approvals.
Although the Company believes that the assumptions inherent in the forward-looking information are reasonable, forward-looking information is not a guarantee of future performance and accordingly undue reliance should not be put on such information due to the inherent uncertainty therein. The Company does not assume any obligation to update the forward-looking statements, or to update the reasons why actual results could differ from those reflected in the forward-looking statements, unless and until required by applicable securities laws. Additional information identifying risks and uncertainties is contained in the Company's filings with the Canadian securities regulators, which filings are available at www.sedar.com.

The partnership commits to opening five local food pantries over the next five years
TAMPA, FL / ACCESSWIRE / August 11, 2021 / The Tampa Bay Buccaneers and The Mosaic Company (NYSE:MOS) today announced a partnership to tackle hunger in Tampa Bay by opening five food pantries in the region over the next five years. The current Super Bowl Champions and Mosaic represent two local leaders with a shared commitment to support the Tampa Bay community. The new partnership seeks to enrich the lives of families in our region and is inspired by Mosaic's mission and passion to address food insecurity, and the Buccaneers extensive community platform to drive social change and empower youth.
"Mosaic has a long history of supporting the communities in which we operate – and where our employees work and live," said Joc O'Rourke, President and CEO of The Mosaic Company. "This partnership with the Tampa Bay Buccaneers represents our continued commitment to help those in need by removing barriers for individuals to thrive and succeed. By improving access to healthy and nutritious food, we are helping to fuel better learning, development and overall wellness – components critical for future success."
The first pantry, which is slated to open in October, will be located at Broward Elementary School in Seminole Heights. The pantry will serve the approximately 300 families in the area, helping children and their families have access to a variety of foods, including perishable and non-perishable options. One in four children in Tampa Bay are food insecure – a number that is even higher in certain areas throughout the region.
"The Buccaneers have always been committed to giving back to the Tampa Bay area by finding ways to provide the resources necessary to improve our communities most in need," said Brian Ford, Chief Operating Officer of the Tampa Bay Buccaneers. "This partnership with Mosaic is truly unique because it is specifically focused on making an even greater impact in the area of food insecurity for so many in our region. We believe everyone deserves a level playing field and are excited to partner on this important initiative that will impact so many children and families here locally."
In addition to the Buccaneers' ongoing initiatives to drive social change, in 2020 the Glazer family, owners of the franchise, donated five million meals to Feeding Tampa Bay toward pandemic relief.
The Buccaneers and Mosaic will partner with Feeding Tampa Bay, part of the Feeding America network, to build and manage the pantries. As part of the agreement, both the Bucs and Mosaic will be donating $10 each, per tackle during the team's 2021 regular season to Feeding Tampa Bay through the Tackling Hunger Fueled by Mosaic program. This commitment is the next step in Mosaic's long-term partnership with Feeding Tampa Bay. Since 2010, Mosaic has donated over $800,000 toward hunger relief in Tampa Bay through the partnership, including weekend backpacks for children, mobile food pantry expansion, warehouse improvements, purchasing much needed equipment including vehicles, among other capital expenses. Across the globe, Mosaic, The Mosaic Company Foundation, and The Mosaic Institute in Brazil in 2020 donated more than $14 million toward community investments, including nearly $2 million in pandemic aid with most of the aid supporting food programs around the world.
About Tampa Bay Buccaneers
The World Champion Tampa Bay Buccaneers are entering their 46th season as members of the National Football League and compete in the National Football Conference's South Division. They were purchased by the late Malcolm Glazer in 1995 and are currently owned by the Glazer Family. Established in 1976, the Buccaneers have totaled six division championships, two conference championships and two Super Bowl championships, including Super Bowl LV in 2021. The Buccaneers are also very active in the community, with the Tampa Bay Buccaneers Foundation and the Glazer Vision Foundation. For more information, visit www.buccaneers.com.
About The Mosaic Company
The Mosaic Company is one of the world's leading producers and marketers of concentrated phosphate and potash crop nutrients. Mosaic is a single-source provider of phosphate and potash fertilizers and feed ingredients for the global agriculture industry. More information on the company is available at www.mosaicco.com.
Media
Ben Pratt
The Mosaic Company
813-775-4206
benjamin.pratt@mosaicco.com
Nelson Luis
Tampa Bay Buccaneers
813-554-1314
Nluis@buccaneers.nfl.com
Investors
Laura Gagnon
The Mosaic Company
813-775-4214
investor@mosaicco.com
SOURCE: The Mosaic Company
View source version on accesswire.com:
https://www.accesswire.com/659259/The-Mosaic-Company-The-Tampa-Bay-Buccaneers-and-Mosaic-Team-Up-To-Tackle-Hunger-in-Tampa-Bay
Intrepid Potash (NYSE:IPI) has had a great run on the share market with its stock up by a significant 53% over the last three months. We wonder if and what role the company's financials play in that price change as a company's long-term fundamentals usually dictate market outcomes. Particularly, we will be paying attention to Intrepid Potash's ROE today.
ROE or return on equity is a useful tool to assess how effectively a company can generate returns on the investment it received from its shareholders. In simpler terms, it measures the profitability of a company in relation to shareholder's equity.
Check out our latest analysis for Intrepid Potash
How To Calculate Return On Equity?
ROE can be calculated by using the formula:
Return on Equity = Net Profit (from continuing operations) ÷ Shareholders' Equity
So, based on the above formula, the ROE for Intrepid Potash is:
2.5% = US$11m ÷ US$435m (Based on the trailing twelve months to June 2021).
The 'return' refers to a company's earnings over the last year. That means that for every $1 worth of shareholders' equity, the company generated $0.03 in profit.
Why Is ROE Important For Earnings Growth?
Thus far, we have learned that ROE measures how efficiently a company is generating its profits. Depending on how much of these profits the company reinvests or "retains", and how effectively it does so, we are then able to assess a company’s earnings growth potential. Assuming everything else remains unchanged, the higher the ROE and profit retention, the higher the growth rate of a company compared to companies that don't necessarily bear these characteristics.
Intrepid Potash's Earnings Growth And 2.5% ROE
It is hard to argue that Intrepid Potash's ROE is much good in and of itself. Even compared to the average industry ROE of 13%, the company's ROE is quite dismal. In spite of this, Intrepid Potash was able to grow its net income considerably, at a rate of 84% in the last five years. We reckon that there could be other factors at play here. Such as – high earnings retention or an efficient management in place.
We then compared Intrepid Potash's net income growth with the industry and we're pleased to see that the company's growth figure is higher when compared with the industry which has a growth rate of 3.4% in the same period.

The basis for attaching value to a company is, to a great extent, tied to its earnings growth. The investor should try to establish if the expected growth or decline in earnings, whichever the case may be, is priced in. By doing so, they will have an idea if the stock is headed into clear blue waters or if swampy waters await. Has the market priced in the future outlook for IPI? You can find out in our latest intrinsic value infographic research report.
Is Intrepid Potash Using Its Retained Earnings Effectively?
Conclusion
Overall, we feel that Intrepid Potash certainly does have some positive factors to consider. Even in spite of the low rate of return, the company has posted impressive earnings growth as a result of reinvesting heavily into its business. Having said that, the company's earnings growth is expected to slow down, as forecasted in the current analyst estimates. To know more about the latest analysts predictions for the company, check out this visualization of analyst forecasts for the company.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.
(Bloomberg) — BHP Group and union leaders at the Escondida complex in Chile are getting closer to a wage deal that would avert a strike at the world’s biggest copper mine.
Negotiators asked labor authorities for a one-day extension in a mediation process to continue working toward an agreement that could be put to workers Tuesday. According to the union, the breakthrough came after BHP acceded to some demands. On Friday, the Melbourne-based company warned that it wouldn’t improve the offer during a strike.
“During the course of the night, conversations between the parties will continue to close an agreement that will then be presented by Union No. 1 to its members,” BHP said in a statement late Monday.
Avoiding a stoppage at a mine that accounts for about 5% of global copper production would ease tensions over tightening supplies at a time when trillions of dollars in government stimulus fuel demand for industrial metals. In 2017, the same union staged a 44-day stoppage.
A deal at Escondida would also ease labor tensions in Chile after workers at a mine owned by JX Nippon Mining & Metals opted to walk off the job Tuesday when their talks with management collapsed.
At a third copper mine in Chile, Codelco’s Andina, the two sides agreed to extend talks to allow workers to vote on a new proposal, the result of which will be known Wednesday.
Surging producer profits are emboldening mine workers, with host nations also looking at ratcheting up taxes to help resolve inequalities exacerbated by the pandemic. At the same time, companies are striving to keep labor costs in check in a cyclical business and as ore quality deteriorates and input prices start to rise.
(Adds chart)
More stories like this are available on bloomberg.com
Subscribe now to stay ahead with the most trusted business news source.
©2021 Bloomberg L.P.
Edmonton, Alberta–(Newsfile Corp. – August 10, 2021) – Grizzly Discoveries Inc. (TSXV: GZD) (OTCQB: GZDIF) (FSE: G6H) ("Grizzly" or the "Company") is pleased to announce that it has entered into an option agreement (the "Option Agreement") with Hi-View Resources Inc. ("Hi-View") for its 80%-owend Ket-28 exploration project in Southeastern BC, Canada.
Under the terms of the Option Agreement, Hi-View will earn a 60% working interest in the property upon completion of the following:
-
Cash payments totaling $500,000 consisting of: (i) $5,000 upon signing of the Option Agreement; (ii) $15,000 upon Hi-View's listing on the CSE; (iii) $50,000 on the first anniversary in order to extend the option; and (iv) further payments totaling $430,000 paid on the first through fifth anniversary dates of Hi-View's listing on the CSE or other recognized stock exchange;
-
Payments totaling 800,000 shares of Hi-View consisting of: (i) 200,000 shares upon Hi-View's listing on the CSE; (ii) 120,000 shares each of the first through fifth anniversary dates of Hi-View's listing upon the CSE or other recognized stock exchange; and
-
Expenditures on the Ket-28 property totaling $1,100,000 consisting of: (i) $100,000 prior to December 31, 2022; (ii) $50,000 prior to the first anniversary date of Hi-View's listing; (iii) $200,000 prior to the second anniversary date of Hi-View's listing; and (iv) $110,000 of spend prior to each of the third through fifth anniversary dates of Hi-View's listing.
About the Ket-28 Property
The Ket-28 claims group is comprised of 16 claims covering 3,432 ha and are part of the Company's larger Greenwood Property located around the town of Greenwood in southeastern BC along the US border.
Historic Drilling at the Ket 28 prospect, located within the Rock Creek claim group of the Greenwood Project, has intersected high grade gold with 52.19 grams per tonne (g/t) Au over 3.35 m core length. Drilling by Grizzly in 2009 and 2010 at the Ket 28 prospect followed up the historic drilling in the mid 1990`s with up to 2.77 g/t Au over 11 m core length and 8.75 g/t Au over 3 m with a higher grade zone of 11.90 g/t Au over 2 m core length.
In 2020, Grizzly completed fifteen drill holes intersecting broad near-surface gold mineralization with key intervals including 1.59 g/t Au over 17.8 m from 43 m, including 7.37 g/t Au over 3.08 m (hole 20KT02), and 0.77 g/t Au over 31 m from 54.5 m, including 1.42 g/t Au over 11.5 m from 61 m (hole 20KT04). More detailed results of the Company's 2020 drill exploration program at Ket 28 were announced by the Company on December 2 and December 21, 2020.
Figure 1: The Grizzly Greenwood Claims and Ket-28 Property (shown in Pink).
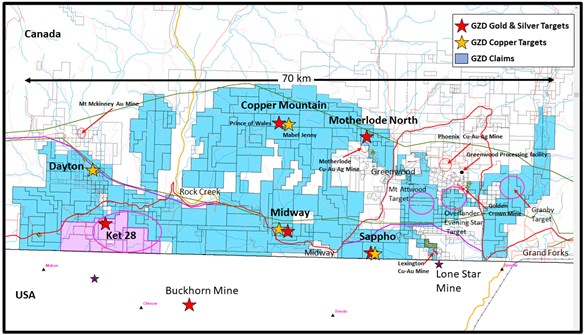
To view an enhanced version of Figure 1, please visit:
https://orders.newsfilecorp.com/files/4488/92646_a1948334f4cfeb8d_002full.jpg
Brian Testo, CEO of Grizzly commented, "We are very pleased to be partnering with Hi-View on the Ket-28 property. The planned expenditures and associated exploration work by Hi-View will contribute to a significant advancement in our understanding of the mineralogy at Ket-28. We look forward to work commencing later this year."
The technical content of this news release and the Company's technical disclosure has been reviewed and approved by Michael B. Dufresne, M. Sc., P. Geol., P.Geo., who is the Qualified Person as defined by National Instrument 43-101 Standards of Disclosure for Mineral Projects.
ABOUT GRIZZLY DISCOVERIES INC.
Grizzly is a diversified Canadian mineral exploration company with its primary listing on the TSX Venture Exchange, with 90 million shares issued, focused on developing its over 156,000 acres of precious and base metals properties in southeastern British Columbia. Grizzly is run by a highly experienced junior resource sector management team, who have a track record of advancing exploration projects from early exploration stage through to feasibility stage.
On behalf of the Board,
GRIZZLY DISCOVERIES INC.
Brian Testo, CEO, President
Tel: 780 693 2242
For further information, please visit our website at www.grizzlydiscoveries.com or contact:
Chris Beltgens
Corporate Development
Tel: 604 347 9535
Email: cbeltgens@grizzlydiscoveries.com
Neither the TSX Venture Exchange nor its Regulation Services Provider (as that term is defined in the policies of the TSX Venture Exchange) accepts responsibility for the adequacy or accuracy of this release.
Caution concerning forward-looking information
This press release contains "forward-looking information" and "forward-looking statements" within the meaning of applicable securities laws. This information and statements address future activities, events, plans, developments and projections. All statements, other than statements of historical fact, constitute forward-looking statements or forward-looking information. Such forward-looking information and statements are frequently identified by words such as "may," "will," "should," "anticipate," "plan," "expect," "believe," "estimate," "intend" and similar terminology, and reflect assumptions, estimates, opinions and analysis made by management of Grizzly in light of its experience, current conditions, expectations of future developments and other factors which it believes to be reasonable and relevant. Forward-looking information and statements involve known and unknown risks and uncertainties that may cause Grizzly's actual results, performance and achievements to differ materially from those expressed or implied by the forward-looking information and statements and accordingly, undue reliance should not be placed thereon.
Risks and uncertainties that may cause actual results to vary include but are not limited to the availability of financing; fluctuations in commodity prices; changes to and compliance with applicable laws and regulations, including environmental laws and obtaining requisite permits; political, economic and other risks; as well as other risks and uncertainties which are more fully described in our annual and quarterly Management's Discussion and Analysis and in other filings made by us with Canadian securities regulatory authorities and available at www.sedar.com. Grizzly disclaims any obligation to update or revise any forward-looking information or statements except as may be required by law.
To view the source version of this press release, please visit https://www.newsfilecorp.com/release/92646
President Biden's $1 trillion infrastructure bill did a lot to counter fears of Covid sweeping through China, with oil prices beginning to bounce back.


Chart of the Week

– July fuel demand in India rebounded to its highest since April as New Delhi cleared restrictions and lockdowns, netting a 3% month-on-month increase to a total of 16.83 million tons.
– The rebound might have been even more pronounced, were it not for fuel prices rising to all-time highs, triggered by a chaotic taxation regime.
– In India, petroleum products are not included in the goods and services tax regime, meaning every state can set its own fuel tax levies and they have been on the rise throughout 2021, up 20% year-on-year already.
– Analysts anticipate India surpassing its pre-pandemic consumption readings in Q4-2021, with fuel pricing remaining the primary factor in the extent of demand recovery.
– Crude imports in June-July dropped to average 2014-2015 levels of 3.5 mbpd, but August loadings have surged to a healthy 4.2 mbpd on the back of demand recovery.
Market Movers
– Saudi Aramco (TADAWUL:2222) saw its Q2 results surge as higher oil prices brought its net profit to $25.5 billion, quadrupling year-on-year. Aramco’s capex infrastructure has been increasing q-o-q as the Saudi NOC seeks to ramp up offshore spare production capacity.
– Australian miner BHP (NYSE:BHP) managed to stave off a union strike at the Escondida copper mine in Chile, the world’s largest, though negotiations are still yet to yield results. With copper prices almost 25% up on the year, the strike would see copper skyrocket.
– US electric vehicle producer Tesla (NASDAQ:TSLA) saw its July sales in China plunge by almost 70% month-on-month, despite having dropped the starting price for Model 3 sedans, sapping confidence in future prospects.
Tuesday, August 10, 2021
Oil prices rebounded from last week’s losses as the market seemed to shrug off fears of Chinese lockdowns, with demand strength across the Atlantic overshadowing COVID-related concerns. It is assumed President Biden’s $1 trillion infrastructure bill will boost oil product demand and lift US economic performance in the short-to-mid term, providing much-needed support for prices.
IPCC Report Targets Methane. The landmark report by the UN Intergovernmental Panel on Climate Change calls on the global community to make “strong, rapid and sustained reductions” in methane emissions alongside CO2-related initiatives. Having 80 times the warming power of CO2 per unit of mass, methane nevertheless has a much shorter atmospheric lifetime of some 20 years.
Iran Cuts Electricity Supply to Iraq. Facing unprecedentedly high domestic power demand, Iran has cut electricity exports to Iraq, despite there being a US waiver allowing it. Iran routinely exports some 2GW to its neighbors, but this August its exports dropped more than tenfold, to 150MW.
US Refiner Seeks EV Battery Move. The US’ fourth-largest refiner, Philips 66 (NYSE:PSX), is mulling a larger move towards electric vehicle batteries and EV storage systems as it seeks to leverage its graphite know-how and existing non-fossil retailing solutions.
Cargill Reports Largest-Ever Profit. The largest privately-held US company, the agriculture giant Cargill, recorded the highest-ever net income in its 156-year history with its 2021 fiscal year results, amounting to $4.93 billion. Following a brief one-year pause in COVID-stricken 2020, Cargill resumed making its results public.
China cutting runs as Delta variant hits refining. China’s state-owned oil refiner Sinopec (NYSE:SHI) is cutting run rates by 5-10% across China as strict government-mandated mobility curtailments and restrictive measures slacken its demand nationwide.
Petrobras Wants to Emulate Guyana. The Brazilian state oil company Petrobras (NYSE:PBR) plans to drill two wildcats in the Foz do Amazonas offshore basin, seeking to replicate the drilling success of Guyana and Suriname. Petrobras controls all six blocks in the basin after BP and Total bailed out of the project.
Related: Do Lithium Batteries Pose A Major Fire Hazard?
Rio Tinto Mismanages Supergiant Mongolian Mine. The WSJ reports that an expert group found that the main reason why Rio Tinto’s (NYSE:RIO) largest copper project, the Oyu Tolgoi mine in Mongolia, has seen its initial $5.3 billion budget expand by another $1.5 billion, lies in the mismanagement of the asset. Rio Tinto shares dropped 3% over the week.
ExxonMobil Suspended from US Climate Group. US oil major ExxonMobil (NYSE:XOM) was unseated from the Climate Leadership Council, a group promoting a US federal carbon price, following a leaked recording of a company lobbyist stating the firm is watering down climate measures with the White House.
Billionaire-Backed Startup to Search Greenland for EV Metals. KoBold Metals, a mineral exploration company backed by Bill Gates and Jeff Bezos, signed an agreement with Bluejay Mining (LON:JAY) to join the search for nickel, copper, cobalt and other metals in Greenland’s Disko-Nuussuaq acreage, Reuters reports.
Canada Eyes Asia Pacific Exports. Canada’s Trans Mountain pipeline expansion, with a throughput capacity of 590kbpd, shall be ready by December 2022, allowing Canadian oil producers to export crude to East Asian markets. CNR (TSE:CNR), Suncor (NYSE:SU), Imperial Oil (TSE:IMO), and others have already claimed their stake in the pipeline’s offtake.
Mozambique Retakes Key LNG Port with Rwandan Help. The strategically located Mocimboa da Praia port town was retaken by joint Mozambique-Rwandan forces, presumably taking the first step in restarting the halted 13 mtpa Mozambique LNG project operated by TotalEnergies (NYSE:TTE).
Russia Raises Metals Taxation. Russian President Vladimir Putin announced that his government would increase the mineral extraction tax on metals in 2022, the third time since the start of this year that the Kremlin hikes taxes on metals as it seeks to fill its deficit budget.
Japan Ends 300 Years of Trading Rice Futures. The first commodity exchange in the world, the Japanese Dojima Exchange trading rice futures, will end trading in June 2022 as Japan’s agriculture ministry refused to reissue its license, arguing the traded volumes were too small to maintain trades.
By Tom Kool for Oilprice.com
More Top Reads From Oilprice.com:
Read this article on OilPrice.com
London stocks kept a foothold in the green Monday, helped by a positive start for August across global equities and gains for the heavily weighted mining sector, following a bullish ratings upgrade by JPMorgan. The bank’s global equity strategy team lifted miners to overweight from neutral, commenting that after a stretch of weakness — 16% off first-quarter highs — “the valuation gap emerging relative to spot prices/earnings provides an opportunity for outperformance.” From the bank’s European mining, metals and steel team, lead analyst Luke Nelson, said earnings to date have confirmed “diversified miners’ capital returns credentials.”
(Reuters) -Turquoise Hill Resources said an independent review of$1.4 billion in cost overruns at the Oyu Tolgoi mine in Mongolia suggested that the project's troubles were not caused by the geology issues that mine operator Rio Tinto blamed https://www.reuters.com/article/us-rio-tinto-output-idUKKCN1UA2HH in 2019.
The review "raises certain questions in relation to the project management process" around the cost blowout and delay, Turquoise Hill said.
"Rio Tinto will engage with the OT (Oyu Tolgoi) Board as soon as we have had the opportunity to review the report in detail," Australia's Rio Tinto said in an emailed statement.
Rio owns 51% of Turquoise Hill, which owns 66% of the Oyu Tolgoi mine. The rest of the mine is owned by the government of Mongolia.
Costs to expand the Oyu Tolgoi mine, Rio's biggest copper growth project, have ballooned up to $6.75 billion from its original budget of $5.3 billion in 2016, raising friction over funding with Turquoise Hill.
The Wall Street Journal was first to report the news https://www.wsj.com/articles/rio-tinto-mismanagement-caused-mongolia-copper-mines-woes-report-says-11628503201.
(Reporting by Priyanshi Mandhan in Bengaluru; Editing by Devika Syamnath and Subhranshu Sahu)
Here are five stocks added to the Zacks Rank #1 (Strong Buy) List today:
Capri Holdings Limited CPRI: This designer, distributor and retailer of branded women's and men's apparel, footwear, and accessories has seen the Zacks Consensus Estimate for its current year earnings increasing 17.7% over the last 60 days.
Capri Holdings Limited Price and Consensus

Capri Holdings Limited price-consensus-chart | Capri Holdings Limited Quote
Daseke, Inc. DSKE: This provider of fleet management, logistics, trucking and open deck transportation services has seen the Zacks Consensus Estimate for its current year earnings increasing more than 100% over the last 60 days.
Daseke, Inc. Price and Consensus

Daseke, Inc. price-consensus-chart | Daseke, Inc. Quote
GMS Inc. GMS: This distributor of wallboard and suspended ceilings systems has seen the Zacks Consensus Estimate for its current year earnings increasing 19.6% over the last 60 days.
GMS Inc. Price and Consensus

GMS Inc. price-consensus-chart | GMS Inc. Quote
Jones Lang LaSalle Incorporated JLL: This provider of real estate and investment management services has seen the Zacks Consensus Estimate for its current year earnings increasing 28.1% over the last 60 days.
Jones Lang LaSalle Incorporated Price and Consensus

Jones Lang LaSalle Incorporated price-consensus-chart | Jones Lang LaSalle Incorporated Quote
The Mosaic Company MOS: This producer and marketer of concentrated phosphate and potash crop nutrients in North America and globally has seen the Zacks Consensus Estimate for its current year earnings increasing 38.9% over the last 60 days.
The Mosaic Company Price and Consensus

The Mosaic Company price-consensus-chart | The Mosaic Company Quote
You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Jones Lang LaSalle Incorporated (JLL) : Free Stock Analysis Report
The Mosaic Company (MOS) : Free Stock Analysis Report
GMS Inc. (GMS) : Free Stock Analysis Report
Daseke, Inc. (DSKE) : Free Stock Analysis Report
Capri Holdings Limited (CPRI) : Free Stock Analysis Report
To read this article on Zacks.com click here.
Here are four stocks with buy rank and strong value characteristics for investors to consider today, August 9th:
360 DigiTech, Inc. QFIN: This digital consumer finance platform has a Zacks Rank #1 (Strong Buy), and seen the Zacks Consensus Estimate for its current year earnings rising 8.1% over the last 60 days.
360 DigiTech, Inc. Price and Consensus

360 DigiTech, Inc. price-consensus-chart | 360 DigiTech, Inc. Quote
360 DigiTech has a price-to-earnings ratio (P/E) of 4.38, compared with 65.20 for the industry. The company possesses a Value Score of A.
360 DigiTech, Inc. PE Ratio (TTM)

360 DigiTech, Inc. pe-ratio-ttm | 360 DigiTech, Inc. Quote
The Mosaic Company MOS: This producer and marketer of concentrated phosphate and potash crop nutrients has a Zacks Rank #1, and seen the Zacks Consensus Estimate for its current year earnings rising 38.9% over the last 60 days.
The Mosaic Company Price and Consensus

The Mosaic Company price-consensus-chart | The Mosaic Company Quote
Mosaic Co. has a price-to-earnings ratio (P/E) of 7.23, compared with 15.80 for the industry. The company possesses a Value Score of A.
The Mosaic Company PE Ratio (TTM)

The Mosaic Company pe-ratio-ttm | The Mosaic Company Quote
Cornerstone Building Brands, Inc. CNR: This designer, engineer, manufacturer, marketer, and installer of external building products has a Zacks Rank #1, and seen the Zacks Consensus Estimate for its current year earnings rising 88.6% over the last 60 days.
Cornerstone Building Brands, Inc. Price and Consensus

Cornerstone Building Brands, Inc. price-consensus-chart | Cornerstone Building Brands, Inc. Quote
Cornerstone Building Brands has a price-to-earnings ratio (P/E) of 6.95, compared with 16.80 for the industry. The company possesses a Value Score of B.
Cornerstone Building Brands, Inc. PE Ratio (TTM)

Cornerstone Building Brands, Inc. pe-ratio-ttm | Cornerstone Building Brands, Inc. Quote
Hanmi Financial Corporation HAFC: This provider of business banking products and services has a Zacks Rank #1, and seen the Zacks Consensus Estimate for its current year earnings rising 21.8% over the last 60 days.
Hanmi Financial Corporation Price and Consensus

Hanmi Financial Corporation price-consensus-chart | Hanmi Financial Corporation Quote
Hanmi Financial has a price-to-earnings ratio (P/E) of 7.98, compared with 12.90 for the industry. The company possesses a Value Score of B.
Hanmi Financial Corporation PE Ratio (TTM)

Hanmi Financial Corporation pe-ratio-ttm | Hanmi Financial Corporation Quote
See the full list of top ranked stocks here.
Learn more about the Value score and how it is calculated here.
Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
The Mosaic Company (MOS) : Free Stock Analysis Report
Hanmi Financial Corporation (HAFC) : Free Stock Analysis Report
360 DigiTech, Inc. Sponsored ADR (QFIN) : Free Stock Analysis Report
Cornerstone Building Brands, Inc. (CNR) : Free Stock Analysis Report
To read this article on Zacks.com click here.
(Reuters) – An expert group reviewing the cause of a $1.4 billion cost overrun at a Mongolian mine run by Rio Tinto said it was caused by the miner's mismanagement, the Wall Street Journal reported on Monday, citing a report.
Costs to expand the Oyu Tolgoi mine, Rio's biggest copper growth project, have ballooned up to $6.75 billion from Rio's original budget of $5.3 billion in 2016, and this has led to a friction over funding with Turquoise Hill.
Turquoise Hill, in which Rio has a 50.8% stake, owns 66% of Oyu Tolgoi, one of the world's largest-known copper and gold deposits. The rest is held by the Mongolian government.
The report, which was commissioned by the owners of the copper project, said the cost overrun was not due to unfavorable rock conditions as blamed by the one of world's largest miner, the WSJ reported.
"This confidential report will be considered by the OT (Oyu Tolgoi) Board and Rio Tinto will engage with the OT Board as soon as we have had the opportunity to review the report in detail," Rio Tinto said in an emailed statement.
There was no evidence that the quality of the rock and general ground conditions were significantly different to that forecast by the miner's owners in 2016, according to the report.
The WSJ report said the U.S. Securities and Exchange Commission and British regulators were looking into the matter.
Turquoise Hill Resources did not immediately respond to a Reuters request for comment.
(Reporting by Priyanshi Mandhan in Bengaluru; Editing by Subhranshu Sahu)
In this article, we discuss the 10 best lithium and phosphate stocks to buy now. If you want to skip our detailed analysis of these stocks, go directly to the 5 Best Lithium and Phosphate Stocks to Buy Now.
The global efforts towards decarbonization have accelerated in the past few years with the United States and China, two of the largest manufacturing countries in the world, incentivizing the production and sale of electric vehicles and clean energy equipment. Nearly all commercial battery-based energy solutions make use of lithium compounds. According to the US Geological Survey, more than 70% of the total lithium production in the world is geared towards batteries. Since the supply of the precious metal is finite, the prices of the resource have skyrocketed.
Some of the biggest names in the lithium business presently include Tesla, Inc. (NASDAQ: TSLA), Johnson Controls International plc (NYSE: JCI), and NIO Inc. (NYSE: NIO), among others. Tesla, Inc. (NASDAQ: TSLA) chief Elon Musk, one of the richest men in the world, said last month that the company, the largest electric vehicle manufacturer in the world, would be making a long-term shift to lithium-iron-phosphate cells for use in EVs and energy storage, affirming his bullish view on the lithium industry.
The move also addresses questions about the use of nickel in EV batteries that have led to fire-safety concerns. A shift to iron, as signaled by Musk, could hit Chinese battery firms since nickel-based batteries are mostly manufactured in China. The use of lithium in EV batteries, though, remains an area that both the US and China seem to agree on, at least for now. According to a report by credit rating agency Fitch, worldwide lithium production is expected to triple from 442,000 tonnes in 2020 to 1.5 million tonnes by 2030.
The dramatic shift towards electric vehicles in recent years has disrupted other sectors of the economy as well, including the finance world. The entire hedge fund industry is feeling the reverberations of the changing financial landscape. Its reputation has been tarnished in the last decade, during which its hedged returns couldn’t keep up with the unhedged returns of the market indices. On the other hand, Insider Monkey’s research was able to identify in advance a select group of hedge fund holdings that outperformed the S&P 500 ETFs by more than 124 percentage points since March 2017. Between March 2017 and July 2021 our monthly newsletter’s stock picks returned 186.1%, vs. 100.1% for the SPY. Our stock picks outperformed the market by more than 115 percentage points (see the details here). That’s why we believe hedge fund sentiment is an extremely useful indicator that investors should pay attention to. You can subscribe to our free newsletter on our homepage to receive our stories in your inbox.

Photo by Kumpan Electric on UnsplashOur Methodology
With this context in mind, here is our list of the 10 best lithium and phosphate stocks to buy now. These were ranked keeping in mind analyst ratings, basic business fundamentals, and hedge fund sentiment.
Best Lithium and Phosphate Stocks to Buy Now
10. Lithium Americas Corp. (NYSE: LAC)
Number of Hedge Fund Holders: N/A
Lithium Americas Corp. (NYSE: LAC) is a Canadian resources company that primarily explores for lithium deposits. It is placed tenth on our list of 10 best lithium and phosphate stocks to buy now. In earnings results for the second quarter, posted on August 5, the firm reported earnings per share of -0.16, missing market estimates by $0.08. The cash and cash equivalents at the end of the first quarter were $505 million. On May 28, the share price of the firm jumped over 2% after it announced an expansion at a resource project in Argentina.
In March, investment advisory B Riley initiated coverage of Lithium Americas Corp. (NYSE: LAC) stock with a Buy rating and a price target of $25, noting that the firm was nearing completion of a lithium project and developing another long-term resource in the US.
Out of the hedge funds being tracked by Insider Monkey, New York-based investment firm Axel Capital Management is a leading shareholder in Lithium Americas Corp. (NYSE: LAC) with 830,000 shares worth more than $13 million.
Just like Tesla, Inc. (NASDAQ: TSLA), Johnson Controls International plc (NYSE: JCI), and NIO Inc. (NYSE: NIO), Lithium Americas Corp. (NYSE: LAC) is one of the best lithium and phosphate stocks to buy now.
In its Q1 2021 investor letter, Massif Capital, an asset management firm, highlighted a few stocks and Lithium Americas Corp. (NYSE: LAC) was one of them. Here is what the fund said:
“Lithium Americas: The volatility noted above in LAC has resulted in solid returns via our options trades around our core equity position. At the current time, we are short calls on LAC, as we have done multiple times throughout the position’s life, expiring on May 21, 2021, at a $17.5 and $22.5 strike price. The volume of contracts sold at each strike corresponds to the size of the equity position we want should the calls expire in the money, and the underlying equity gets called away from us. The thought process behind this trade construction is that if we know the size of the position we want at a particular price point, there is no reason not to accumulate additional returns by pre-selling the stock we would have sold anyway.
High levels of volatility positively impact the price of options, increasing the premium we can earn from selling covered calls. To date, we have sold covered calls on LAC that have expired worthless four times, yielding a roughly 7% return on the equity position’s current value or 71bps for the portfolio overall. The outstanding covered calls appear to be trending towards a similar worthless expiration. If they do, the covered call trades on LAC will result in us owning the shares with committed capital of -$0.28 per share.
Although we believe in the fullness of time LAC warrants a $30+ valuation, the prices achieved in early January of this year were not justified by the underlying fundamentals. Some will argue we should have sold down our position. We had already established our option positions and believe LAC is an emerging major in the lithium mining industry. Thus, we decided to maintain the position unchanged. Although still relatively high, the current $15 per share valuation is not crazy compared to where we think the firm should be trading based on fundamentals, so we are no longer overly concerned with the position as is.
LAC management also took advantage of the volatility issuing stock on January 22 for $22 a share. The ~$400 million in proceeds will be used to develop Thacker Pass, the US-based clay lithium deposit, which will likely be the largest producing Lithium mine in America when turned on. In our opinion, the stock issuance could not have come at a better time. LAC management has advanced the project through various development stages (de-risking), but with the share issuance, they have significantly reduced the need to bring in an outside partner to develop the asset as the first phase of the project is expected to cost roughly $581 million. After-tax and at an 8% discount rate, the Thacker Pass project’s present value is approximately $2.6 billion (the firm’s current market capitalization is $1.5 billion). Although the share issuance was dilutive, increasing the total shares by 17%, we believe it will, in the long run, prove a forward-looking, value-additive decision by management.
The lithium market remains an area of interest and focus for us. This reflects our belief that the most exciting investment opportunities to capture secular trends in EV’s and batteries are found upstream in the mining industry. It is also a reflection that there is a greater diversity of lithium investment opportunities relative to other battery metals.”
9. Sociedad Química y Minera de Chile S.A. (NYSE: SQM)
Number of Hedge Fund Holders: 16
Sociedad Química y Minera de Chile S.A. (NYSE: SQM) is a Chilean firm that produces and distributes lithium derivatives. It is ranked ninth on our list of 10 best lithium and phosphate stocks to buy now. On July 16, the company announced that it had received approval from authorities in Australia to build a lithium hydroxide refinery. The project, once completed, would be capable of producing 50,000 metric tons of battery-grade lithium hydroxide. The production on the site is expected to commence by 2024.
On May 20, investment advisory Scotiabank upgraded Sociedad Química y Minera de Chile S.A. (NYSE: SQM) stock to Sector Perform from Underperform with a price target of $42. Ben Isaacson, an analyst at the firm, issued the ratings update.
Out of the hedge funds being tracked by Insider Monkey, Chicago-based investment firm Citadel Investment Group is a leading shareholder in Sociedad Química y Minera de Chile S.A. (NYSE: SQM) with 718,156 shares worth more than $38 million.
Alongside Tesla, Inc. (NASDAQ: TSLA), Johnson Controls International plc (NYSE: JCI), and NIO Inc. (NYSE: NIO), Sociedad Química y Minera de Chile S.A. (NYSE: SQM) is one of the best lithium and phosphate stocks to buy now.
In its Q1 2021 investor letter, ClearBridge Investments, an asset management firm, highlighted a few stocks and Sociedad Química y Minera de Chile S.A. (NYSE: SQM) was one of them. Here is what the fund said:
“Among materials names in our structural bucket, we sold SQM as the stock hit our price target. Lithium prices remain at levels well below previous highs and while we expect they may reach higher levels in the future; high pricing likely encourages additional supply onto the market.”
8. Livent Corporation (NYSE: LTHM)
Number of Hedge Fund Holders: 22
Livent Corporation (NYSE: LTHM) is placed eighth on our list of 10 best lithium and phosphate stocks to buy now. The company is based in Pennsylvania. It makes and sells lithium compounds. The company posted earnings for the second quarter on August 5, reporting earnings per share of $0.04, beating market predictions by $0.02. The revenue over the period was $102 million, up 57% compared to the revenue over the same period last year and beating market estimates by $14.4 million.
In April, investment advisory Evercore upgraded Livent Corporation (NYSE: LTHM) stock to Outperform from In Line and raised the price target to $22 from $20, noting the positive developments in the lithium industry as a whole in terms of basic fundamentals.
Out of the hedge funds being tracked by Insider Monkey, New York-based investment firm Joho Capital is a leading shareholder in Livent Corporation (NYSE: LTHM) with 3.7 million shares worth more than $65 million.
In addition to Tesla, Inc. (NASDAQ: TSLA), Johnson Controls International plc (NYSE: JCI), and NIO Inc. (NYSE: NIO), Livent Corporation (NYSE: LTHM) is one of the best lithium and phosphate stocks to buy now.
7. Energizer Holdings, Inc. (NYSE: ENR)
Number of Hedge Fund Holders: 22
Energizer Holdings, Inc. (NYSE: ENR) is ranked seventh on our list of 10 best lithium and phosphate stocks to buy now. The company markets different types of batteries and is headquartered in Missouri. On May 10, the firm posted earnings for the second fiscal quarter, reporting earnings per share of $0.77, beating market estimates by $0.17. The revenue over the period was $685 million, up 16% compared to the revenue over the same period last year and beating market predictions by $59 million.
On May 11, investment advisory Morgan Stanley reiterated an Overweight rating on Energizer Holdings, Inc. (NYSE: ENR) stock and raised the price target to $56 from $54, noting the large earnings beat for the firm in the second fiscal quarter.
At the end of the first quarter of 2021, 22 hedge funds in the database of Insider Monkey held stakes worth $237 million in Energizer Holdings, Inc. (NYSE: ENR).
Tesla, Inc. (NASDAQ: TSLA), Johnson Controls International plc (NYSE: JCI), and NIO Inc. (NYSE: NIO) are some of the best lithium and phosphate stocks to buy now, just like Energizer Holdings, Inc. (NYSE: ENR).
6. QuantumScape Corporation (NYSE: QS)
Number of Hedge Fund Holders: 29
QuantumScape Corporation (NYSE: QS) is a California-based company that develops and sells solid-state lithium batteries that are used in electric vehicles. It is placed sixth on our list of 10 best lithium and phosphate stocks to buy now. The stock has been one of the most high-volume ones on the market in recent weeks. On August 2, the share price soared close to 3.5%, stretching year-to-date gains to 70%, in a high-volume trading day for the company. The firm also stands to gain as EV deliveries improve in the post-pandemic economy.
On July 21, investment advisory JPMorgan initiated coverage of QuantumScape Corporation (NYSE: QS) stock with a Neutral rating and a price target of $35, underlining that the firm would play a vital role in the development of solid-state batteries for the EV industry in the near future.
At the end of the first quarter of 2021, 29 hedge funds in the database of Insider Monkey held stakes worth $534 million in QuantumScape Corporation (NYSE: QS).
Tesla, Inc. (NASDAQ: TSLA), Johnson Controls International plc (NYSE: JCI), and NIO Inc. (NYSE: NIO) are some of the best lithium and phosphate stocks to buy now, in addition to QuantumScape Corporation (NYSE: QS).
In its Q1 2021 investor letter, Baron Funds, an asset management firm, highlighted a few stocks and QuantumScape Corporation (NYSE: QS) was one of them. Here is what the fund said:
“QuantumScape Corporation is an early-stage developer of solid-state battery technology for electric vehicles aimed at improving key aspects of batteries, including safety, charging times, energy density, and cost. The company went public via a SPAC in November. After rapid appreciation, the stock came under pressure when the company raised additional capital to help accelerate its commercialization process. We exited our small position, as described below.
We sold QuantumScape Corporation, an early-stage solid-state electric vehicle battery innovator, because it was an undersized position with an ambitious valuation. We will continue to monitor QuantumScape’s developments and may revisit the company as an investment at a future point in time. “
Click to continue reading and see 5 Best Lithium and Phosphate Stocks to Buy Now.
Suggested Articles:
Disclosure. None. 10 Best Lithium and Phosphate Stocks to Buy Now is originally published on Insider Monkey.
Domtar Corporation’s UFS second-quarter 2021 adjusted earnings of $1.22 per share missed the Zacks Consensus Estimate of $1.26. Including one-time items, the company reported earnings per share of 75 cents against the prior-year quarter’s loss of 5 cents. Increased shipments of paper and higher net average selling prices for pulp and paper aided results in the quarter. The company noted an increase in demand for paper through the second quarter amid the ongoing economic recovery from the effects of the COVID-19 pandemic.
Consolidated sales increased 26% year over year to $1,010 million. The top line, however, lagged the Zacks Consensus Estimate of $1,041 million. Net average selling prices for pulp and paper were up from prior-year quarter. On a year-over-year basis, manufacturing paper volumes were up, while pulp volumes were slightly down.
Consolidated adjusted operating income amounted to $99 million during the quarter under review against the year-ago quarter’s operating loss of $3 million.
Domtar Corporation Price, Consensus and EPS Surprise

Domtar Corporation price-consensus-eps-surprise-chart | Domtar Corporation Quote
Segmental Performance
Following the sale of its Personal Care business on Mar 1, 2021, the company has only one operating segment — Pulp and Paper, which comprises design, manufacturing, marketing and distribution of communication, specialty and packaging papers, as well as softwood, hardwood and fluff pulp, and high quality airlaid ultrathin laminated cores.
Quarterly revenues of the Pulp and Paper segment totaled $1010 million, up 26% year over year. Revenues from Communication Papers were up 29% year over year to $498 million. While Specialty and Packaging paper’s revenues improved 14% to $145 million, the same from Market Pulp surged 28% to $357 million. Revenues from absorbent core materials were down 17% to $10 million.
Adjusted operating income for the segment was $109 million in the second quarter, substantially up from the year-earlier reported figure of $4 million.
Balance Sheet & Cash Flow
The company had cash and cash equivalents of $346 million at the end of second-quarter 2021, up from the $309 million held at end of 2020. Net debt-to-total capitalization ratio was 7% as of Jun 30, 2021, down from 26% as of Dec 31, 2020.
Domtar generated $90 million of cash from operating activities during the first six-month period of 2021 compared with the $155 million reported in the year-earlier comparable period.
Update on Merger With Paper Excellence
On May 10, 2021, Domtar and Paper Excellence together announced that they have entered into a business combination agreement under which the latter will acquire all of the issued and outstanding shares of Domtar common stock for $55.50 per share, in cash. The all-cash transaction represents an enterprise value of approximately $3 billion. Subsequently, on Jul 29, Domtar announced that the deal has been approved by Domtar’s shareholders.
The company added that clearances have been obtained under the antitrust laws of Spain and the People’s Republic of China, following previous clearances obtained in the United States and Turkey — representing another step toward the closing of the announced merger. The merger is expected to be completed before the end of this year, subject to receiving clearance under Canada’s Competition Act and other customary closing conditions.
Outlook
While the uncertainty regarding the pandemic remains, Domtar believes paper demand will continue to pick up pace as people return to schools and offices. It expects to sell all paper production for the balance of the year. The pulp market is likely to gradually improve on steady demand growth and supply constraint. Paper prices are expected to continue to increase, while pulp prices are expected to witness some seasonal volatility. While raw material costs are expected to remain stable, freight costs are likely to be higher this year.
Price Performance

Image Source: Zacks Investment Research
The stock has soared 95% in the past year, compared with the industry’s rally of 52.6%.
Zacks Rank & Other Key Picks
Domtar currently sports a Zacks Rank #1 (Strong Buy). You can see the complete list of today’s Zacks #1 Rank stocks here.
Some other top-ranked stocks in the basic materials space include Commercial Metals Company CMC, Nucor Corporation NUE and The Mosaic Company MOS. All of these stocks flaunt a Zacks Rank #1 currently. .
Commercial Metals has a projected earnings growth rate of 32.8% for the current fiscal year. The company’s shares have gained nearly 41% in the past year.
Nucor has an expected earnings growth rate of 455% for the current fiscal year. The company’s shares have rallied around 126% over the past year.
Mosaic Company has a projected earnings growth rate of 412% for the current fiscal year. The company’s shares have gained roughly 71% in a year’s time.
Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Domtar Corporation (UFS) : Free Stock Analysis Report
Nucor Corporation (NUE) : Free Stock Analysis Report
The Mosaic Company (MOS) : Free Stock Analysis Report
Commercial Metals Company (CMC) : Free Stock Analysis Report
If you would like to receive our free newsletter via email, simply enter your email address below & click subscribe.
 Follow us on Twitter
 Become our facebook fan
CONNECT WITH US
Tweets
Tweet with hash tag #miningfeeds or @miningfeeds and your tweets will be displayed across this site.
MOST ACTIVE MINING STOCKS
Daily Gainers
 Wallbridge Mining Co. Ltd. |
WM.TO | +1,900.00% |
| Galore Resources Inc. |
GRI.V | +100.00% |
| Midlands Minerals Corp. |
MEX.V | +66.88% |
 Redstone Resources Ltd |
RDS.AX | +50.00% |
| GoviEx Uranium Inc. |
GXU.V | +42.86% |
| Mount Burgess Mining NL |
MTB.AX | +33.33% |
| Casa Minerals Inc. |
CASA.V | +30.00% |
| Poseidon Nickel Limited |
POS.AX | +25.00% |
| Azincourt Energy Corp. |
AAZ.V | +20.00% |
| Impact Minerals Limited |
IPT.AX | +18.18% |