A strong stock as of late has been Teck Resources Ltd (TECK). Shares have been marching higher, with the stock up 8.8% over the past month. The stock hit a new 52-week high of $72.56 in the previous session. Teck Resources has gained 50.3% since the start of the year compared to the 20.5% gain for the Zacks Basic Materials sector and the 31.1% return for the Zacks Mining – Miscellaneous industry.
What's Driving the Outperformance?
The stock has an impressive record of positive earnings surprises, having beaten the Zacks Consensus Estimate in each of the last four quarters. In its last earnings report on July 23, 2026, Teck Resources reported EPS of $1.39 versus consensus estimate of $0.78.
For the current fiscal year, Teck Resources is expected to post earnings of $3.6 per share on $10.44 in revenues. This represents a 62.9% change in EPS on a 35.38% change in revenues. For the next fiscal year, the company is expected to earn $3.03 per share on $10.22 in revenues. This represents a year-over-year change of -15.82% and -2.05%, respectively.
Valuation Metrics
While Teck Resources has moved to its 52-week high over the past few weeks, investors need to be asking, what is next for the company? A key aspect of this question is taking a look at valuation metrics in order to determine if the company is due for a pullback from this level.
On this front, we can look at the Zacks Style Scores, as they provide investors with an additional way to sort through stocks (beyond looking at the Zacks Rank of a security). The individual style scores for Value, Growth, Momentum and the combined VGM Score run from A through F. Investors should consider the style scores a valuable tool that can help you to pick the most appropriate Zacks Rank stocks based on their individual investment style.
Teck Resources has a Value Score of C. The stock's Growth and Momentum Scores are B and F, respectively, giving the company a VGM Score of B.
In terms of its value breakdown, the stock currently trades at 20X current fiscal year EPS estimates, which is not in-line with the peer industry average of 20.3X. On a trailing cash flow basis, the stock currently trades at 14.7X versus its peer group's average of 17.9X. Additionally, the stock has a PEG ratio of 2.5. This isn't enough to put the company in the top echelon of all stocks we cover from a value perspective.
Zacks Rank
We also need to consider the stock's Zacks Rank, as this supersedes any trend on the style score front. Fortunately, Teck Resources currently has a Zacks Rank of #2 (Buy) thanks to favorable earnings estimate revisions from covering analysts.
Since we recommend that investors select stocks carrying Zacks Rank of 1 (Strong Buy) or 2 (Buy) and Style Scores of A or B, it looks as if Teck Resources meets the list of requirements. Thus, it seems as though Teck Resources shares could still be poised for more gains ahead.
How Does TECK Stack Up to the Competition?
Shares of TECK have been soaring, and the company still appears to be a decent choice, but what about the rest of the industry? One industry peer that looks good is Norsk Hydro ASA (NHYDY). NHYDY has a Zacks Rank of #2 (Buy) and a Value Score of A, a Growth Score of A, and a Momentum Score of C.
Earnings were strong last quarter. Norsk Hydro ASA beat our consensus estimate by 4.55%, and for the current fiscal year, NHYDY is expected to post earnings of $0.92 per share on revenue of $22.86 billion.
Shares of Norsk Hydro ASA have gained 4.5% over the past month, and currently trade at a forward P/E of 11.13X and a P/CF of 9.23X.
The Mining – Miscellaneous industry may rank in the bottom 74% of all the industries we have in our universe, but there still looks like there are some nice tailwinds for TECK and NHYDY, even beyond their own solid fundamental situation.
Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Teck Resources Ltd (TECK) : Free Stock Analysis Report
Norsk Hydro ASA (NHYDY) : Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).
Graphene Manufacturing Group's fast-charging battery cells show no performance loss Proactive uses images sourced from Shutterstock
Graphene Manufacturing Group Ltd (TSX-V:GMG, OTCQX:GMGMF) said its fast-charging GCELLS have shown no reduction in performance after 489 charge cycles, each completed within six minutes, in the latest data from its battery development program with Rio Tinto.
The cycling data, collected by the Battery Innovation Center of Indiana on 1 Ah cells built with materials developed and supplied by GMG's Brisbane Battery Development Centre, compared the GCELLS against a well-known Lithium Titanate Oxide battery tested under the same charging profile. The LTO cell degraded to 86% of its original capacity, near the industry's typical 80% end-of-life threshold, within just 64 cycles.
GMG said its cells have effectively lasted more than seven times longer than the LTO comparison under identical testing conditions.
Craig Nicol, CEO of GMG, said the data is an important proof point for the program, showing GCELLS can be repeatedly fast-charged with no measurable degradation, well beyond where the LTO comparison reached end of life. “Energy density is an area we are continuing to optimise, and we are confident, based on the pathway BIC and our own team have identified, that we can lift this back towards 50 Wh/kg at a 10C charge rate as this program matures.”
Bob Galyen, GMG director and former chief technology officer of CATL, called the cycling stability "genuinely exceptional," noting the low internal resistance of around 5 mOhms and a 4 degree temperature rise above ambient show the material science is translating into real cell-level performance.
Jack Perkowski, chairman of GMG, said that BIC's independently measured data gives the board confidence in the program's direction as management works through the optimisation steps ahead.
The work is being carried out under a Joint Development Agreement between GMG and Rio Tinto, one of the world's largest metals and mining groups, with support from the Battery Innovation Center of Indiana in the United States.
Shares were up 2.4% on Wednesday.
Brisbane, Queensland, Australia–(Newsfile Corp. – September 9, 2026) – Graphene Manufacturing Group Ltd. (TSXV: GMG) (OTCQX: GMGMF) ("GMG" or the "Company") is pleased to provide the latest progress update on the next generation graphene battery technology being developed by GMG under a Joint Development Agreement with Rio Tinto, one of the world's largest metals and mining groups, and with the support of the Battery Innovation Center of Indiana ("BIC") in the United States of America.
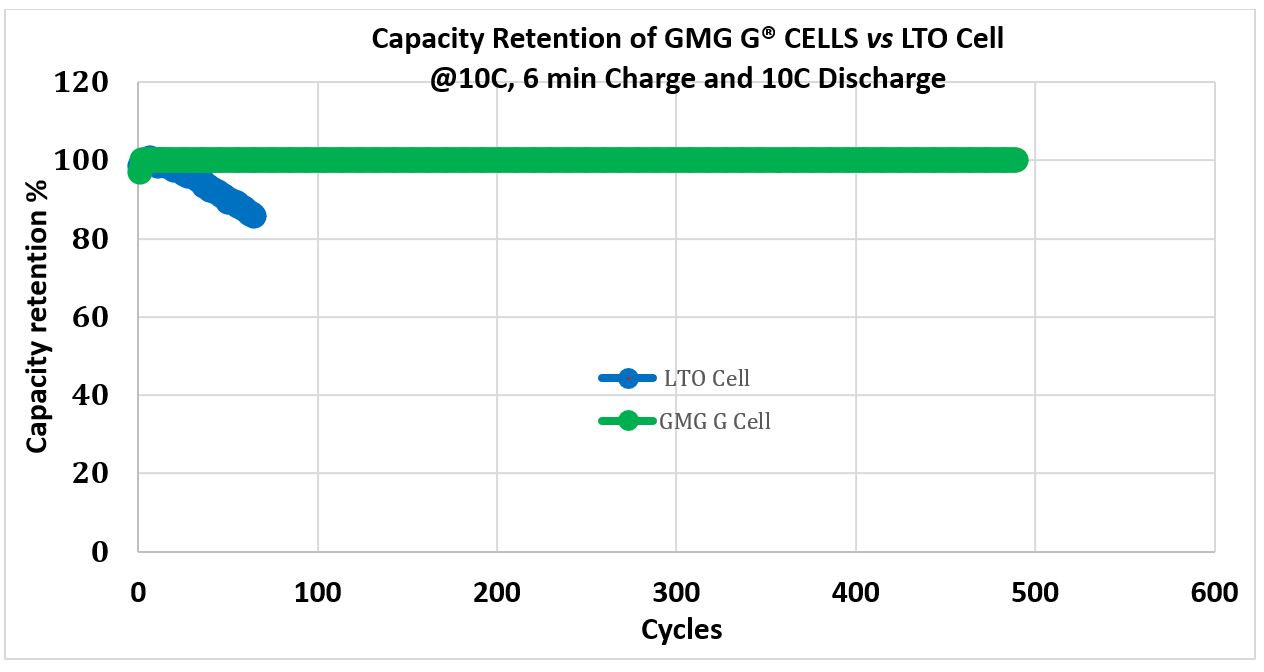
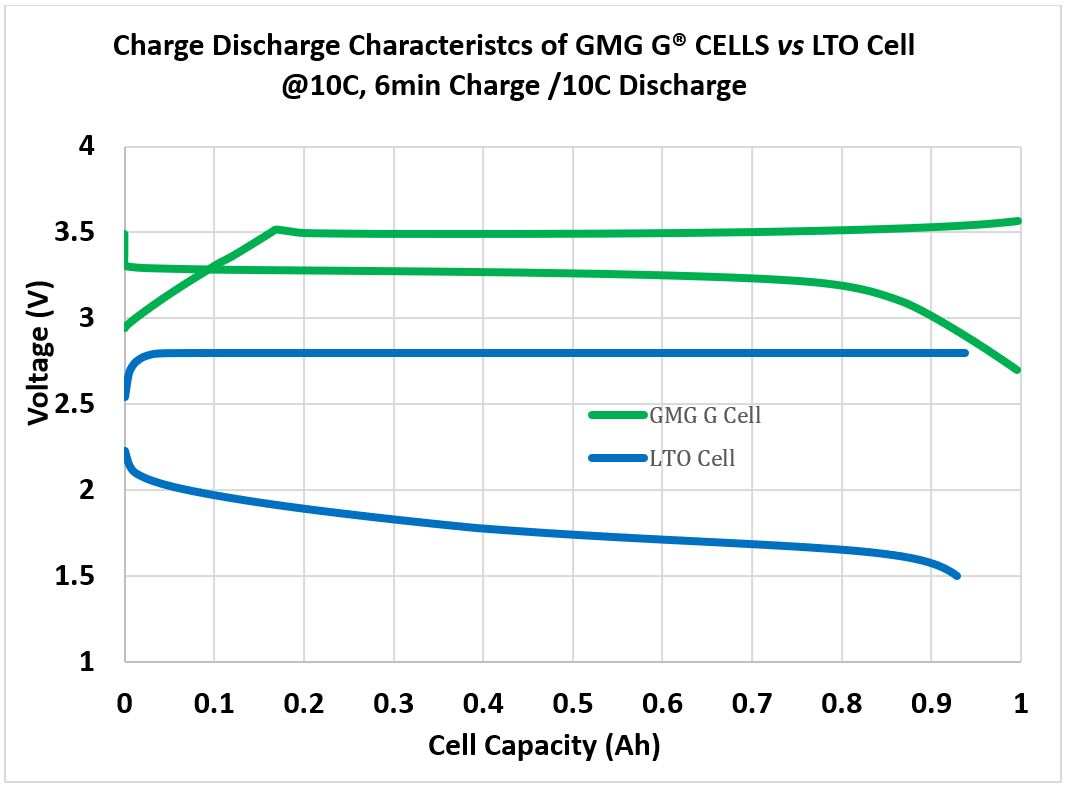
GMG is pleased to share the following cycling data of GMG's fast charging G®CELLS (1 Ah cells with 6 minute charging) as seen in Figure 1, with voltage and capacity graphs shown in Figure 2. This data was collected by the BIC on cells that were made by the BIC with materials that were developed, manufactured and supplied by GMG in its Brisbane Battery Development Centre.
Figure 1 shows that G®CELLS have cycled with no performance reduction after 489 cycles, as at September 4th 2026, despite being charged and discharged within 6 minutes for each cycle. Figure 1 also shows the performance of a well-known Lithium Titanate Oxide (LTO) battery which, when charged under the same cycling profile, degraded to 86% of original capacity (near the 80% state of charge which is typically the declared end of life of a cell) within 64 cycles. The G®CELLS have effectively lasted over seven times longer when cycling with the same testing.
Figure 1: GMG G® CELLS and LTO Cycling data with no degradation or performance reductionafter 489 cycles with 10C 6 minutes charge and 10C 6 minutes discharge
To view an enhanced version of this graphic, please visit:https://images.newsfilecorp.com/files/8082/313606_gmgfig1.jpg
Figure 2 shows very flat voltage and capacity curves with little change of voltage during ~80% of the discharge cycle, especially when compared to the LTO cells. The G®CELLS constant voltage during a large percentage of discharge time is a valuable battery parameter to support easier to control constant power discharge.
Figure 2: Charge Discharge Characteristics of GMG G® CELLS and LTO Cell
To view an enhanced version of this graphic, please visit:https://images.newsfilecorp.com/files/8082/313606_gmgfig2.jpg
The battery performance data for measured energy density, temperature and resistance for each of these cells achieved is seen in Figure 3. While the energy density is lower than previously reported, this is unoptimized and the Company believes it can bring this energy density back up to around 50 Wh/kg (10 C charge rate) after further optimisation is done after initial testing. The very low resistance of the G®CELLS of ~ 0.005 Ohms (5 mOhms) allowed for a very low temperature increase of 4o C above ambient despite charging at very high speeds – as compared to the LTO cells resistance of up to 0.030 Ohms (30 mOhms) which increased by 19oC above ambient during testing.
| Charging/Discharging & Type of Cells | Energy Density (Wh/kg) | Temperature (deg C) – Ambient: 25 deg C | Resistance(Ohm) |
| 10 C / 10 C – G® CELLS | 39 | 29 | 0.005 |
| 10 C / 10 C – LTO | 37 | 44 | up to 0.030 |
Figure 3: GMG G Cells and LTO measured performance data
Bob Galyen, GMG Director and former Chief Technology Officer of CATL, commented: "The cycling stability we are seeing from these G®CELLS is genuinely exceptional. Sustaining zero measurable capacity fade past 489 cycles under a full 10C charge and 10C discharge regime, each cycle completed in six minutes, is a result that stands in stark contrast to the LTO benchmark cell, which is regarded as one of the most robust fast-charging chemistries on the market today and still degraded to end-of-life within 64 cycles under the same profile. The very low internal resistance of around 5 mOhms, and the resulting 4 degree temperature rise above ambient, tells me GMG's material science is translating into real, measurable cell-level performance rather than just laboratory promise. Having built and scaled battery manufacturing for the world's largest lithium-ion producer, I know how rare it is to see this combination of fast-charge durability and thermal control this early in a cell's development. There is clear further work ahead on some of the energy density optimisation and further scaling of the cell size, but the fundamentals being demonstrated here are the right ones to be solving first."
Craig Nicol, Chief Executive Officer and Managing Director of GMG, commented: "This data set from BIC is an important proof point for our graphene battery program. Fast charging is one of the biggest barriers to broader electric vehicle and energy storage adoption, and these results show G®CELLS can be repeatedly charged and discharged in six minutes with no measurable degradation after 489 cycles, well beyond where the comparable LTO cell reached end of life. We are also encouraged by the very low resistance and minimal temperature rise, which speak directly to the safety and thermal management advantages we believe graphene can bring to battery design. Energy density is an area we are continuing to optimise, and we are confident, based on the pathway BIC and our own team have identified, that we can lift this back towards 50 Wh/kg at a 10C charge rate as this program matures. I want to thank the team at BIC and our partners Rio Tinto, for their continued collaboration as we progress this technology along the roadmap."
Jack Perkowski, Chairman of GMG, commented: "Battery development of this kind requires patient capital, disciplined engineering and world-class partners, and this update reflects progress on all three fronts. The fact that BIC, an organisation with a decade of experience and over 500 battery development projects behind it, is generating this kind of independently measured cycling data on cells built with GMG's graphene materials gives the Board real confidence in the direction of this program. Combined with the ongoing support of Rio, I believe GMG is building the right foundations to advance this technology toward commercial relevance, and the Board will continue to support management as they work through the optimisation steps ahead."
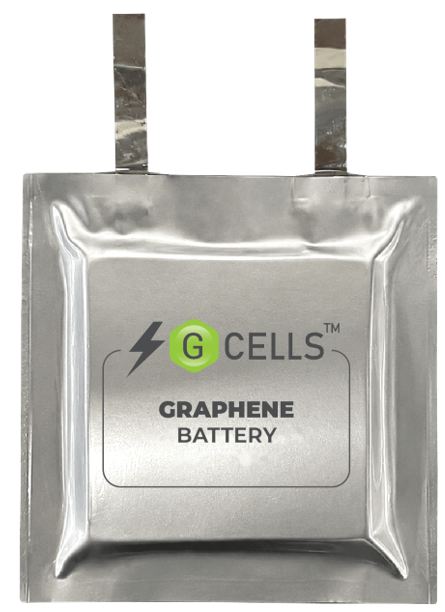
Please see the following webpage for further details about the graphene batteries: https://graphenemg.com/graphene-products/gcells/. The G®CELLS are in pouch format – as seen in Figure 4. The launch video link for G®CELLS is shown in Figure 5.
Figure 4: G Cell Pouch Cell Battery
To view an enhanced version of this graphic, please visit:https://images.newsfilecorp.com/files/8082/313606_gmgfig4.jpg
Figure 5: G®CELLS Launch Video
Launch video: https://youtu.be/pfHhh5-TLyU
To view an enhanced version of this graphic, please visit:https://images.newsfilecorp.com/files/8082/313606_76d5197784c8692d_004full.jpg
About BIC:
BIC is a collaborative initiative designed to incorporate leadership from renowned universities, government agencies, and commercial enterprises. BIC is a public-private partnership and a not-for-profit organization focusing on the rapid development, testing and commercialization of safe, reliable and lightweight energy storage systems for defense and commercial customers. BIC is a unique organization that has been leading battery cell development for world leading battery companies for over 10 years and has carried out over 500 battery development projects.
About GMG
GMG is an Australian based clean-technology company which develops, makes and sells energy saving and energy storage solutions, enabled by graphene manufactured via in house production process. GMG uses its own proprietary production process to decompose natural gas (i.e. methane) into its natural elements, carbon (as graphene), hydrogen and some residual hydrocarbon gases. This process produces high quality, low cost, scalable, 'tuneable' and low/no contaminant graphene suitable for use in clean-technology and other applications.
The Company's present focus is to de-risk and develop commercial scale-up capabilities, and secure market applications. In the energy savings segment, GMG has initially focused on graphene enhanced heating, ventilation and air conditioning ("HVAC-R") coating (or energy-saving coating) which is now being marketed into other applications including electronic heat sinks, industrial process plants and data centres. Another product GMG has developed is the graphene lubricant additive focused on saving liquid fuels initially for diesel engines.
In the energy storage segment, GMG is working collaboratively with financial support from the Australian Government to progress R&D and commercialization of GMG Graphene Batteries. GMG has also developed a graphene additive slurry that is aimed to improve the performance of lithium-ion batteries.
GMG's 4 critical business objectives are:
For further information please contact:
- Craig Nicol, Chief Executive Officer & Managing Director of the Company at craig.nicol@graphenemg.com, +61 415 445 223
- Leo Karabelas at Focus Communications Investor Relations, leo@fcir.ca, +1 647 689 6041
Neither the TSX Venture Exchange nor its Regulation Services Provider (as that term is defined in the policies of the TSX Venture Exchange) accept responsibility for the adequacy or accuracy of this news release.
Cautionary Note Regarding Forward-Looking Statements
This news release includes certain statements and information that may constitute forward-looking information within the meaning of applicable Canadian securities laws. Forward-looking statements relate to future events or future performance and reflect the expectations or beliefs of management of the Company regarding future events. Generally, forward-looking statements and information can be identified by the use of forward-looking terminology such as "intends", "expects" or "anticipates", or variations of such words and phrases or statements that certain actions, events or results "may", "could", "should", "would" or will "potentially" or "likely" occur. This information and these statements, referred to herein as "forward‐looking statements", are not historical facts, are made as of the date of this news release and include, without limitation, statements that GMG Graphene Batteries are safe and fast charging and that graphene can be used to increase their performance and cycle life, statements regarding the Company's ability to bring energy density back up to around 50 Wh/kg (10 C charge rate) after further optimisations, GMG's intentions to develop commercial scale-up capabilities, GMG's focus in the energy savings segment, GMG's intentions for the use of graphene lubricant additive on saving liquid fuels, expectations for R&D and commercialisation of Graphene Batteries, GMG's ability to improve the performance of lithium-ion batteries, statements attributed to Bob Galyen, Craig Nicol and Jack Perkowski regarding the significance of the BIC cycling data, the Company's technology, partnerships and commercial prospects, and the Company's four critical business objectives.
Such forward-looking statements are based on a number of assumptions of management, including, without limitation, assumptions that GMG Graphene Batteries can be produced at lower cost, as to charging time, energy density, life cycle, safety, thermal runaway risk and the need for a thermal management system for, the speed and stability of charging, that GMG Graphene Batteries will progress to BTRL 7 and 8, that a range of global companies in a variety of industries will be interested in working with GMG, that the battery pack design will be plastic and offer weight, cost and complexity advantages to a metal case and increased energy density, that the service agreement with the BIC will enable the Company to optimize its cell design and battery manufacturing equipment, that the Company will be able to bring energy density back up to around 50 Wh/kg (10 C charge rate) as anticipated, and that the Company will be able to meet its overall timeline on the battery cell roadmap. Additionally, forward-looking information involves a variety of known and unknown risks, uncertainties and other factors which may cause the actual plans, intentions, activities, results, performance or achievements of GMG to be materially different from any future plans, intentions, activities, results, performance or achievements expressed or implied by such forward-looking statements. Such risks include, without limitation: that GMG Graphene Batteries cannot be produced at lower cost, or any of the assumptions as to charging time, energy density, life cycle, scaling of the cell size, safety, thermal runaway risk and the need for a thermal management system for GMG Graphene Batteries cannot be achieved; that GMG Graphene Batteries do not offer expected speed and stability of charging; that GMG Graphene Batteries will not progress to BTRL 7 and 8; that a range of global companies in a variety of industries will not be interested in working with GMG; that the battery pack design will not be plastic and will not offer weight, cost and complexity advantages to a metal case and increased energy density; that the Company will not be able to optimize the electrochemical behaviour of the pouch cell through laboratory experimentation or at all; that the Company will not be able to bring energy density back up to around 50 Wh/kg (10 C charge rate) or at all; that the Company will not be able to meet its overall timeline on the battery cell roadmap; that the service agreement with the BIC will not enable the Company to optimize its cell design and battery manufacturing equipment; that further testing or larger-format cells will not replicate the cycling, resistance or temperature performance reported in this news release; that the Joint Development Agreement with Rio Tinto will not continue on the terms or timeline currently anticipated; GMG's operations could be adversely affected by possible future government legislation, policies and controls or by changes in applicable laws and regulations, or by the failure to obtain all necessary regulatory approvals; public health crises such as pandemics may adversely impact GMG's business and the ability of the Company to develop its products; the volatility of global capital markets; political instability; the failure of GMG to attract and retain skilled personnel; unexpected development and production challenges; GMG could face technology or software disruptions; unanticipated costs; risks relating to the extent and duration of the conflicts in Eastern Europe and the Middle East and their impact on global markets; that the Company will be unable to develop, market, and sell its products as currently anticipated; that the Company will be unsuccessful in identifying and engaging strategic partners; that the Company will be unable to acquire equipment to streamline its production process, or that the expansion of its production facilities will not result in the benefits currently expected; that companies currently working with GMG or parties that have entered into NDA arrangements with the Company will not be interested in purchasing the Company's products; that GMG's products may not perform as anticipated or deliver the expected commercial benefits; that GMG's proprietary production processes may not provide an alternative to traditional graphite supply chains; that the Company will be unable to grow its sales or revenues as anticipated; that third-party market data and industry projections will not be accurate as presented; and the risk factors set out under the heading "Risk Factors" in the Company's annual information form dated November 04, 2025 available for review on the Company's profile at www.sedarplus.ca.
Although management of the Company has attempted to identify important factors that could cause actual results to differ materially from those contained in forward-looking statements or forward-looking information, there may be other factors that cause results not to be as anticipated, estimated or intended. There can be no assurance that such statements will prove to be accurate, as actual results and future events could differ materially from those anticipated in such statements. Accordingly, readers should not place undue reliance on forward-looking statements and forward-looking information. Readers are cautioned that reliance on such information may not be appropriate for other purposes. The Company does not undertake to update any forward-looking statement, forward-looking information or financial outlook that is incorporated by reference herein, except in accordance with applicable securities laws.
To view the source version of this press release, please visit https://www.newsfilecorp.com/release/313606
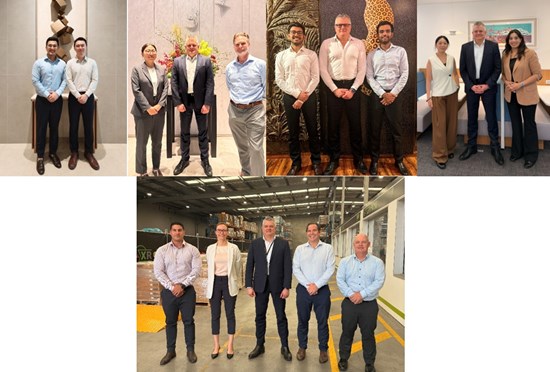
Brisbane, Queensland–(Newsfile Corp. – September 8, 2026) – Graphene Manufacturing Group Ltd. (TSXV: GMG) (OTCQX: GMGMF) ("GMG" or the "Company") is pleased to announce the launch of the GMG Asia Pacific Sales Team which has been performing business development in their various country markets since early 2026. The GMG Asia Pacific Sales Team is initially based in India, South Korea, and the Japan and Singapore, in addition to the team in Australia, as seen in Figure 1.
Figure 1: Photos of some of the GMG Asia Pacific Sales & Marketing Team including the teams (from left to right) Singapore, Japan, India, Korea and Australia.
To view an enhanced version of this graphic, please visit:https://images.newsfilecorp.com/files/8082/313340_figure1_gmg_550.jpg
Craig Nicol, Founder, Managing Director and CEO of GMG, commented: "The launch of our dedicated Asia Pacific Sales Team marks an important step in GMG's global commercialisation strategy. Having spent much of my career building and leading sales and marketing teams across Asia Pacific, I understand firsthand the scale of opportunity these markets represent for graphene-enhanced thermal, lubricant and energy storage solutions. India, South Korea, Japan and South-East Asia are home to some of the world's largest and fastest-growing manufacturing, automotive, electronics and data-centre industries, and together with Australia and New Zealand they represent a natural extension of our go-to-market footprint. Our new team has already been engaging directly with customers and channel partners across the region since early 2026, and we are encouraged by the level of interest and early traction we are seeing. This regional build-out complements our recent production milestones, including the start-up of our Gen 2.0 graphene production plant, and positions GMG to convert growing global demand into commercial outcomes across some of the most important industrial economies in the world."
Jack Perkowski, Chairman and Non-Executive Director of GMG, commented: "The Board is very pleased to see GMG take this next step in its international growth strategy. Establishing a dedicated presence in Asia Pacific is a logical and important move given the depth of industrial activity in these markets and their relevance to GMG's core product lines in thermal management, lubricants and energy storage. This is a region I know well from my own experience helping international companies establish and scale operations in Asia, and I am confident that GMG's new team will be well placed to build the relationships and market knowledge required to succeed there. The Board looks forward to updating shareholders on the team's progress as it builds out its pipeline across India, South Korea, Japan, South-East Asia, Australia and New Zealand."
About GMG
GMG is an Australian based clean-technology company which develops, makes and sells energy saving and energy storage solutions, enabled by graphene manufactured via in house production process. GMG uses its own proprietary production process to decompose natural gas (i.e. methane) into its natural elements, carbon (as graphene), hydrogen and some residual hydrocarbon gases. This process produces high quality, low cost, scalable, 'tuneable' and low/no contaminant graphene suitable for use in clean-technology and other applications.
The Company's present focus is to de-risk and develop commercial scale-up capabilities, and secure market applications. In the energy savings segment, GMG has initially focused on graphene enhanced heating, ventilation and air conditioning ("HVAC-R") coating (or energy-saving coating) which is now being marketed into other applications including electronic heat sinks, industrial process plants and data centres. Another product GMG has developed is the graphene lubricant additive focused on saving liquid fuels initially for diesel engines. GMG is also developing a graphene coolant additive focused on energy saving for data centres and industrial cooling applications.
In the energy storage segment, GMG and the University of Queensland are working collaboratively with financial support from the Australian Government to progress R&D and commercialization of GMG Graphene Batteries. GMG has also developed a graphene additive slurry that is aimed to improve the performance of lithium-ion batteries.
GMG's 4 critical business objectives are:
Produce Graphene and improve/scale cell production processes
Build Revenue from Energy Savings Products
Develop Next-Generation Battery
Develop Supply Chain, Partners & Project Execution Capability
For further information please contact:
-
Craig Nicol, Chief Executive Officer & Managing Director of the Company at craig.nicol@graphenemg.com, +61 415 445 223
-
Leo Karabelas at Focus Communications Investor Relations, leo@fcir.ca, +1 647 689 6041
Neither the TSX Venture Exchange nor its Regulation Services Provider (as that term is defined in the policies of the TSX Venture Exchange) accept responsibility for the adequacy or accuracy of this news release.
Cautionary Note Regarding Forward-Looking Statements
This news release includes certain statements and information that may constitute forward-looking information within the meaning of applicable Canadian securities laws. Forward-looking statements relate to future events or future performance and reflect the expectations or beliefs of management of the Company regarding future events. Generally, forward-looking statements and information can be identified by the use of forward-looking terminology such as "intends", "expects" or "anticipates", or variations of such words and phrases, or statements that certain actions, events or results "may", "could", "should", "would" or will "potentially" or "likely" occur. These statements, referred to herein as "forward-looking statements", are not historical facts, are made as of the date of this news release and include, without limitation, statements regarding: the Company's launch and continued operation of the GMG Asia Pacific Sales Team; the Team's business development activities and its ability to build relationships, market knowledge and sales pipeline in India, South Korea, Japan, South-East Asian, Australian and New Zealand markets; the size, growth and commercial opportunity represented by these markets for GMG's products, including THERMAL-XR®, G® LUBRICANT, G FLUID™ and graphene-based energy storage solutions; GMG's expectations regarding customer and channel partner interest and engagement in the Asia Pacific region; the Company's plans to expand its regional sales, marketing and business development presence and resourcing over time; the anticipated contribution of the Asia Pacific Sales Team to GMG's broader global commercialisation and revenue growth strategy; and GMG's intentions with respect to converting regional business development activity into commercial orders and revenue.
Such forward-looking statements are based on a number of assumptions of management, including, without limitation, assumptions that: the Company's operational and strategic progress will continue; the GMG Asia Pacific Sales Team will be able to successfully identify, engage and convert customers and channel partners in its target markets; demand for GMG's products in India, South Korea, Japan, South-East Asia, Australia and New Zealand will develop in line with management's expectations; the Company will have sufficient management, financial and operational resources to support the Team's ongoing activities and any future expansion; general economic, business and market conditions in the region will remain stable and supportive of GMG's commercialisation efforts; the Company's cash position and business fundamentals remain strong; and no material adverse regulatory, trade or currency developments will impede the Team's business development activities.
Additionally, forward-looking information involves a variety of known and unknown risks, uncertainties and other factors which may cause the actual plans, intentions, activities, results, performance or achievements of GMG to be materially different from any future plans, intentions, activities, results, performance or achievements expressed or implied by such forward-looking statements. Such risks include, without limitation, fluctuations in the Company's share price that may increase the warrant liability; the risk that the GMG Asia Pacific Sales Team is unable to generate customer interest, sales pipeline or orders within the timeframe or at the scale currently anticipated; the risk that market adoption of GMG's products in Asia Pacific markets is slower or smaller than anticipated; competition from existing or new market participants in the region; risks associated with operating in multiple international jurisdictions, including differing regulatory, trade, customs and import requirements, language and cultural factors, and reliance on local distributors or partners; foreign exchange volatility affecting the cost or profitability of regional operations; failure to achieve operational or commercial milestones; inability to commercialise products; changes in accounting standards; adverse market conditions; and the risk factors set out under the heading "Risk Factors" in the Company's annual information form dated November 4, 2025 available for review on the Company's profile at www.sedarplus.ca.
Although management of the Company has attempted to identify important factors that could cause actual results to differ materially from those contained in forward-looking statements or forward-looking information, there may be other factors that cause results not to be as anticipated, estimated or intended. There can be no assurance that such statements will prove to be accurate, as actual results and future events could differ materially from those anticipated in such statements. Accordingly, readers should not place undue reliance on forward-looking statements and forward looking information. Readers are cautioned that reliance on such information may not be appropriate for other purposes. The Company does not undertake to update any forward-looking statement, forward-looking information or financial outlook that are incorporated by reference herein, except in accordance with applicable securities laws.
To view the source version of this press release, please visit https://www.newsfilecorp.com/release/313340
Southern Copper Corporation SCCO delivered a solid 116.9% year-over-year surge in the operating cash flow in the first six months of 2026 to $3.68 billion. Southern Copper’s strong cash generation is driven by higher sales and a $718.5-million reduction in operating assets and liabilities requirements.The company also benefited from its cash cost decrease, which was driven by a 68.2% year-over-year rise in by-product revenue credits. Cash and cash equivalents stood at $5.67 billion as of June 30, 2026, while capital investments totaled $864.7 million.
Over the past few years, Southern Copper has successfully lowered its debt levels. Long-term debt was $7.99 billion at the end of June 30, 2026, following the issuance of $1.25 billion of 10-year senior unsecured notes carrying a 5.35% interest rate. The proceeds are intended primarily to support the Tía María project and other capital needs of the company’s Peruvian operations.
In July 2026, the board authorized a $1.10-per-share cash dividend plus a stock dividend of 0.012 shares per common share, reflecting continued capital returns alongside higher investment spending. The company’s copper production declined 3.8% year over year to 461,206 tons in the first half of 2026 due to a decrease in production at the company’s Peruvian operations. Despite the year-to-date fall in production, the company has slightly hiked its 2026 copper production outlook to 917,000 tons from the initially stated 910,000 tons. The figure still implies a 5% year-over-year decline. Nonetheless, Southern Copper maintains a strong long-term outlook with production expected to increase to 1.6 million tons by 2033 or 2034.
Moreover, copper prices are currently near $6.6 per pound, up 47% in a year, supported by tight global supply and strong demand. Along with SCCO, its peers Teck Resources Ltd TECK and Freeport-McMoRan Inc. FCX are gaining from this rise in copper prices. Higher prices for molybdenum, zinc and silver will also aid growth.
The rally in metal prices this year and its ongoing cost control efforts position the company for further cash flow gains in the months ahead.
Southern Copper Peers’ Cash Flow Performance
Teck Resources’ cash flow from operating activities improved to C$2.74 billion ($1.98 billion) in the first half of 20206 from a cash outflow of C$427 million ($309 million). Teck Resources ended the second quarter 2026 with C$6.05 billion ($4.38 billion) in cash and cash equivalents, and liquidity of C$10.3 billion ($7.5 billion).
Teck Resources’ copper segment’s revenues surged 85% year over year, driven by higher copper prices and sales volumes. This pushed the company’s top line to $2.6 billion, marking a 78% year-over-year rise. Freeport-McMoRan’s cash flow from operations increased to $3.68 billion in the first half from $1.69 billion in the prior year. Freeport-McMoRan ended the second quarter with strong liquidity, including $4.1 billion in cash and cash equivalents, $3 billion in availability under the Freeport revolving credit facility, and $1.5 billion in availability under the PT-FI credit facility.However, revenues declined 7.3% year over year to $7.03 billion in the second quarter of 2026. Freeport-McMoRan’s copper production fell 18.4% year over year to 786 million pounds in the reported quarter.
SCCO’s Price Performance, Valuations & Estimates
Southern Copper shares have gained 40.7% year to date compared with the Zacks Mining – Non Ferrous industry’s rise of 28.9%. During this time, the Basic Materials sector has risen 22.1% and the S&P 500 has rallied 13.2%.
Image Source: Zacks Investment Research
The Southern Copper stock is currently trading at a forward 12-month earnings multiple of 27.80X, which is a premium to the industry average of 23.62X.
Image Source: Zacks Investment Research
The Zacks Consensus Estimate for Southern Copper’s 2026 sales is $16.86 billion, indicating a 25.6% year-over-year jump. The consensus mark for the year’s earnings is pegged at $7.59 per share, suggesting a rally of 44.8%.
The Zacks Consensus Estimate for 2027 sales implies an 11.7% year-over-year dip. The same for earnings suggests a fall of 8.5%.
Earnings estimates for 2026 have moved 0.4% south over the past 60 days, while the same for 2027 have moved down 0.1% over the past 60 days.
Image Source: Zacks Investment Research
The company currently carries a Zacks Rank #3 (Hold). You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Southern Copper Corporation (SCCO) : Free Stock Analysis Report
Freeport-McMoRan Inc. (FCX) : Free Stock Analysis Report
Teck Resources Ltd (TECK) : Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).
Investors interested in stocks from the Mining – Miscellaneous sector have probably already heard of Teck Resources Ltd (TECK) and Wheaton Precious Metals Corp. (WPM). But which of these two stocks is more attractive to value investors? We'll need to take a closer look to find out.
The best way to find great value stocks is to pair a strong Zacks Rank with an impressive grade in the Value category of our Style Scores system. The proven Zacks Rank puts an emphasis on earnings estimates and estimate revisions, while our Style Scores work to identify stocks with specific traits.
Right now, Teck Resources Ltd is sporting a Zacks Rank of #2 (Buy), while Wheaton Precious Metals Corp. has a Zacks Rank of #3 (Hold). Investors should feel comfortable knowing that TECK likely has seen a stronger improvement to its earnings outlook than WPM has recently. However, value investors will care about much more than just this.
Value investors analyze a variety of traditional, tried-and-true metrics to help find companies that they believe are undervalued at their current share price levels.
Our Value category highlights undervalued companies by looking at a variety of key metrics, including the popular P/E ratio, as well as the P/S ratio, earnings yield, cash flow per share, and a variety of other fundamentals that have been used by value investors for years.
TECK currently has a forward P/E ratio of 19.11, while WPM has a forward P/E of 32.68. We also note that TECK has a PEG ratio of 2.39. This popular metric is similar to the widely-known P/E ratio, with the difference being that the PEG ratio also takes into account the company's expected earnings growth rate. WPM currently has a PEG ratio of 2.77.
Another notable valuation metric for TECK is its P/B ratio of 1.61. The P/B is a method of comparing a stock's market value to its book value, which is defined as total assets minus total liabilities. By comparison, WPM has a P/B of 7.34.
These are just a few of the metrics contributing to TECK's Value grade of B and WPM's Value grade of F.
TECK stands above WPM thanks to its solid earnings outlook, and based on these valuation figures, we also feel that TECK is the superior value option right now.
Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Teck Resources Ltd (TECK) : Free Stock Analysis Report
Wheaton Precious Metals Corp. (WPM) : Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).
Andromeda Metals raises $3.04 million to advance high-purity alumina project Proactive uses images sourced from Shutterstock
Andromeda Metals Ltd (ASX:ADN, OTC:ANDMF) has raised $3.04 million before costs through a share purchase plan (SPP) and share placement, with proceeds to support development of its High Purity Alumina (HPA) Project.
The company raised $2.94 million through the SPP, which attracted participation from 342 eligible shareholders, alongside a further $102,000 placement to non-related parties.
Funds to support HPA pre-feasibility study
The placement comprised 17.29 million new shares issued at $0.0059 per share, the same price offered under the SPP.
The proceeds would primarily be directed towards advancing the HPA Project, including supporting completion of a pre-feasibility study (PFS).
Funds will also provide general working capital and cover costs associated with the capital raising.
Shareholder support
The SPP had initially targeted approximately $3 million before costs, with Andromeda retaining discretion to accept oversubscriptions.
Following completion of the offer and the additional placement, total proceeds reached $3.044 million.
The board thanked shareholders for their participation in the SPP and continued support for the company.
This article first appeared on GuruFocus.
- Cash Position: Held cash and term deposits of AUD723 million at year-end, including the second tranche of the May placement that settled in July.
- Equity Raised: Raised over AUD930 million through three private placements and shareholder purchase plans during the year.
- Pro Forma Cash: On a pro forma basis, the company would have held cash of greater than AUD900 million.
- Convertible Notes: Executed long-form documentation for AUD200 million of convertible notes with NROC in May 2026.
- Strategic Equity Subscriptions: Entered binding subscription agreements for a total of AUD230 million with KfW (German Raw Materials Fund) and Export Finance Australia in March 2026.
- Offtake Agreements: Secured a binding offtake term sheet with Traxys North America for 500 tons of NdPr and 700 tons of Dy and Tb, and a term sheet with an Indian group for an additional 500 tons of NdPr and 7 tons per annum of Dy and Tb.
- Warning! GuruFocus has detected 1 Warning Sign with ARAFF.
- Is ARAFF fairly valued? Test your thesis with our free DCF calculator.
Release Date: September 04, 2026
For the complete transcript of the earnings call, please refer to the full earnings call transcript.
Positive Points
- Arafura Rare Earths Ltd (ARAFF) has secured offtake agreements into five countries and ECA-covered debt from five countries, demonstrating strong multi-government and international support.
- The company has successfully raised over AUD 930 million in equity, including strategic investments from the NRF, EFA, and the German Raw Materials Fund, fully funding the Nolans Project.
- NdPr prices have seen a sustained lift, with the introduction of US and Japan pricing floors stabilizing the market and supporting a more transparent pricing environment.
- The Nolans Project is uniquely positioned as the only ore-to-oxide rare earth project in construction globally, offering a strategic advantage to bypass Chinese supply chains.
- The company has identified potential capital cost reductions of over AUD 200 million through design optimizations, helping to offset inflationary pressures on the project.
- Arafura Rare Earths Ltd (ARAFF) has secured binding offtake term sheets for its heavy rare earths (DyTb), with pricing mechanisms linked to independent, transparent seaborne indices.
- Construction is on track to commence in September 2026, with a clear 37-month schedule and a de-risked execution plan following early works completed in 2022.
Negative Points
- The company's share price performance has not met expectations, trading near its cash value, which management acknowledges is a significant concern for shareholders.
- Arafura Rare Earths Ltd (ARAFF) faces substantial project execution risks due to the complexity and remote location of the Nolans Project, which could lead to schedule delays or budget overruns.
- The company's market valuation is significantly lower than peers like Lynas Rare Earths and MP Materials, despite similar production levels, indicating a lack of investor confidence.
- China remains structurally dominant in the rare earths market, and its export controls and policy actions continue to pose a significant geopolitical risk to the rest-of-world supply chain.
- The company has experienced significant dilution from multiple capital raisings, which has impacted existing shareholders despite being necessary to fund the project.
- Arafura Rare Earths Ltd (ARAFF) is still awaiting final credit approvals from a small number of lenders to achieve contractual close on its project financing, creating uncertainty.
- The ramp-up to nameplate production is forecast to take two to three years after practical completion, which is a long period before the project can generate significant revenue.
Q & A Highlights
Q: Can you provide more clarification on the physical start date of major construction works and the timeline for key milestones?A: Darryl Cuzzubbo (CEO & Managing Director) confirmed that construction will start in September as planned, with access works beginning in about two weeks. The next large contract, bulk earthworks, is expected to be released in the middle of next quarter, with a goal to complete them by the middle of next year to allow concrete works to begin. This outlines the high-level critical path for the next six months.
Q: What is the Nolans' expected annual DyTb output, what percentage is locked into binding offtake agreements, and what is the plan for selling the remainder? Are these contracts index priced or do they have floor mechanisms?A: Peter Sherrington (CFO) stated that the project recovers roughly 40 tons of DyTb annually. They have already contracted approximately 15 tons with Traxys North America and an Indian counterparty. The remaining product will be matched with customers who require NdPr, particularly EV automakers needing high-performance magnets. Regarding pricing, they are unlikely to put a floor in but will negotiate annual prices or use mechanisms reflecting the tightness in the marketplace, though specific pricing regimes are commercial in confidence.
Q: Can you elaborate on the studies underway to increase recoveries of heavy rare earths and/or separate them further?A: Darryl Cuzzubbo (CEO & Managing Director) explained that they are looking at a separate project to process additional heavies, potentially recovering additional DyTb from the waste stream to increase output from 40 tons to 50-55 tons. This would also involve processing it into a separate DyTb oxide. This is a separate project subject to a separate decision that will be brought to the market at a later point.
Q: How will the ore-to-oxide refining process be conducted more safely and environmentally responsibly in Australia compared to China?A: Darryl Cuzzubbo (CEO & Managing Director) noted that with nine lenders across five countries, they must meet international standards. The process is similar to hydrometallurgical solvent extraction used at Olympic Dam and can be done responsibly. Peter Sherrington (CFO) added that a key differentiator is that all waste material is handled on a single site under one residue storage facility with one regulator, unlike in China where processing is often done at separate sites. Tommie van der Walt (Chief Projects Officer) added that environmental impact is part of the design criteria.
Q: How long after commencement of construction until you have product to sell, and what is the timeline to mechanical completion?A: Darryl Cuzzubbo (CEO & Managing Director) outlined a 37-month construction schedule from the start of construction in September. Practical completion is expected towards the end of 2029, followed by a two-year commissioning and ramp-up process. This would see first production at the end of 2029, with production reaching nameplate capacity at the end of 2031 or early 2032.
Q: Will the debt be finalized and binding prior to your departure, and what are the conditions around the US government $300 million debt facility? Will it be executed as part of the full debt stack?A: Peter Sherrington (CFO) confirmed that reaching contractual close is one of his main objectives before leaving. He clarified that the $775 million of senior debt facilities excludes the letter of support from US EXIM. The US EXIM facility is not considered part of the initial senior debt stack but is an opportunity to be pursued alongside any project expansion, such as for heavy rare earths or a stage 2.
Q: The share price performance has not met expectations. What are we doing as a company to improve the share price going forward?A: Darryl Cuzzubbo (CEO & Managing Director) acknowledged the situation, noting the company's cash balance is not much different from its market cap. He outlined two key actions: continuing to get in front of investors to highlight their unique position as the only ore-to-oxide project in construction that can bypass China, and delivering on construction milestones. He noted that other rare earths projects have also pulled back, but expects a re-rating as they progress and deliver on their commitments.
Q: Does the current board composition have the right people to successfully deliver the Nolans Project and support the executive team?A: Darryl Cuzzubbo (CEO & Managing Director) explained that over the last two years, they have deliberately built out both the management team and the board with execution capability for the construction phase. He highlighted recent board appointments including Mike Spreadborough with operational expertise from Olympic Dam, Roger Higgins with large project experience, and Ian Murray with financial and CEO experience. He stated they are well-positioned from both a board and management perspective for the current phase.
Q: What are the specific initiatives and capital market communication plans in place to protect the company's standing in the S&P/ASX 300 and MSCI indexes?A: Darryl Cuzzubbo (CEO & Managing Director) stated they continue to engage with investors in Australia, Asia, and North America, highlighting their position as an alternative to China. He pointed out the discrepancy between their market cap and that of peers like Lynas and MP Materials, despite similar production levels. A company representative added that they recognize the need for broader research coverage and are working on an engagement program including institutional meetings, analyst briefings, and targeted outreach. Angela Bigg (new CFO) emphasized the importance of demonstrating credibility by delivering on milestones.
Q: Following FID, what are the remaining conditions to be satisfied to achieve financial close and senior debt drawdown?A: Peter Sherrington (CFO) explained that FID has been called, and the next critical milestones are contractual close, which requires closing out a couple of final credit approvals. Most lenders are complete and ready to go, but the whole group must be ready to execute. Following that, the settlement of strategic investments from EFA and the German Raw Materials Fund is critical for construction to commence.
Q: Are there any expectations that further capital will be required, and what about potential future dilution?A: Darryl Cuzzubbo (CEO & Managing Director) stated clearly that the company is currently fully funded and focused on construction. There is no work on any capital raises at this time.
Q:
For the complete transcript of the earnings call, please refer to the full earnings call transcript.
The Basic Materials group has plenty of great stocks, but investors should always be looking for companies that are outperforming their peers. Is Teck Resources Ltd (TECK) one of those stocks right now? A quick glance at the company's year-to-date performance in comparison to the rest of the Basic Materials sector should help us answer this question.
Teck Resources Ltd is a member of our Basic Materials group, which includes 279 different companies and currently sits at #15 in the Zacks Sector Rank. The Zacks Sector Rank considers 16 different groups, measuring the average Zacks Rank of the individual stocks within the sector to gauge the strength of each group.
The Zacks Rank emphasizes earnings estimates and estimate revisions to find stocks with improving earnings outlooks. This system has a long record of success, and these stocks tend to be on track to beat the market over the next one to three months. Teck Resources Ltd is currently sporting a Zacks Rank of #2 (Buy).
Over the past 90 days, the Zacks Consensus Estimate for TECK's full-year earnings has moved 8.4% higher. This shows that analyst sentiment has improved and the company's earnings outlook is stronger.
Based on the latest available data, TECK has gained about 43.7% so far this year. Meanwhile, stocks in the Basic Materials group have gained about 21.3% on average. This means that Teck Resources Ltd is outperforming the sector as a whole this year.
Another stock in the Basic Materials sector, Trekor Metals (TGB), has outperformed the sector so far this year. The stock's year-to-date return is 48.4%.
Over the past three months, Trekor Metals' consensus EPS estimate for the current year has increased 21.4%. The stock currently has a Zacks Rank #2 (Buy).
To break things down more, Teck Resources Ltd belongs to the Mining – Miscellaneous industry, a group that includes 89 individual companies and currently sits at #192 in the Zacks Industry Rank. This group has gained an average of 31% so far this year, so TECK is performing better in this area. Trekor Metals is also part of the same industry.
Going forward, investors interested in Basic Materials stocks should continue to pay close attention to Teck Resources Ltd and Trekor Metals as they could maintain their solid performance.
Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Teck Resources Ltd (TECK) : Free Stock Analysis Report
Trekor Metals Limited (TGB) : Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).
Toronto, Ontario–(Newsfile Corp. – September 4, 2026) – Honey Badger Silver Inc. (TSXV: TUF) (OTCQB: HBEIF) (FSE: 1QA) (Tradegate: 1QA) ("Honey Badger Silver" or the "Company") is pleased to announce the details of the 2026 field exploration program at its 100%-owned Nanisivik Project on Baffin Island, Nunavut.
Chad Williams, Executive Chairman and Interim CEO, commented:
"Our focus for the 2026 on-site work at Nanisivik was to substantiate the potential of this project to host economic zones of silver-bearing mineralization. Importantly, mineralization at Nanisivik is known to contain zinc, lead, and potentially many other critical minerals. In particular, historic references to large existing silver-bearing pyrite zones are now very interesting because of the recent dramatic rise in the price of sulphur. In addition, the substantial rise in the price of certain critical minerals – like germanium – given their new highly strategic importance, has motivated Honey Badger to look at Nanisivik with a fresh lens. These minerals were never considered important during the many years that Nanisivik operated as an underground mine. In summary, Nanisivik contains many promising zones located throughout the large project area controlled by Honey Badger."
2026 FIELD PROGRAM AND NEXT STEPS
Building upon the Company's positive 2025 exploration results and its recently announced initiative to evaluate extensive massive-pyrite mineralization (see News Release dated July 28, 2026), the recently executed 2026 field program was designed to advance two specific emerging opportunities at Nanisivik: 1) the documented extensive massive-pyrite system and 2) additional silver-zinc-lead mineralization and critical-mineral potential located outside of the historic mined zones, providing an opportunity to further characterize the mineralized system using modern analytical methods.
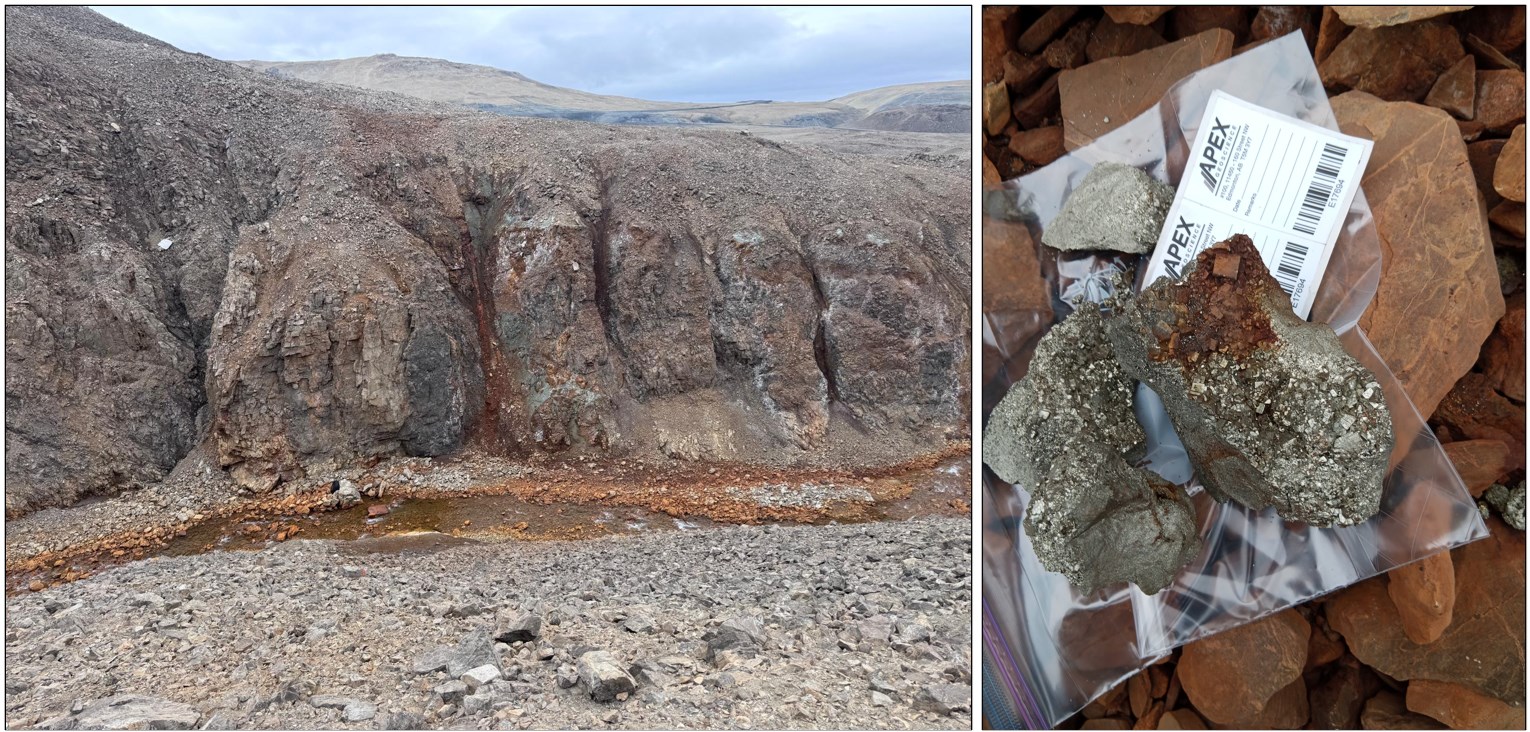
The field team was managed by APEX Geoscience, overseen by Honey Badger Silver. The team successfully collected samples of massive pyrite as well as other potentially mineralized samples containing sphalerite, galena, and pyrite, from both float and outcrop across multiple zones across the property (see Figure 1).
Figure 1. Photographs from the 2026 field program at Nanisivik where the crew located massive pyrite (right image) in float material interpreted to have come from the overlying gossanous outcrop (left image). Assays are pending.
To view an enhanced version of this graphic, please visit:https://images.newsfilecorp.com/files/3204/312932_96ca7a602416d8c5_001full.jpg
Samples collected during the program were transported under chain-of-custody procedures and submitted to an independent accredited laboratory for multi-element geochemical analysis. The Company expects the analytical results to provide valuable information on the composition of the pyrite-rich mineralization and to assist in evaluating the potential for germanium and other critical or potentially valuable elements within the system.
Upon receipt of the analytical results, Honey Badger Silver will integrate the new data with historical geological, geochemical and geophysical information to refine its understanding of the Nanisivik mineralized system. The Company will then evaluate opportunities for additional analytical work, metallurgical testing and other follow-up studies, as warranted, and assess potential future exploration programs, including drilling and/or other methods of testing priority targets.
NANISIVIK HIGHLIGHTS
-
Proven mineralized district: The former Nanisivik Mine produced approximately 17.9 Mt grading 9% zinc, 0.7% lead and 35 g/t silver, equivalent to 3.55 billion pounds of zinc, 284 million pounds of lead and 20.1 million ounces of silver.1
-
Potential large-scale sulphur opportunity: Historical publications reported an estimated 50–100 Mt of massive pyrite mineralization within the South Boundary and North Pyrite zones (see additional information below).2
-
Critical-minerals upside: Honey Badger Silver is evaluating the extensive sulphide system for germanium and other critical minerals that were not systematically evaluated during historical mining.
-
Additional high-grade exploration targets: Recent prospecting at the Area 14 Target returned grab samples grading up to 249 g/t silver and 51.5% zinc, while geophysics identified new conductors away from the former mine site.
-
2026 assays pending: New samples of massive pyrite and prospective polymetallic mineralization have been submitted for modern multi-element analysis, providing a potential near-term catalyst.
ABOUT NANISIVIK
The Nanisivik Project is located on northern Baffin Island, Nunavut, near the community of Arctic Bay and encompasses the area surrounding the former Nanisivik Mine. The mine operated from 1976 to 2002 and produced approximately 17.9 million tonnes of ore grading 9% zinc, 0.7% lead and 35 g/t silver, equivalent to approximately 3.55 billion pounds of zinc, 284 million pounds of lead and 20.1 million ounces of silver prior to closing down in 2002 due to falling metal prices.1
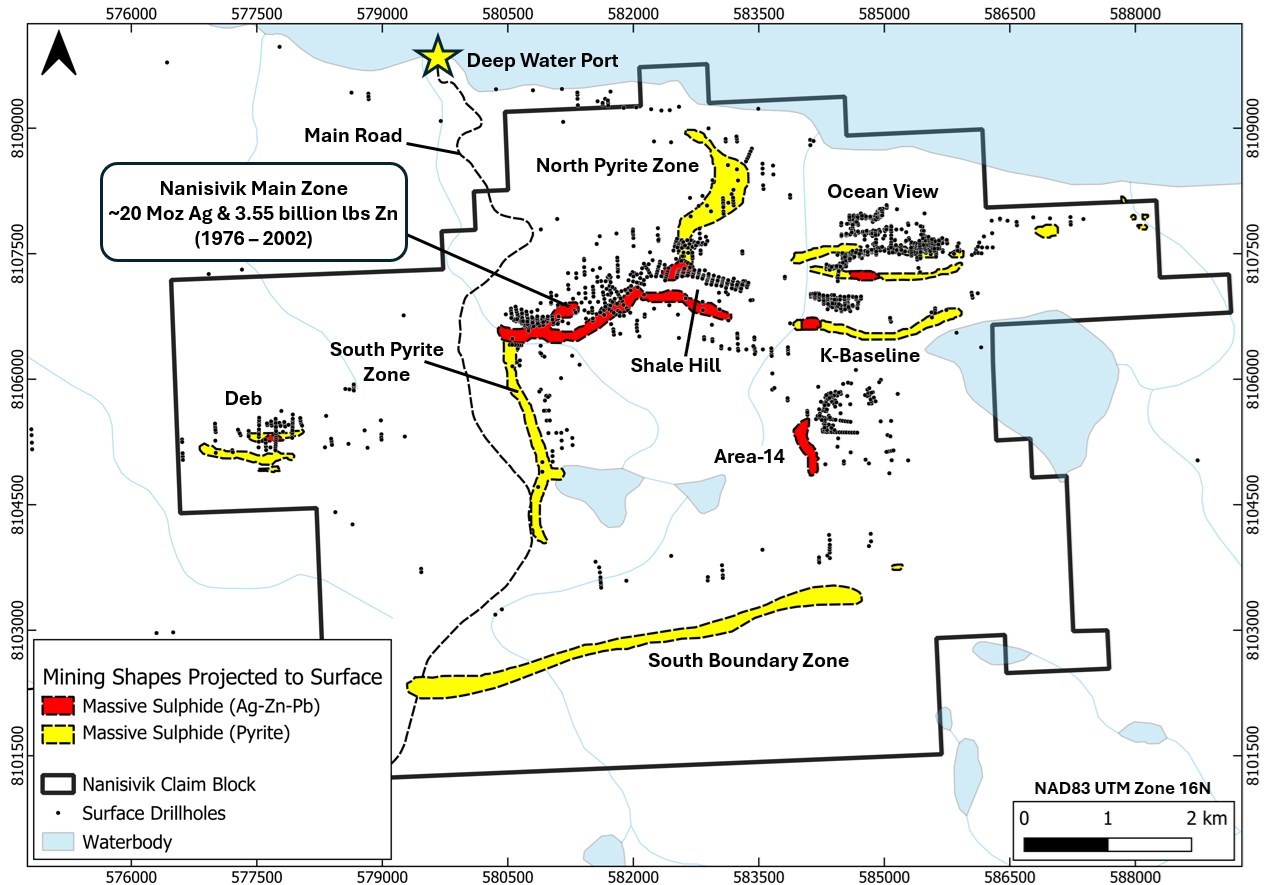
In addition to the mineralization that was mined, historical publications describing mining operations at Nanisivik indicate the presence of extensive massive pyrite mineralization within the South Boundary Zone and North Pyrite Zone (Figure. 2).2 McNeil et al. (1993) reported a historical, non-compliant estimate ranging from 50 to 100 million tonnes of massive pyrite.2 The Company considers the estimate to be relevant as it highlights the potential for a large pyrite-bearing system at Nanisivik and supports the exploration rationale for evaluating the sulphur potential of the property. While the estimate was reported by authors familiar with mine operations and regional geology at the time, the reliability of the estimate is uncertain because the publication does not disclose sufficient information regarding the estimation methodology, assumptions, classification criteria, or supporting data necessary to evaluate the estimate under current CIM standards or NI 43-101 requirements. Verification and potential upgrading of the historical estimate would likely require review of available historical geological, sampling and drilling data, together with confirmatory drilling and sampling to validate the extent and continuity of the pyrite mineralization. A Qualified Person has not completed sufficient work to classify these historical figures as current mineral resources or mineral reserves, and the Company is not treating them as such.
The Nanisivik mineralized system also exhibits potential for germanium and other critical metals, which were not systematically evaluated during historical mining operations, but noted in past reports to be associated with metals like zinc.3 Honey Badger Silver is undertaking additional sampling and analysis to evaluate the potential for germanium and other critical minerals within existing and potentially new zones of mineralization.
Honey Badger Silver has also identified potential silver-zinc-lead mineralization outside the historic mine workings, including multiple priority targets generated through its review of historical drilling and geophysical data. Recent exploration has highlighted the Area 14 and Oceanview areas, where prospecting returned grab samples grading up to 249 g/t silver and 51.5% zinc, and geophysical surveys identified new untested conductors (see News Release dated December 1, 2025).
The combination of a past-producing high-grade silver-zinc-lead mine, an extensive pyrite-bearing sulphide system, opportunity for finding new polymetallic mineralization and potential critical-mineral content provides Honey Badger Silver with multiple avenues for value creation at Nanisivik.
Figure 2. Property map of the Nanisivik Project showing surface projections of the massive pyrite and Silver-Zinc-Lead bodies. Historic surface drillholes are also shown.
To view an enhanced version of this graphic, please visit:https://images.newsfilecorp.com/files/3204/312932_96ca7a602416d8c5_002full.jpg
ERRATUM
The Company wishes to correct an error in its previous disclosure dated August 27, 2026, regarding historical drill results from the Yava Main Zone. The previously reported result for drill hole DH Y-74-01 was stated as 40.1 meters grading 67.53 g/t silver, 1.1% copper, 3.73% zinc, 0.54% gold and 0.36% lead, with an estimated true width of approximately 23 meters.4 The gold grade was incorrectly reported as 0.54% in the previous release; the correct grade is 0.54 g/t gold. All other reported values remain unchanged.
About Honey Badger Silver (TSXV: TUF) (OTCQB: HBEIF) (FSE: 1QA) (Tradegate: 1QA)
Honey Badger Silver is a leading North American silver and critical minerals company. Backed by an impressive portfolio of 8 high-quality silver mineral projects across the Northwest Territories, Yukon, and Nunavut, including the fully permitted, high-grade PC Silver Mine, Sunrise Lake, Plata, Yava and Nanisivik properties, Honey Badger Silver controls district-scale land positions in some of the most metal-rich jurisdictions on the continent.
What sets Honey Badger Silver apart is its strategic blend of real silver ownership and growth leverage: the Company holds over 10,000 ounces of physical silver yielding 12% annually, reinforcing tangible asset value while advancing aggressive exploration and acquisition plans.
Led by a proven team of mine-builders and capital markets professionals, Honey Badger Silver is building a cash-generating, asset-backed platform for the bull cycle in precious and critical minerals.
More information is available at www.honeybadgersilver.com.
Chad WilliamsExecutive Chairman, Interim CEO
Investor Relationsinvestors@honeybadgersilver.com | +1 (647) 226-7315
Historical Information
(1) Patterson, D.J., & Powis, K.B. (2002). Structural and Stratigraphic Controls on Zn-Pb-Ag Mineralization at the Nanisivik Mississippi Valley-Type Deposit, Northern Baffin Island, Nunavut. Geological Survey of Canada, Current Research 2002-C22.(2) McNeil, W.H., Rawling, K.R. and Sutherland, R.A. (1993). Nanisivik Mine – Operations and Innovations in an Arctic Environment. Proceedings of World Zinc '93, pp. 41–52.(3) Sutherland, R.A. and Dumka, D., 1995. Geology of Nanisivik Mine, N.W.T., Canada. In: Misra, K.C. (ed.), Carbonate-Hosted Lead-Zinc-Fluorite-Barite Deposits of North America. Society of Economic Geologists, Guidebook Series, Vol. 22, p. 4–12.(4) Cote, R. and Campbell, C. (2008). The Yava Property of Savant Explorations Limited, Hackett-Back River Greenstone Belt, Mackenzie Mining District, Territory of Nunavut, Canada: The 2007 High Resolution HeliGEOTEM Survey and Preliminary Ground Follow-Up Using Rock and Soil Geochemical Sampling over Selected A.E.M. Anomalies. National Instrument 43-101 Technical Report, dated February 15, 2008.
Neither the TSX Venture Exchange nor its Regulation Services Provider (as that term is defined in the policies of the TSX Venture Exchange) accepts responsibility for the adequacy or accuracy of this release.
Qualified Person
The scientific and technical data contained in this news release pertaining to the Project was reviewed and approved by Andrew Jedemann, MSc., P.Geo. who is an independent consultant and "qualified person" within the meaning of NI 43-101.
This news release does not constitute an offer to sell or a solicitation of an offer to buy, nor shall there be any sale of any of the securities in any jurisdiction in which such offer, solicitation or sale would be unlawful, including any of the securities in the United States of America. The securities have not been and will not be registered under the United States Securities Act of 1933, as amended (the "1933 Act") or any state securities laws, and may not be offered or sold within the United States or to, or for account or benefit of, U.S. Persons (as defined in Regulation S under the 1933 Act) unless registered under the 1933 Act and applicable state securities laws, or an exemption from such registration requirements is available.
Cautionary Note Regarding Forward-Looking Information
This news release contains "forward-looking information" within the meaning of applicable Canadian securities legislation that is based on expectations, estimates, projections and interpretations as at the date of this news release, including, without limitation, Honey Badger Silver's strategic objectives and the potential of the Company's mineral projects. Any statement that involves discussions with respect to predictions, expectations, interpretations, beliefs, plans, projections, objectives, assumptions, future events or performance (often but not always using phrases such as "expects", or "does not expect", "is expected", "interpreted", "management's view", "anticipates" or "does not anticipate", "plans", "budget", "scheduled", "forecasts", "estimates", "believes" or "intends" or variations of such words and phrases or stating that certain actions, events or results "may" or "could", "would", "might" or "will" be taken to occur or be achieved) are not statements of historical fact and may be forward-looking information and are intended to identify forward-looking information. This forward-looking information is based on reasonable assumptions and estimates of management of the Company at the time such assumptions and estimates were made, and involves known and unknown risks, uncertainties and other factors which may cause the actual results, performance or achievements of Honey Badger Silver to be materially different from any future results, performance or achievements expressed or implied by such forward-looking information.
Such factors include, but are not limited to, risks relating to capital and operating costs varying significantly from estimates; delays in obtaining or failures to obtain required governmental, environmental or other project approvals; uncertainties relating to the availability and costs of financing needed in the future; changes in equity markets; inflation; fluctuations in commodity prices; delays in the development of projects; other risks involved in the mineral exploration and development industry; and those risks set out in the Company's public documents filed on SEDAR+ under Honey Badger Silver's issuer profile. Although the Company believes that the assumptions and factors used in preparing the forward-looking information in this news release are reasonable, undue reliance should not be placed on such information, which only applies as of the date of this news release, and no assurance can be given that such events will occur in the disclosed timeframes or at all. The Company disclaims any intention or obligation to update or revise any forward-looking information, whether as a result of new information, future events or otherwise, other than as required by law.
To view the source version of this press release, please visit https://www.newsfilecorp.com/release/312932
Southern Copper (SCCO) closed at $204.26 in the latest trading session, marking a +1.31% move from the prior day. The stock's performance was ahead of the S&P 500's daily gain of 0.46%. On the other hand, the Dow registered a gain of 0.56%, and the technology-centric Nasdaq increased by 0.45%.
Coming into today, shares of the miner had gained 3.31% in the past month. In that same time, the Basic Materials sector gained 12.62%, while the S&P 500 gained 2%.
Analysts and investors alike will be keeping a close eye on the performance of Southern Copper in its upcoming earnings disclosure. The company is expected to report EPS of $1.81, up 34.07% from the prior-year quarter. At the same time, our most recent consensus estimate is projecting a revenue of $4.13 billion, reflecting a 22.39% rise from the equivalent quarter last year.
For the entire fiscal year, the Zacks Consensus Estimates are projecting earnings of $7.61 per share and a revenue of $16.86 billion, representing changes of +45.23% and +25.6%, respectively, from the prior year.
Investors should also note any recent changes to analyst estimates for Southern Copper. These latest adjustments often mirror the shifting dynamics of short-term business patterns. Therefore, positive revisions in estimates convey analysts' confidence in the business performance and profit potential.
Our research shows that these estimate changes are directly correlated with near-term stock prices. To capitalize on this, we've crafted the Zacks Rank, a unique model that incorporates these estimate changes and offers a practical rating system.
The Zacks Rank system, stretching from #1 (Strong Buy) to #5 (Strong Sell), has a noteworthy track record of outperforming, validated by third-party audits, with stocks rated #1 producing an average annual return of +25% since the year 1988. Over the past month, the Zacks Consensus EPS estimate has shifted 0.29% downward. Currently, Southern Copper is carrying a Zacks Rank of #3 (Hold).
In terms of valuation, Southern Copper is presently being traded at a Forward P/E ratio of 26.5. This indicates a premium in contrast to its industry's Forward P/E of 26.13.
Also, we should mention that SCCO has a PEG ratio of 1.73. The PEG ratio bears resemblance to the frequently used P/E ratio, but this parameter also includes the company's expected earnings growth trajectory. The Mining – Non Ferrous industry had an average PEG ratio of 1 as trading concluded yesterday.
The Mining – Non Ferrous industry is part of the Basic Materials sector. With its current Zacks Industry Rank of 202, this industry ranks in the bottom 18% of all industries, numbering over 250.
The Zacks Industry Rank is ordered from best to worst in terms of the average Zacks Rank of the individual companies within each of these sectors. Our research shows that the top 50% rated industries outperform the bottom half by a factor of 2 to 1.
Remember to apply Zacks.com to follow these and more stock-moving metrics during the upcoming trading sessions.
Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Southern Copper Corporation (SCCO) : Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).
Merger terms put Teck Resources back in focus
Teck Resources (TSX:TECK.B) is back in the spotlight after outlining timing details for its proposed merger of equals with Anglo American and Anglo American's plan for a US$4.5b special dividend.
The merger headlines are landing after a strong run for Teck Resources, with the share price at CA$92.78 and a year to date share price return of 40.60% and a 1 year total shareholder return of 102.05%. Recent trading has been choppy, with the share price return down 6.26% over the past week but up 9.98% over the past month, which suggests momentum has cooled in the very short term even though longer term total shareholder returns, including the 214.16% total shareholder return over five years, remain robust.
Scan how Teck Resources compares to other miners with recent price strength and major corporate actions by reviewing our curated list of 9 top copper producer stocks.
After a steep multi year run and a recent pullback, Teck Resources now trades slightly above average analyst targets, yet still at a small intrinsic value discount. Is the market being too cautious, or not cautious enough?
Most Popular Narrative: 6.9% Overvalued
Teck Resources last traded at CA$92.78, compared with a widely followed narrative fair value of CA$86.76 that is built using an 8.30% discount rate.
Teck is progressing lower risk, high return copper growth projects (Zafranal, San Nicolas) that are well advanced in permitting and construction readiness. These offer near term expansion opportunities in stable jurisdictions and position the company to capture outsized volume growth and improved net margins versus industry peers.
Want to understand why Teck Resources earns a richer price tag in this narrative? The key is how future copper volumes, profitability, and required returns are stitched together. Curious which growth, margin, and valuation assumptions have to hold to support that fair value? The full narrative lays out the numbers that do the heavy lifting.
Result: Fair Value of CA$86.76 (OVERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
However, Teck Resources still faces meaningful risks, including potential project delays or cost overruns, and weaker copper or zinc prices that could quickly challenge this richer valuation narrative.
Find out about the key risks to this Teck Resources narrative.
Another View on Teck Resources' Valuation
The narrative fair value suggests Teck Resources is 6.9% overvalued at CA$92.78, yet the SWS DCF model points to an estimated future cash flow value of CA$97.97. That implies the stock trades at about a 5.3% discount. Which perspective do you think better reflects the risks around future copper and zinc cash flows?
For a closer look at how all those future cash flows are combined, check the full workings in the Look into how the SWS DCF model arrives at its fair value.
TECK.B Discounted Cash Flow as at Sep 2026
Next Steps
With mixed signals around Teck Resources and its merger plans, it makes sense to act promptly and test the story against hard data for yourself. To weigh both the risks and the potential upside in one place, start with the 2 key rewards and 1 important warning sign.
Looking for more Teck Resources sized investment ideas?
If you only stop at Teck Resources, you could miss other opportunities that fit your goals. Take a few minutes now to scan these focused stock ideas using the Simply Wall Street Screener.
- Target potential bargains by studying companies that screen as high quality yet priced below intrinsic value through the 10 high quality undervalued stocks.
- Strengthen your income stream by reviewing companies that offer over 5% yields in the 3 dividend fortresses.
- Prioritise resilience by checking companies with strong balance sheets and fundamentals in the list of solid balance sheet and fundamentals (12 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data
and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your
financial situation. We aim to bring you long-term focused analysis driven by fundamental data.
Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material.
Simply Wall St has no position in any stocks mentioned.
Companies discussed in this article include TECK-B.TO.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com
Teck Resources has delivered very strong share price gains over the past five years, yet the valuation checks suggest the stock now leans on the expensive side even though the intrinsic value estimate points to only a small discount to the current market price.
- Teck Resources has returned 214.2% over 5 years, which means anyone looking at the stock today is assessing it after a substantial re-rating by the market.
- Expectations for Teck Resources to keep converting its resource base into steady cash flow can support the current price, while any setback in cash generation or higher capital needs may weigh heavily on what investors are willing to pay.
- On a broad set of valuation checks Teck Resources scores 2 out of 6, which points to a stock that is not a clear bargain and screens as overvalued on market multiples even though the Discounted Cash Flow (DCF) estimate suggests it is fairly valued with a modest discount of about 5.3% to the current price.
The issue now is whether Teck Resources' recent re-rating leaves enough cushion in the current price for investors who are thinking about the stock at today's valuation levels.
Broaden your watchlist beyond Teck Resources by scanning our hand-picked 10 high quality undervalued stocks, which combine quality fundamentals with prices that still screen as attractive on Simply Wall St.
Is Teck Resources Fairly Priced on Cash Flow?
The Discounted Cash Flow (DCF) approach estimates what Teck Resources is worth based on the cash it is expected to generate for shareholders. For Teck Resources, the model starts with latest twelve month free cash flow of about CA$1.0b and assumes that cash generation continues to grow from this base over time.
On these assumptions, the DCF model points to an intrinsic value of around CA$97.97 per share. That sits only slightly above the current market price, which implies an estimated discount of about 5.3%. This suggests Teck Resources is not pricing in aggressive growth, yet the stock also does not screen as a deep bargain on cash flows alone.
Overall, the DCF workup indicates Teck Resources looks roughly fairly valued with only a small margin between intrinsic value and the current share price.
Teck Resources is fairly valued according to our Discounted Cash Flow (DCF), but this can change at a moment's notice. Track the value in your watchlist or portfolio and be alerted on when to act.
TECK.B Discounted Cash Flow as at Sep 2026
Has Teck Resources Run Too Far on Earnings?
The P/E ratio is a useful cross-check for Teck Resources because earnings are a key focus for investors in established materials companies. Teck Resources currently trades on a P/E of about 18.2x, which is slightly above the Metals and Mining industry average of roughly 17.5x and well below a broader peer average of around 30.3x.
A tailored fair P/E ratio for Teck Resources, which reflects its sector, size and risk profile, is estimated at about 12.3x. That is meaningfully lower than the current market multiple and indicates that, on this framework, investors are paying a premium to the earnings that the company is generating today. This contrasts with the DCF work, which pointed to only a small gap between intrinsic value and the share price.
On earnings multiples alone, Teck Resources screens as overvalued, with the current P/E sitting well above the fair ratio implied by its fundamentals.
TSX:TECK.B P/E Ratio as at Sep 2026
See what the numbers say about this price — find out in our valuation breakdown.
The Teck Resources Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Teck Resources valuation puzzle leaves off by spelling out which views on future growth, margins and earnings would need to play out for the stock to be worth materially more or less than it is today. Each one links its number to a specific view on how Teck Resources' growth, profitability and risks could evolve, which you can revisit over time as fresh information becomes available on the Community page.
Community views on Teck Resources are split between a copper led upside story and concern that a lot of that promise is already reflected in the price.
Bull case: 16% undervalued
"Teck's early leadership in low-carbon mining and digital traceability is positioning the company to capture price premiums and preferred access to emerging "green" metals supply chains…"
Read the full Bull Case to see why Teck Resources could be undervalued
Bear case: 7% overvalued
"Persistent operational delays and unforeseen technical challenges at major projects like QB2, including the ongoing TMF (Tailings Management Facility) issues and shiploader repairs, risk continued production shortfalls and increased costs…"
Read the full Bear Case to see why Teck Resources could be overvalued
Do you think there's more to the story for Teck Resources? Head over to our Community to see what others are saying!
The Bottom Line
For Teck Resources, the Discounted Cash Flow (DCF) work points to an intrinsic value only slightly above the current price, which suggests limited upside purely on cash flow assumptions. The P/E based view instead flags the stock as overvalued, since the current multiple runs ahead of the tailored fair ratio. That gap comes down to how confident you are that cash generation can support today’s valuation despite a weaker set of broader checks. The key question from here is whether Teck Resources can deliver the cash flow and execution that would justify the premium earnings multiple investors are currently paying.
This article by Simply Wall St is general in nature. We provide commentary based on historical data
and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your
financial situation. We aim to bring you long-term focused analysis driven by fundamental data.
Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material.
Simply Wall St has no position in any stocks mentioned.
Companies discussed in this article include TECK-B.TO.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com
VANCOUVER, British Columbia, Sept. 01, 2026 (GLOBE NEWSWIRE) — Teck Resources Limited (TSX: TECK.A and TECK.B, NYSE: TECK) (“Teck”) today provides the following information in connection with its proposed merger (the “Merger”) of equals with Anglo American plc (“Anglo American”).
Teck and Anglo American have agreed that the period between fulfilment (or waiver, as applicable) of the remaining non-Effective Date conditions precedent to the Merger, as described in the arrangement agreement (the “Arrangement Agreement”) dated September 9, 2025 between the parties and Teck’s circular dated November 3, 2025 (the “Meeting Circular”), and completion of the Merger will be eleven (11) trading days and the effective time of the Merger is expected to be 10:00 p.m. Vancouver time on the eleventh trading day.
Pursuant to the terms of the Arrangement Agreement, it is a condition precedent to the completion of the Merger that Anglo American declare a special dividend on its ordinary shares in the amount of approximately US$4.5 billion (the “Anglo Special Dividend”). Under the terms of the Arrangement Agreement, the Anglo Special Dividend is to be paid within 30 days of the effective date of the Merger (the “Effective Date”). Teck and Anglo American have instead agreed that the Anglo Special Dividend is to be paid within 45 days of the Effective Date.
Forward-Looking StatementsThis news release contains certain forward-looking information and forward-looking statements as defined in applicable securities laws (collectively referred to as forward-looking statements). These statements relate to future events or future performance. All statements other than statements of historical fact are forward-looking statements. The use of any of the words “anticipate”, “can”, “could”, “plan”, “expect”, “may”, “will”, “likely”, “should” and similar expressions is intended to identify forward-looking statements. These statements involve known and unknown risks, uncertainties and other factors that may cause actual results or events to differ materially from those anticipated in such forward-looking statements. These statements speak only as of the date of this news release. These forward-looking statements include, but are not limited to, timing of the payment of the Anglo Special Dividend.
These statements are based on a number of assumptions, including, but not limited to, assumptions regarding general business and economic conditions, future outlook and anticipated events, such as the ability of Anglo American and Teck to complete the Merger, the ability of Teck and Anglo American to obtain all required regulatory approvals, the ability of Teck and Anglo American to satisfy all other conditions to the Merger, the strategic vision of the merger between Teck and Anglo American following the closing of the Merger, the satisfaction of the conditions precedent to the Merger and other factors, many of which are beyond the control of Teck. The foregoing list of assumptions is not exhaustive. Events or circumstances could cause actual results to vary materially.
Forward-looking information is based on the information available at the time those statements are made and reflects the good faith belief of the officers and directors of Teck and Anglo American as of that time with respect to future events and is subject to risks and uncertainties that could cause actual results to differ materially from those expressed in the forward-looking information. Factors that may cause actual results to vary materially include, but are not limited to, the possibility that the Merger will not be completed on the terms and conditions, or on the timing, currently contemplated, and that it may not be completed at all, due to a failure to obtain or satisfy, in a timely manner or otherwise, required regulatory approvals and other conditions to the closing of the Merger or for other reasons, public perception of the Merger, market reaction to the Merger, the negative impact that the failure to complete the Merger for any reason could have on the business of Anglo American or Teck, the ability of Anglo American and Teck to successfully integrate and capture expected synergies, general economic and market conditions, including interest and foreign exchange rates, global financial markets, changes in government regulations or in securities, tax or other laws, industry competition, technological developments and other factors described or discussed in Anglo American’s or Teck’s disclosure materials filed with applicable securities regulatory authorities from time to time. For additional risk factors regarding Teck’s business see also “Risk Factors” in Teck’s current Annual Information Form dated February 19, 2026, as filed under Teck’s profile on SEDAR+ (www.sedarplus.ca) and on EDGAR (www.sec.gov).
Teck assumes no obligation to update forward-looking statements except as required under securities laws. Further information concerning risks, assumptions and uncertainties associated with these forward-looking statements, the Merger and Teck’s business can be found in the Meeting Circular filed under Teck’s profile on SEDAR+ (www.sedarplus.ca) and on EDGAR (www.sec.gov).
About TeckTeck is a leading Canadian resource company focused on responsibly providing metals essential to economic development and the energy transition. Teck has a portfolio of world-class copper and zinc operations across North and South America and an industry-leading copper growth pipeline. We are focused on creating value by advancing responsible growth and ensuring resilience built on a foundation of stakeholder trust. Headquartered in Vancouver, Canada, Teck’s shares are listed on the Toronto Stock Exchange under the symbols TECK.A and TECK.B and the New York Stock Exchange under the symbol TECK. Learn more about Teck at www.teck.com or follow @TeckResources.
Investor Contact:Edwin ShadeoActing Vice President, Investor Relations and Treasurer604.699.4531edwin.shadeo@teck.com
Media Contact:Dale SteevesDirector, External Communications236.987.7405 dale.steeves@teck.com
VANCOUVER, BC, Aug. 31, 2026 /CNW/ — (TSX: LUN) (Nasdaq Stockholm: LUMI) Lundin Mining Corporation ("Lundin Mining" or the "Company") reports the following updated share capital and voting rights, in accordance with the Swedish Financial Instruments Trading Act.
The number of issued and outstanding shares of the Company has increased by 44,794 to 851,337,385 common shares with voting rights as of August 31, 2026. The increase in the number of issued and outstanding shares from July 31, 2026 to date is a result of the exercise of employee stock options or the vesting of employee share units. During this period, the Company did not purchase any shares for cancelation under its Normal Course Issuer Bid program ("NCIB").
Normal Course Issuer Bid
Under the Company's shareholder distribution policy, the Company is committed to allocating up to US$150 million in annual share buybacks through the NCIB program. The Company's Board of Directors has also approved an increase of up to US$100 million to the share repurchase program for the remainder of 2026. So far during 2026, Lundin Mining has acquired 6,098,494 common shares at an average cost of approximately C$35.70/share.
About Lundin Mining
Lundin Mining is a Canadian mining company headquartered in Vancouver, Canada with three operating mines in Brazil and Chile. We produce metals that underpin global development, supporting infrastructure, electrification, technological innovation, and economic resilience. Our strategic vision is to become a top ten global copper producer. To get there, we are executing a clear growth strategy, which includes advancing one of the world's largest copper, gold, and silver projects in the Vicuña District on the border of Argentina and Chile, where we hold a 50% interest. We also hold a 31% interest in the Los Helados project, located adjacent to our operating Caserones mine, providing longer term growth optionality. Lundin Mining has a proven track record of value creation through resource growth, operational excellence, and responsible development. The Company's shares trade on the Toronto Stock Exchange (LUN) and Nasdaq Stockholm (LUMI). Learn more at www.lundinmining.com.
The information in this release pertaining to the updated share capital and voting rights is subject to the disclosure requirements of Lundin Mining under the Swedish Financial Instruments Trading Act. The information was submitted for publication, through the agency of the contact persons set out below on August 31, 2026 at 4:00 pm Pacific Time.
View original content to download multimedia: http://www.newswire.ca/en/releases/archive/August2026/31/c2515.html
Vancouver, British Columbia–(Newsfile Corp. – August 31, 2026) – Golden Arrow Resources Corporation (TSXV: GRG) (FSE: G6A) (OTCQB: GARWF), ("Golden Arrow" or the "Company") is pleased to announce that the Company has successfully completed the transaction announced on June 23, 2026, and has sold copper assets at the San Pietro Project ("Copper Assets") to Capstone Copper Corp. ("Capstone") and its wholly-owned subsidiary (the "Transaction"). The Transaction was approved by disinterested shareholders of the Company on August 21, 2026.
The full details of the Transaction were set out in our news release dated June 23, 2026. As consideration for the sale of the Copper Assets, New Golden Exploration Chile SpA ("NGE"), a joint venture indirectly owned by Golden Arrow (75.019%) and its joint venture partner, Sociedad de Servicios Andinos SPA (24.981%), received 2,200,012 common shares of Capstone (the "Capstone Shares") for a value of approximately US$25,000,000 (the "Consideration), calculated using the volume-weighted average closing price of Capstone's common shares for the 10 trading days ending two business days prior to closing, calculated on the Bank of Canada exchange rate two business days prior to closing. The approximate transaction costs and taxes payable for the Transaction are expected to be $6,550,000, with such fees being deducted from the Consideration received. New Golden Explorations Atlantida Ltd., a Golden Arrow subsidiary, received 1,666,914 Capstone Shares but had 165,042 Capstone Shares withheld for taxes payable in Chile, and 66,000 Capstone Shares deducted for the Advisory Fee (as defined below). Sociedad de Servicios Andinos SPA received 533,098 Capstone Shares.
"We are pleased to complete this transaction to unlock value from the San Pietro project. We now have a solid treasury that allows us to immediately expand our exploration efforts in Chile and Argentina, including planning the first drill program at our Atakama gold project this autumn. This closing marks a new chapter for the Company, and we look forward to building on this momentum to make our next discovery and deliver additional value to our shareholders," stated Nikolaos Cacos, Golden Arrow President & CEO.
As compensation for the services provided by Southern Cone Partners ("SCP") in connection with the Transaction, the Company paid a transaction fee equal to US$750,000 (the "Advisory Fee"), to SCP. The Advisory Fee was satisfied through the issuance of 66,000 Capstone Shares, which were deducted from the Consideration received by NGE. The entire Transaction was arm's length and no other finder's fees were paid.
About Golden Arrow:
Golden Arrow is a mineral exploration company with a successful track record of creating value by making precious and base metal discoveries and advancing them into exceptional deposits. Golden Arrow is actively exploring a portfolio of projects in Chile and Argentina. The Company is an affiliated company of the Grosso Group, a resource focused management organization that provides operational support to its affiliated companies as they advance quality resource projects.
ON BEHALF OF THE BOARD"Nikolaos Cacos" Mr. Nikolaos Cacos, President and CEO
For further information, please contact: Corporate CommunicationsTel: 1-604-687-1828 Toll-Free: 1-800-901-0058Email: info@goldenarrowresources.com
Neither the TSX-V nor its Regulation Services Provider (as that term is defined in policies of the TSX-V) accepts responsibility for the adequacy or accuracy of this release.
This news release may contain forward-looking statements. Forward-looking statements address future events and conditions and therefore involve inherent risks and uncertainties. All statements, other than statements of historical fact, that address activities, events or developments the Company believes, expects or anticipates will or may occur in the future, including, without limitation, statements about: Golden Arrow's plans for, and the future prospects of, its mineral properties; the approximate transaction costs and taxes payable for the Transaction; and the Company's business strategy, plans and outlooks and the future financial or operating performance of the Company are forward-looking statements.
Forward-looking statements are subject to a number of risks and uncertainties that may cause the actual results of the Company to differ materially from those discussed in the forward-looking statements and, even if such actual results are realized or substantially realized, there can be no assurance that they will have the expected consequences to, or effects on, the Company. Factors that could cause actual results or events to differ materially from current expectations include, among other things: risks associated with technical difficulties in connection with exploration activities; and the possibility that future exploration, development or mining results will not be consistent with the Company's expectations. Actual results may differ materially from those currently anticipated in such statements. Readers are encouraged to refer to the Company's public disclosure documents for a more detailed discussion of factors that may impact expected future results.
The forward-looking statements contained in this news release are made as of the date hereof and the Company does not undertake any obligation to update or revise any forward-looking statements except as required by applicable securities laws.
To view the source version of this press release, please visit https://www.newsfilecorp.com/release/312093
Southern Copper Corporation SCCO intends to invest $20.5 billion over the next decade to support its long-term outlook, with the bulk of the capital allocated to projects. Southern Copper has also reaffirmed its dedication to collaborating with Peru's government to drive economic and social progress. This will be achieved by advancing the company’s Peruvian projects, Tía María, Los Chancas, and Michiquillay, which represent a total investment of $10.3 billion.SCCO expects to spend $1.8 billion on the Tia Maria project located in the Peruvian region of Arequipa, which is designed to produce 120,000 tons of copper cathodes per year. As of June 30, 2026, the project was 42% complete, with $693 million invested and $1.10 billion committed. The company targets start-up for the second half of 2027.The company expects to invest $2.6 billion in the Los Chancas, which is expected to produce 130,000 tons of copper and 7,500 tons of molybdenum annually from 2031. Michiquillay requires $2.5 billion in investment and expects to produce 225,000 tons of copper annually from 2032 over an initial mine life exceeding 25 years.In Mexico, El Pilar is moving toward early site work in September 2026 and construction in the first quarter of 2027, with production targeted for the second half of 2029. The project is designed for 36,000 tons of annual copper cathode output. These projects give Southern Copper multiple sources of organic production growth beyond current mine grades. These developments help reach tangible milestones for the company’s broader expansion program across both operating countries over time. Southern Copper maintains a strong long-term outlook with production expected to increase to 1.6 million tons by 2033 or 2034.
Project Updates of Southern Copper Peers
Freeport-McMoRan Inc. FCX completed the evaluation of a large-scale expansion at El Abra in Chile to define a large sulfide resource that could potentially support a major mill project similar to the large-scale concentrator at Cerro Verde, with an estimated resource of 20 billion recoverable pounds of copper. Freeport-McMoRan expects the expansion to result in the addition of more than 700 million pounds of copper production annually.Freeport-McMoRan has a strong liquidity profile and generates substantial cash flows, providing ample flexibility to fund expansion projects, reduce debt and enhance shareholder returns. BHP Group Limited BHP has copper projects under execution and a pipeline that could deliver around two Mtpa of attributable copper production by the 2030s. BHP Group is planning an Escondida New Concentrator project with a potential $4.4-$5.9-billion investment to replace the aging Los Colorados plant. BHP Group has approved a pre-commitment funding of $0.5 billion (BHP’s share) for the concentrator, which is expected to have a higher production capacity and add 230-270 kt of copper annually.
SCCO’s Price Performance, Valuations & Estimates
Southern Copper shares have skyrocketed 123.3% year to date compared with the Zacks Mining – Non-Ferrous industry’s surge of 82.4%. During this time, the Basic Materials sector has risen 34.6% and the S&P 500 has rallied 23%.
Image Source: Zacks Investment Research
The Southern Copper stock is currently trading at a forward 12-month earnings multiple of 29.17X, which is a premium to the industry average of 24.84X.
Image Source: Zacks Investment Research
The Zacks Consensus Estimate for Southern Copper’s 2026 sales is $16.86 billion, indicating a 25.6% year-over-year jump. The consensus mark for the year’s earnings is pegged at $7.61 per share, suggesting a rally of 45.2%.
The Zacks Consensus Estimate for 2027 sales implies an 11.7% year-over-year dip. The same for earnings suggests a fall of 8.2%.Earnings estimates for 2026 have moved 0.1% south over the past 60 days, while the same for 2027 have moved up 0.3% over the past 60 days.
Image Source: Zacks Investment Research
The company currently carries a Zacks Rank #3 (Hold). You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Southern Copper Corporation (SCCO) : Free Stock Analysis Report
Freeport-McMoRan Inc. (FCX) : Free Stock Analysis Report
BHP Group Limited Sponsored ADR (BHP) : Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).
Monday U.S. Featured Earnings
Science Applications International Corp (NASDAQ: SAIC) (Q2) EPS of $2.25, compared to $3.63 in the prior-year quarter.
Canada Featured Earnings
CHAR Technologies Ltd. (V.YES) (Q2) EPS for gain of half a cent, compared to loss of two cents in the prior-year quarter.
Goldsky Resources Corp. (V.GSKR) (Q2) EPS for loss of four cents, compared to loss of 16 cents in the prior-year quarter
Ucore Rare Metals Inc. (V.UCU) (Q2) EPS for loss of 3.5 cents, compared to loss of five cents in the prior-year quarter.
Tuesday
U.S. Economic Lookahead
US Manufacturing PMI (Aug.)
ISM Report on Business Manufacturing PMI (Aug.)
Construction Spending (July)
Job Openings & Labor Turnover Survey (July)
U.S. Featured Earnings
Palo Alto Networks Inc (NASDAQ: PANW) (Q4) EPS of 51 cents compared to 42 cents in the prior-year quarter
Dell Technologies Inc. (NYSE:DELL) (Q2) EPS of $4.63, compared to $2.10 in the prior-year quarter
Medtronic plc. (NYSE:MDT) (Q2) EPS of $1.38, compared to $1.26 in the prior-year quarter
Canada Economic Lookahead
S&P Global Canada Manufacturing PMI (Aug.) The index rose to 53.5 in July from 52.2 in June and 53 in July 2025.
Canada Featured Earnings
Hydreight Technologies Inc (V.NURS) (Q2) EPS of 5.5 cents, compared to five cents in the prior-year quarter
Zoomd Technologies Ltd. (V.ZOMD) (Q2) EPS of two cents, compared to breakeven in the prior-year quarter.
Wednesday
U.S. Economic Lookahead
ADP National Employment Report (Aug.)
Factory Orders (July)
Federal Reserve Beige Book
U.S. Featured Earnings
Broadcom Inc. (NASDAQ:AVGO) (Q2) EPS of $2.83, compared to $1.26 in the prior-year quarter
Snowflake Inc. (NYSE:SNOW) (Q2) EPS for loss of 51 cents, compared to loss of 80 cents in the prior-year quarter
Hewlett Packard Enterprise Company (NYSE:HPE) (Q3) EPS of 81 cents, compared to 35 cents in the prior-year quarter.
Canada Featured Earnings
Read:
- Gold Is at Record Highs and the Money Is Chasing the Drill Bit. This Junior Just Aimed Eight Holes at an Untested Brazilian Gold Core
- The Abitibi Belt's Next Gold Story May Already Be in the Ground. This Silver Miner Just Started Looking.
- Greenland Mines Lands a Site Team at Sarfartoq Within Days of Signing, Setting Up a 2026 Rare Earth Field Program
- Quantum Secure Encryption Scales Commercial Deployment as U.S. Pours Billions Into Quantum Computing
- The $1 Trillion Data Problem Quantum Computing Is About to Make Worse
Dye & Durham Ltd. (T. DND) (Q4) EPS of $2.24, compared to $2.03 in the prior-year quarter.
MAJOR DRILLING GRP (T.MDI) (Q1) EPS for 19 cents, compared to 10 cents in the prior-year quarter.
VersaBank (T.VBNK) (Q3) EPS of 41 cents, compared to 39 cents in the prior-year quarter.
Thursday
U.S. Economic Lookahead
Initial jobless claims (August 29)
U.S. Trade Balance (July)
US Services PMI (Aug.)
U.S. Featured Earnings
Ciena Corporation (NYSE:CIEN) (Q2) EPS of $1.45, compared to 41 cents in the prior-year quarter.
Copart, Inc. (NASDAQ:CPRT) (Q4) EPS of 39 cents, compared to 41 cents in the prior-year quarter.
Zscaler, Inc. (NASDAQ:ZS) (Q4) EPS for gain of six cents, compared to loss of four cents in the prior-year quarter
Canada Economic Lookahead
Canadian international merchandise trade (July) In June, Canada's merchandise exports increased 0.4%, while imports edged up 0.2%. As a result, Canada's merchandise trade surplus with the world widened slightly from $3.7 billion in May to $3.9 billion in June.
Canada Featured Earnings
BRP Inc (T.DOO) (Q2) EPS for loss of 64 cents, compared to gain of $1.83 in the prior-year quarter
Enghouse Systems Ltd (T.ENGH) (Q3) EPS of 33 cents, compared to 30 cents in the prior-year quarter
Tecsys Inc. (T.TCS) (Q1) EPS gain of 11 cents, compared to loss of two cents in the prior-year quarter
Friday
U.S. Economic Lookahead
Employment Report (Aug.)
U.S. Featured Earnings
KNOT Offshore Partners LP (NYSE:KNOP) (Q2) EPS for loss of three cents, $3.67, compared to gain of 20 cents in the prior-year quarter
Canada Economic Lookahead
Labour Force Survey (Aug.) Employment increased by 75,000 (+0.4%) in July and the employment rate rose 0.1 percentage points to 60.9%. The unemployment rate declined 0.1 percentage points to 6.4%
NexGen Energy Ltd. (NYSE:NXE) is making waves after CEO Leigh Curyer revealed active talks with mining giant BHP Group Limited (NYSE:BHP) on August 17 regarding a potential equity stake and financing for its flagship Rook I project in Saskatchewan. Having just broken ground on construction for what is slated to be one of the world's largest, lowest-cost uranium mines, NexGen is seeking to raise $1 billion in capital over the next nine months through prepayments, debt, or direct equity. The partnership discussion underscores growing institutional interest, but a side-by-side look at the financial health of both companies shows two fundamentally different investment propositions.
n Photo from PBF Energy LinkedInnFinancial Performance Comparison: High-Growth Pure Play vs. Cash-Flow Powerhousen
NexGen Energy Ltd. (NYSE:NXE) represents a development-stage uranium exploration and development company with no commercial mining revenue. In Q2 2026, NexGen posted a net income of $74.55 million CAD (driven primarily by a non-cash mark-to-market gain of $96.47 million CAD on its convertible debentures), reversing a net loss of $86.69 million CAD in Q2 2025. The company maintains significant liquidity, holding $756.17 million CAD in cash alongside $214.08 million CAD in short-term investments as of June 30, 2026, for total cash and short-term investments of $970.25 million CAD. While its absence of operational revenues makes standard earnings metrics non-applicable, its asset backing and project economics remain compelling.
n
In stark contrast, BHP Group Limited (NYSE:BHP) delivered a record operational year in FY2026, showcasing massive profitability across its global operations. BHP reported underlying EBITDA of $33 billion, up 27% year-over-year, achieving an overall margin of nearly 60%, driven by a record 70% margin in its copper business. Free cash flow surged 83% to $9.8 billion, allowing BHP to distribute a total annual dividend of $1.72 per share ($8.7 billion total) at a robust 66% payout ratio. BHP also slashed net debt to below $9 billion, more than $4 billion lower than the previous year, giving it huge financial flexibility to self-fund its $11 billion annual capex pipeline. Financially, BHP is far superior in stability, balance sheet strength, and immediate cash generation, whereas NexGen's value relies entirely on future execution.
nBull and Bear Casesn
NexGen Energy’s bull case is centered on the successful construction of its Rook I project, which could give the company control over up to 20% of global primary uranium supply. Securing an equity partner such as BHP or obtaining utility prepayments could also help close its approximately $1 billion funding gap and significantly reduce project financing risk. However, the bear case is driven by the risks inherent in large-scale mining projects in remote northern regions, including unexpected capital cost overruns, construction delays, and regulatory hurdles. Additional equity raises could also dilute existing shareholders before the mine begins production.
n
BHP Group’s bull case is supported by its diversified portfolio, industry-leading cost control, and dominant position in copper, with unit costs declining 6%. Its ability to self-fund copper expansion positions the company to benefit from long-term electrification and energy-transition demand. On the downside, BHP remains exposed to global economic cycles and fluctuations in iron ore and steelmaking coal prices. A slowdown in global industrial activity could therefore pressure commodity prices and weigh on the company’s top-line growth.
nInsider Monkey's Hedge Fund Data Analysisn
Hedge fund positioning showed modest shifts across NexGen Energy and BHP Group in Q1 2026. NexGen Energy had 36 hedge fund holders, compared with 37 in Q4 2025. Among its major holders, Millennium Management, led by Israel Englander, held 3,518,448 shares valued at approximately $32.99 million, reducing its position by 38%. Kingdon Capital, led by Mark Kingdon, held 2.5 million shares worth approximately $23.47 million, increasing its position by 2.4%.
n
BHP Group saw somewhat stronger institutional participation, with hedge fund holders increasing from 29 to 31. Fisher Asset Management, led by Ken Fisher, held 24,341,120 shares valued at approximately $2.02 billion, representing a 2% increase. Citadel Investment Group, led by Ken Griffin, held 943,100 call shares valued at approximately $78.57 million, while reducing its position by 24%.
nConclusion: What Investors Should Watch Nextn
Investors comparing these two mining entities are choosing between immediate cash-generating stability and high-upside project development. Moving forward, the key catalyst to watch for NexGen Energy Ltd. (NYSE:NXE) is whether its strategic negotiations with BHP crystallize into a formal equity partnership or project-level investment over the next nine months. For BHP Group Limited (NYSE:BHP), investors should monitor execution on its medium-term $11 billion capex plan and track whether copper remains a strong margin driver in FY2027.
n
n
While we acknowledge the potential of BHP as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
n
n
n
READ NEXT: 33 Stocks That Should Double in 3 Years and 15 Stocks That Will Make You Rich in 10 Years
n
Disclosure: None. Follow Insider Monkey on Google News.
n
Freeport-McMoRan Inc. FCX and BHP Group Limited BHP are two heavyweights in the copper mining industry. Both are navigating fluctuating copper prices and global economic uncertainties. Copper prices continue to show strength driven by robust demand from China and the United States. Structural tailwinds, including electric vehicles (EVs), renewable energy projects, artificial intelligence data center growth and grid modernization, continue to boost copper consumption. Worries about tightening supply amid rising EV and infrastructure demand aided the red metal. Copper surged to an all-time high near $6.9 per pound earlier this month on supply tightness and demand strength. Supply risks stemming from operational issues in top producer Chile, along with export bans on copper concentrates from the Democratic Republic of Congo, supported the price rally. Imports to the United States have also surged ahead of a potential tariff announcement by the Trump administration. Copper prices are currently hovering near $6.6 per pound. Let’s dive deep and closely compare the fundamentals of these two copper giants to determine which one is a better investment option now.
The Case for Freeport
Freeport continues to leverage its portfolio of high-quality copper assets, emphasizing disciplined execution and organic growth initiatives to strengthen its production profile. FCX has completed the evaluation of a large-scale expansion at El Abra in Chile to define a large sulfide resource that could potentially support a major mill project similar to the large-scale concentrator at Cerro Verde, with an estimated resource of approximately 20 billion recoverable pounds of copper. The expansion is expected to result in the addition of more than 700 million pounds of copper production annually. In Arizona, FCX is progressing with pre-feasibility studies at its Safford/Lone Star operations, with completion targeted for 2026, to assess a sizable sulfide expansion opportunity. It has expansion opportunities at Bagdad in Arizona that can more than double the concentrator capacity of the operation. Technical and economic studies have revealed the potential to build concentrating facilities to boost copper production by 200-250 million pounds annually. PT Freeport Indonesia (PT-FI) is developing the Kucing Liar ore body within the Grasberg district with a targeted ramp-up to commence in 2030. Studies completed by FCX in 2025 show an opportunity to increase Kucing Liar’s design capacity to 130,000 metric tons of ore per day and reserves by roughly 20% at low costs. FCX has a strong liquidity profile and generates substantial cash flows, providing ample flexibility to fund expansion projects, reduce debt and enhance shareholder returns. It generated solid operating cash flows of $5.6 billion in 2025. Cash flows provided by operations were around $2 billion in the second quarter of 2026. Freeport ended the second quarter with strong liquidity, including $4.1 billion in cash and cash equivalents, $3 billion in availability under the Freeport revolving credit facility, and $1.5 billion in availability under the PT-FI credit facility.At the end of the second quarter, Freeport had a net debt of $2.1 billion, excluding PTFI’s new downstream processing facilities. Its net debt is below its targeted range of $3-$4 billion. Freeport has a policy of distributing 50% of the available cash to its shareholders and the balance to either reduce debt or invest in growth projects. FCX has no significant debt maturities until 2027. FCX offers a dividend yield of roughly 0.4% at the current stock price. Its payout ratio is 13% (a ratio below 60% is a good indicator that the dividend will be sustainable). Backed by strong financial health, the company's dividend is perceived to be safe and reliable.Freeport faces headwinds from higher costs. Its second-quarter unit net cash costs jumped 74% year over year to $1.97 per pound due to lower copper volumes. Freeport expects unit net cash costs of $2 per pound for the third quarter, while projecting a full-year average of roughly $1.9 (compared with $1.65 in 2025). The projected third-quarter unit cost reflects a roughly 43% year-over-year increase. The uptick in costs reflects higher costs of energy and other consumables due to the Middle East conflict and persistent pressure on volumes. Higher costs are expected to weigh on the company's margins. Freeport’s copper sales volumes tumbled approximately 30% year over year in the second quarter to 710 million pounds. The downside primarily resulted from lower operating rates during the phased ramp-up of the Grasberg Block Cave mine in Indonesia following the mud rush incident in September 2025. While the company’s third-quarter outlook for copper sales volumes of 750 million pounds indicates a sequential improvement, it suggests a 23% year-over-year decline. The company, in April 2026, lowered its consolidated sales volume projections for full-year 2026 to around 3.1 billion pounds of copper from the prior view of 3.4 billion pounds due to an expected delay in achieving full ramp-up of the Grasberg Block Cave mine. Lower sales volumes are expected to weigh on its top line.
The Case for BHP
BHP continues to reshape its portfolio toward commodities such as copper and potash, allocating a meaningful portion of its medium-term capital expenditure to these areas. This strategy positions the company to benefit from decarbonization, electrification, population growth and rising living standards in emerging markets. It is also making operations more efficient on the back of smart technology adoption across the entire value chain. Fiscal 2026 copper production was 1,952.8 kt, within the company’s 1,900-2,000 kt guidance range, despite planned lower grades at Escondida and ore complexity at Spence. Escondida produced 1,261.2 kt, while Antamina output rose 27% to a record 151.5 kt and Copper South Australia delivered 320.7 kt. BHP’s fiscal 2027 copper guidance of 1,650-1,800 kt points to a near-term volume reset, but the longer-term pipeline remains intact. BHP has copper projects under execution and a pipeline that could deliver around two Mtpa of attributable copper production by the 2030s. It is planning an Escondida New Concentrator project with a potential $4.4-$5.9 billion investment to replace the aging Los Colorados plant. BHP has approved a pre-commitment funding of $0.5 billion (BHP’s share) for the concentrator, which is expected to have a higher production capacity and add 230-270 kt of copper annually.Resolution Copper, a joint venture owned by BHP (45%) and Rio Tinto (55%), completed a land exchange in Arizona. This enables the next phase of technical work and development planning for the Resolution Copper project, which is one of the most significant undeveloped copper resources in the United States.
The company’s balance sheet remains strong with cash and cash equivalents of $18.5 billion at the end of fiscal 2026. BHP also ended fiscal 2026 with net debt of $8.7 billion, down from $12.9 billion in fiscal 2025 and below its $10-$20 billion target range.BHP’s net operating cash flow increased 17% year over year to $21.8 billion in fiscal 2026, partly driven by higher realized prices and cost management. Free cash flow surged 83% to $9.8 billion, after spending $10.3 billion on capital and exploration projects. BHP remains committed to driving shareholder value, having determined a final dividend of $5 billion, leading to total returns to its shareholders of $8.7 billion for the year. Since the introduction of its capital allocation framework in 2016, BHP has delivered more than $115 billion to its shareholders. BHP offers a dividend yield of roughly 2.9% at the current stock price.
FCX & BHP: Price Performance, Valuation & Other Comparisons
FCX stock has rallied 78% over the past year, while BHP has gained 71.6%.
Image Source: Zacks Investment Research
FCX is currently trading at a forward 12-month earnings multiple of 23.21. BHP is currently trading at a forward 12-month earnings multiple of 18.99, below FCX.
Image Source: Zacks Investment Research
BHP’s return on equity of 21.6% is higher than FCX’s 10.6%. This reflects BHP’s efficient use of shareholder funds in generating profits.
Image Source: Zacks Investment Research
How the Zacks Consensus Estimate Compares for FCX & BHP
The Zacks Consensus Estimate for FCX’s 2026 sales and EPS implies a year-over-year rise of 10.2% and 57.6%, respectively. The EPS estimates for 2026 have been going up over the past 60 days.
Image Source: Zacks Investment Research
The consensus estimate for BHP’s current fiscal year sales implies a year-over-year rise of 10.1%. The same for EPS suggests a 5.9% year-over-year increase. The EPS estimates for the current fiscal year have been going south over the past 60 days.
Image Source: Zacks Investment Research
FCX or BHP: Which Is the Better Pick?
Both FCX and BHP currently carry a Zacks Rank #3 (Hold), so picking one stock is not easy. You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.Both Freeport and BHP present compelling investment cases. FCX is poised to gain from progress in expansion activities that will boost production capacity. Robust financial health allows FCX to invest in growth projects and drive shareholder value. Strong cash generation, investment in growth projects and higher operational efficacy, aided by the adoption of technology, bode well for BHP Group. BHP appears to have an edge over FCX due to its more attractive valuation. BHP’s higher ROE also indicates that it is more effectively utilizing shareholder funds. Investors seeking exposure to the copper mining space might consider BHP to be the more favorable option at this time.
Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Freeport-McMoRan Inc. (FCX) : Free Stock Analysis Report
BHP Group Limited Sponsored ADR (BHP) : Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).
Global demand tied to AI related investment is shaping trade and capital flows, and that is putting growth companies with clear earnings ambitions back in focus. Investors are searching for businesses that can convert this demand into real revenue, and management teams that are confident enough to back their own outlook with meaningful share ownership. This article walks through three fast growing stocks with high insider ownership that fit that brief.
The three stocks below are just a starting sample, and the full screen on Simply Wall St surfaces 102 more companies with similarly compelling growth and insider ownership stories that are not covered here. To identify and analyze the opportunities that best fit your own criteria, head straight to the Fast Growing Stocks With High Insider Ownership screener.
PDI Gold is a West Africa focused gold company developing and operating mines, with the Kiniéro Gold Project in Guinea as its flagship 398 km² exploration to development asset. The company also has interests in the Bankan Gold Project in Guinea and the Nampala Gold Mine in Mali, which add further optionality if development and operations progress as planned. PDI Gold currently has a market cap of about A$4.4b.
Investors watching the Fast Growing Stocks With High Insider Ownership theme may see PDI Gold as a pure play on the Kiniéro build out, where ramping production, a large resource and active exploration all sit behind analyst forecasts for future revenue and earnings. At the same time, the story involves meaningful risk. The company is still loss making, has less than a year of cash runway and relies on external funding while it waits on key permits in Guinea and manages country risk in Mali. If execution, financing and permitting are successfully managed, the combination of growth potential and insider alignment at PDI Gold may appeal to investors who are comfortable with higher risk, development stage exposure.
High risk growth at PDI Gold can look exciting when insiders are heavily invested and a flagship project anchors the story. Before taking a view, it helps to see the 2 key rewards and 3 important warning signs investors often miss in the 2 key rewards and 3 important warning signs (2 are major!)
ASX:PDI Earnings & Revenue Growth as at Aug 2026 Telix Pharmaceuticals (ASX:TLX)
Telix Pharmaceuticals develops and sells radiopharmaceutical products that help doctors image and treat cancers. Its Precision Medicine and Therapeutics pipeline, including TLX591 for advanced prostate cancer, ties it closely to the fast growing theme in this screener. The business is already commercial, with about US$704.7 million of revenue from Precision Medicine and US$277.1 million from Manufacturing Solutions, and additional internal adjustments between segments. Telix Pharmaceuticals currently has a market cap of about A$5.3b.
Investors watching fast growing stocks with high insider commitment may view Telix Pharmaceuticals as a way to get exposure to cancer imaging and treatment products that are already generating revenue, while still having a pipeline that could change the scale of the business if key trials and approvals progress as expected. H1 2026 revenue of US$477 million, Q2 revenue growth of 22% and EBITDA of US$52 million show that Illuccix, Gozellix and manufacturing are already meaningful, and recent trial progress on TLX591 and TLX250 plus the Regeneron partnership add further optionality. The flip side is real risk around high R&D spend, debt and cash flow pressure, regulatory reviews and pricing competition. This combination means Telix can potentially reward patient investors if things go right, but also demands a high tolerance for volatility and clinical setbacks.
Telix Pharmaceuticals is already generating hundreds of millions in revenue, yet the real inflection might still be ahead. Get the full story, including key trial and balance sheet pressure risks, in the analysis report for Telix Pharmaceuticals
ASX:TLX Earnings & Revenue Growth as at Aug 2026 Lindian Resources (ASX:LIN)
Lindian Resources is a Perth based explorer focused on gold, bauxite and rare earth elements across Tanzania, Guinea, Malawi, Australia and Singapore, with the Kangankunde Rare Earths project in Malawi as its flagship and clearest link to fast growing demand for rare earths in clean energy and tech supply chains. As an exploration and development stage company, Lindian is not yet reporting segment level revenue, so the investment story is built around future production potential rather than current sales. The stock currently has a market cap of about A$1.4b.
Lindian Resources gives you pure exposure to a rare earths story that is already moving from drill results toward planned production, with Kangankunde in Malawi and a processing route through the SARECO facility in Kazakhstan both targeting Q4 2026. Forecast revenue growth of around 138.8% a year and an expected shift into profitability within three years show why the market is paying up for this growth profile, even with a rich P/B multiple. The trade off is real. The company is still loss making, relies on external funding, has diluted shareholders recently and faces execution risk on commissioning, processing and sales. For investors comfortable with higher risk growth stories, that mix of potential and uncertainty is exactly where deeper research on Lindian may start to get interesting.
Accelerating rare earths potential at Lindian Resources is only half the picture. The real question is how that growth profile lines up against what analysts expect next. See how the story stacks up in the analyst forecasts for Lindian Resources
ASX:LIN Earnings & Revenue Growth as at Aug 2026 Seeking Alternatives Before The Crowd Moves
Fresh ideas move first and the strongest stories often break out while most investors are still watching old winners. Do not get caught chasing. Scan new momentum while it matters and get in early.
- Spot companies building early leadership in digital assets and payments by reviewing the curated 21 cryptocurrency and blockchain stocks before the market focus shifts and valuations adjust.
- Track infrastructure stocks that could be affected if AI demand reshapes data and power needs by scanning the focused 55 AI infrastructure stocks while they are still under the radar.
- Zero in on metals producers involved in electrification with a hand picked 9 top copper producer stocks that highlights miners aligned with grid and technology build outs.
This article by Simply Wall St is general in nature. We provide commentary based on historical data
and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your
financial situation. We aim to bring you long-term focused analysis driven by fundamental data.
Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material.
Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com
Melbourne, Australia and Vancouver, British Columbia–(Newsfile Corp. – August 27, 2026) – Mithril Silver and Gold Limited (TSXV: MSG) (ASX: MTH) (OTCQB: MTIRF) ("Mithril" or the "Company") is pleased to provide details of significant progress at Mithril's district scale Copalquin property, Durango State, Mexico.
Drilling Highlights
-
Recent drilling at the historic Copalquin Mine area at Target 4 has returned wide, high-grade, and near surface silver and gold mineralisation, with substantially elevated silver values,
-
Mineralisation intercepted by drilling across the combined Copalquin-Zaragoza corridor now extended to a strike length of 550 metres and 200 metres vertically
-
Projected vein remains untested 400 m to the northwest towards Target 1 (Refugio) and 600 m to the southeast towards Target 4 (San Manuel):
- 11.70 m @ 456 g/t AgEq1 (1.06 g/t gold, and 381 g/t silver) from 22.0 m (CO26-001), including3.40 m @ 1,239 g/t AgEq (2.72 g/t gold, and 1049 g/t silver) from 28.4 m, and including0.60 m @ 3,877 g/t AgEq (4.81 g/t gold, and 3,540 g/t silver) from 31.2 m.
- 13.95 m @ 387 g/t AgEq (1.76 g/t gold, and 264 g/t silver) from 88.85 m (CO26-002), including1.00 m @ 1,747 g/t AgEq (7.03 g/t gold, and 1,255 g/t silver) from 97 m.
- 6.50 m @ 320 g/t AgEq (0.22 g/t gold, and 305 g/t silver) from 93.4 m (CO26-003), including0.80 m @ 1,890 g/t AgEq (1.07 g/t gold, and 1,815 g/t) silver from 97 m.
This latest drilling includes higher silver grades and builds on successful results from June 2024 when the first drill holes in this area returned intercepts, including 5.66 m with 2.58 g/t gold, 230 g/t silver from 18.5 m in drill hole CDH-1522. At the time, the geology of the area was not well understood. With the benefit of this new drilling, combined with the high-grade results further along strike at Zaragoza, including 0.57 m with 6.40 g/t gold, 4,400 g/t silver from 342.4 m in drill hole MTH-ZG25-373, the Company is working to determine grade continuity within the Copalquin-Zaragoza Structure, which has a potential total strike length of 1.5 km (see Figure 1).
Drilling has now confirmed mineralisation over approximately 550 metres of strike length and remains open for potential expansion both along strike and dip (see Figure 2). This growing zone is interpreted to form part of the Copalquin-Zaragoza Structure, a major northwest-trending geological feature that may connect El Refugio at Target 1 with the historical San Manuel workings at Target 4 across the valley to the southeast.
"These results represent an important step forward in our progress at the historic Copalquin Mine area within this large, high-grade gold-silver system. What began as an area with limited geological understanding has progressed with potential to be a substantial, high-grade mineralised corridor, with drilling demonstrating strong gold and silver mineralisation over a substantial strike length and across multiple levels," said John Skeet, Managing Director and CEO. "The combination of these broad mineralised intervals with significant high-grade intercepts at the Copalquin mine area and our results further along strike at Zaragoza is particularly positive. We are seeing how these discoveries potentially align within the larger Copalquin-Zaragoza Structure and connecting several historical mining areas across the district. Drilling has recommenced at Target 4 to test the structure to the southeast."
Figure 1: Target 1 plan map showing drill hole trace locations, highlight intercepts in this announcement and resource footprint area
To view an enhanced version of this graphic, please visit:https://images.newsfilecorp.com/files/11657/311734_974ba0de1441f90c_001full.jpg
Figure 2: Long section view of the El Refugio vein looking perpendicular to vein to the northeast
To view an enhanced version of this graphic, please visit:https://images.newsfilecorp.com/files/11657/311734_974ba0de1441f90c_002full.jpg
ABOUT THE COPALQUIN AND LA DURA GOLD SILVER PROPERTIES
Mithril is undertaking an aggressive exploration program in 2026, with 25,000 metres of drilling planned during the year across the Copalquin District. Work in the second half of 2026 is focussing on expanding known mineralised zones, testing new high-priority targets, integrating district-wide geophysical data, and continuing to advance the Company's district-scale exploration thesis. There are 13 target areas with 6 of that advancing as high-priority and including the recently upgraded resource at Target 14. The district features over 100 historic underground workings including several notable past-producing multi-level mines and small 200 surface workings (c.1850 – 1910). Mapping and sampling across the lower half of the 70 km2 mining concession area demonstrates and a large epithermal silver-gold system with multiple target areas for potential resource growth plus the conduit system responsible for the widespread silver and gold mineralisation. Of note, are the persistent and widespread high gold grades, sampled across this silver district.
Figure 3: Mithril's Copalquin and La Dura property locations in Durango State, Mexico
To view an enhanced version of this graphic, please visit:https://images.newsfilecorp.com/files/11657/311734_mithrilthree.jpg
The northern half of the Copalquin concession area features large areas of alteration. The LiDAR image shows evidence of historic mining activity and indicates some key structures. Along with historic sampling data, the northern section of the property presents as a potentially significant large exploration area within Mithril's Copalquin mining concessions.
Mithril has an exclusive option to purchase 100% interest in the Copalquin mining concessions by paying US$10M on or any time before 7 August 2028.
The nearby 20 km2 La Dura property has recently been added to the portfolio providing a brown field property with a database of mapping, sampling and drilling5. The recent LiDAR survey6 has revealed multiple historic workings within the concession area, including the 4-level high-grade La Dura mine. An initial 1.5 km long mineralisation corridor has been identified as a future drill target. An aerial magnetic survey has been complete with interpretation work currently progressing.
Figure 4: LiDAR identified historic workings across the 70km2 district. Current drilling locations at Target 3 and Target 4 with ongoing mapping and sampling.
To view an enhanced version of this graphic, please visit:https://images.newsfilecorp.com/files/11657/311734_974ba0de1441f90c_005full.jpg
Figure 5: Property-wide channel sampling results for the middle and south district sections within ~50% of the 70 km2 mining concession area covering the Copalquin District. An aerial magnetic survey and a desktop structural study have been completed over the area and are being interpreted to support drill planning for district defining targets such as the current drilling along the Copalquin Structure.
To view an enhanced version of this graphic, please visit:https://images.newsfilecorp.com/files/11657/311734_974ba0de1441f90c_006full.jpg
Drilling Program Discussion
Table 1: Recent significant results received for Target 1 resource upgrade drilling
| Hole ID | From (m) | To (m) | Length (m) | Au g/t | Ag g/t | AuEq g/t7 | AgEq g/t8 | Cu % | Pb % | Zn % |
| Target 1 | ||||||||||
| LS26-008 | 30.40 | 43.85 | 13.45 | 1.55 | 16.6 | 1.78 | 125 | 0.01 | 0.00 | 0.01 |
| including* | 41.20 | 41.70 | 0.50 | 27.90 | 156.0 | 30.13 | 2109 | 0.00 | 0.00 | 0.00 |
| LS26-008 | 87.35 | 87.85 | 0.50 | 0.85 | 8.2 | 0.97 | 68 | 0.00 | 0.00 | 0.01 |
| LS26-009 | 82.20 | 82.80 | 0.60 | 1.29 | 3.2 | 1.33 | 93 | 0.01 | 0.00 | 0.01 |
| LS26-009 | 125.30 | 126.80 | 1.50 | 0.91 | 70.3 | 1.92 | 134 | 0.01 | 0.06 | 0.10 |
| RE26-017 | 402.00 | 402.60 | 0.60 | 2.63 | 10.1 | 2.77 | 194 | 0.00 | 0.00 | 0.07 |
| RE26-017 | 404.95 | 405.50 | 0.55 | 7.54 | 17.4 | 7.79 | 545 | 0.00 | 0.01 | 0.01 |
| Target 4 | ||||||||||
| CO26-001* | 22.00 | 33.70 | 11.70 | 1.06 | 381.3 | 6.51 | 456 | 0.20 | 0.07 | 0.35 |
| including | 23.40 | 24.00 | 0.60 | 2.67 | 456.0 | 9.18 | 643 | 0.43 | 0.07 | 0.50 |
| and | 28.40 | 31.80 | 3.40 | 2.72 | 1048.9 | 17.70 | 1239 | 0.50 | 0.19 | 0.90 |
| including | 28.40 | 29.10 | 0.70 | 7.92 | 1260.0 | 25.92 | 1814 | 1.27 | 0.04 | 0.22 |
| and* | 31.20 | 31.80 | 0.60 | 4.81 | 3540.0 | 55.38 | 3877 | 0.82 | 1.01 | 3.88 |
| CO26-002* | 88.85 | 102.80 | 13.95 | 1.76 | 263.8 | 5.53 | 387 | 0.04 | 0.01 | 0.03 |
| including | 88.85 | 99.00 | 10.15 | 2.31 | 347.9 | 7.28 | 510 | 0.05 | 0.01 | 0.03 |
| including | 97.00 | 99.00 | 2.00 | 5.32 | 778.5 | 16.44 | 1151 | 0.04 | 0.01 | 0.02 |
| including* | 97.00 | 98.00 | 1.00 | 7.03 | 1255.0 | 24.96 | 1747 | 0.04 | 0.01 | 0.02 |
| CO26-003* | 60.20 | 61.75 | 1.55 | 0.63 | 162.0 | 2.95 | 206 | 0.15 | 0.03 | 0.20 |
| and | 93.40 | 99.90 | 6.50 | 0.22 | 305.0 | 4.57 | 320 | 0.08 | 0.10 | 0.14 |
| including | 96.00 | 98.85 | 2.85 | 0.41 | 662.4 | 9.87 | 691 | 0.17 | 0.22 | 0.31 |
| including* | 97.00 | 97.50 | 0.50 | 1.07 | 1815.0 | 27.00 | 1890 | 0.43 | 0.88 | 1.28 |
| Target 5 | ||||||||||
| MA26-002* | 168.25 | 168.75 | 0.50 | 12.20 | 848.0 | 24.31 | 1702 | 0.02 | 0.05 | 0.07 |
| AP26-002 | 30.60 | 31.10 | 0.50 | 0.40 | 58.7 | 1.24 | 87 | 0.01 | 0.04 | 0.08 |
| AP26-003 | 14.10 | 15.50 | 1.40 | 0.21 | 35.4 | 0.71 | 50 | 0.00 | 0.02 | 0.04 |
| LI26-001 | 27.60 | 28.10 | 0.50 | 0.26 | 61.0 | 1.13 | 79 | 0.01 | 0.01 | 0.01 |
| LI26-002 | 74.35 | 75.00 | 0.65 | 0.48 | 53.7 | 1.25 | 88 | 0.01 | 0.00 | 0.01 |
* Intercepts shown on attached maps and sections** Copper (Cu), lead (Pb) and zinc (Zn) values are shown for information only and are not included in the calculation of AuEq nor being considered as part of the economic model for the deposit by Mithril.
Figure 6: Target 1 plan map showing drill hole trace locations, highlight intercepts in this announcement and resource footprint area
To view an enhanced version of this graphic, please visit:https://images.newsfilecorp.com/files/11657/311734_974ba0de1441f90c_007full.jpg
Copalquin-Zaragoza Drilling Summary
The Copalquin Mine is located on the northwest margin of the Copalquin arroyo just above the site of the historical San Manuel 10 tonne per day mine (Figure 7). There are two tunnels driven at 290 degrees on a 0.4 to 0.8 m wide quartz vein that dips steeply to the northeast. The longer of the two tunnels is 30 m in length and has no stopes.
Matrix supported hydrothermal breccia with black sulphide is observed in the vein in the workings. The vein is in the centre of a 15 m wide zone of similar thinner veins forming a structural corridor. Channel sampling returned assays grading up to 7.48 g/t Au and 300 g/t Ag, over a width of 1.2 m. In 2024, drill holes CDH-151 and CDH-152 were drilled immediately below the workings to test the down dip continuation of the high-grade mineralisation, and holes CDH-154 to CDH-156 were drilled to the northwest and along strike of the workings. The best intercept was in hole CDH-152 grading 1.92 m at 4.50 g/t Au and 520.2 g/t Ag starting from 18.50 m downhole. Drill holes, CDH-151 (partially), -155, and -156 intercepted what is now understood to be a post-mineral dyke system (Tapp) at the projected vein intercept depths and that were previously interpreted to terminate the mineralization.
Across the ridge to the northwest in the Soledad arroyo, the Zaragosa workings appear to be on the same structure (Figure 7). The Zaragoza workings are completely caved and inaccessible but are shown on historical maps to run at 105 degrees directly towards the Copalquin mine 300 m to the southeast. Both tunnels are developed in granodiorite.
In 2025, four holes were completed at Zaragoza as an initial program to undercut historical workings (with channel grades up to 0.75 m with 3.46 g/t Au and 1,190.0 g/t Ag) that were thought to be the possible northwest feeder structure of Target 1. The drilling successfully intercepted high-grade gold and silver approximately 130 m down dip from historical workings. The best drill hole returned assays of 6.4 g/t Au and 4,400.0 g/t Ag over 0.57 m starting from 342.4 m depth in hole MTH-ZG25-37. Hydrothermal vein and quartz breccia zones with anomalous Au and Ag were intercepted in holes MTH-ZG25-39, 40 and 42.
Based on the positive results of previous drilling and new interpretation of the post-mineral dyke system (Tapp) that was applied in the Refugio area9, three drill holes (totalling 528 m) have been completed to test a revised interpretation of the Copalquin structure. All three drill holes successfully intercepted the target structure within the host granodiorite unit.
The three holes were drilled to test the projected extension of the Copalquin vein along strike, and at similar elevation, and across the post-mineral dyke intrusions (Tapp). Hole CO26-001 was the first hole to be drilled on the east side of the Copalquin arroyo as a 60 m step-out from hole CDH-152 and successfully intercepted the Copalquin structure in a 11.70 m wide (downhole length) hydrothermal vein and quartz breccia zone. Drill hole CO26-002 was a 120 m step-out to the northwest of hole CDH-156, and 70 m step-out to the southeast of hole MTH-ZG25-42 to bridge the connection between the Copalquin and Zaragoza structures, and also successfully intercepted a 13.60 m wide (downhole length) mineralized hydrothermal quartz breccia. Hole CO26-003 moved back to the southeast as a 60 m step-out from CO26-001 and successfully intercepted two zones of mineralization, with the upper zone partially truncated by the Tapp system and the lower zone spanning 6.50 m (downhole length) of mineralized quartz breccia and stockwork (see grades reported in Table 1).
Anomalous base metal mineralization was intercepted in all three holes, occurring at generally low concentrations and dominated by zinc and lead, with less common copper (present as chalcopyrite). Based on other drilling results in Target 4 and Target 5, the granodiorite (Tgd) commonly exhibits elevated base metals and silver within polymetallic mineralization. This base metal association may reflect a polymetallic component of the deeper or lower-temperature expression at the base of the broader epithermal silver-gold system.
The program successfully expanded the known footprint of the Copalquin vein along strike at a consistent elevation of approximately 850 metres above sea level, successfully bridged the Copalquin and Zaragosa structures over approximately 500 m of strike length, and identified drilling targets in all directions along the structural corridor. Untested ground exists to the southeast along approximately 600 m along strike and 350 m up-dip between CO26-003 and the historical San Manuel mine, and to the northwest along approximately 400 m of strike with 250 m up-dip of untested ground between MTH-ZG25-39 towards the El Refugio zone (Figure 9).
Figure 7 Copalquin Structure plan map showing drill traces along 500 metres of strike and recent drill intercepts
To view an enhanced version of this graphic, please visit:https://images.newsfilecorp.com/files/11657/311734_974ba0de1441f90c_008full.jpg
Figure 8: Cross section +/- 100 metres for drilling on the Copalquin Structure
To view an enhanced version of this graphic, please visit:https://images.newsfilecorp.com/files/11657/311734_974ba0de1441f90c_009full.jpg
Figure 9: Long section view of the El Refugio vein looking perpendicular to vein to the northeast
To view an enhanced version of this graphic, please visit:https://images.newsfilecorp.com/files/11657/311734_974ba0de1441f90c_010full.jpg
Other drilling results discussion
Since completion of the Target 1 Mineral Resource drilling program in June 2026, Mithril has been leading an exploration drilling campaign to test geophysical and structural targets. The program has been advancing methodically moving from west to east.
Four holes were completed at El Refugio (2 holes, 1,038 m) and La Soledad (2 holes, 723 m) following the cut-off date of the Target 1 Mineral Resource Estimate. The holes in Refugio tested down dip extension of the vein, with hole RE26-017 successfully intercepting mineralization in 2 zones At La Soledad, drilling was completed to test the southeast extension of the vein, with several notable intercepts (see Table 1) within a narrow and stockwork mineralisation.
In the Refugio west area, five holes were drilled at El Gallo (2 holes, 462 m), La Guacima (1 hole, 228 m) and El Platano (2 holes,1,143 m) areas. The program intended to test the western extension of the Refugio vein between the Mineral Resource area and El Gallo. Presence of the Refugio structure was intercepted in drilling, however mineralization contained no reportable grades. El Platano, located to the northwest of the Target 1 resource area, consists of a zone with strong argillic alteration and which appears to lie along a northeast trending structure. Drill hole EP26–001 targeted intersection of this northeast structure at the top of the hole as well as geophysical anomalies to depth which were explained by Tapp intrusions. Drill hole EP26-002 was drilled to overlap with EP26-001 at a higher elevation, and to test for the continuity of the westerly projected Refugio structure at depth. Hole EP26–002 successfully intersected the Refugio structure between 306.05-311.60 m downhole depth as a brecciated zone with light grey hydrothermal quartz and minor sulphides, and with anomalous but non-reportable grades.
In the Target 5 area, drilling was completed to test the depth and northwest extension of the El Apomal (3 holes, 865 m), Las Lianas (3 holes, 513 m), and La Maquina (1 hole, 234 m). The Apomal holes intercepted quartz breccia structures at the projected depths however did not contain reportable grades. Of note in hole AP26-003 was a semi-massive sulphide intersection, within a northeast trending structure, with 6.2 m of 0.58 % lead and 0.55 % zinc from 200 m, including 1 m with 2.62 % lead and 1.61% zinc from 205.2 m. While base metal mineralization is not a pursued interest by Mithril, the intercept offers insight into the broader mineralized system in the Target 5 area. At La Maquina, hole MA26-002 was a follow-up to the success of the discovery hole MA26-00110. Hole MA26-001 was drilled as a 150 m step-out to the northwest and successfully intercepted the structure approximately 100 m below surface.
A summary of all holes being announced in this News Release is shown in Table 2, with a complete list of all assays >0.10 g/t AuEq listed in Table 3 .
Table 2: Drill hole collar details included in this announcement
| Hole ID | Easting | Northing | Elevation | Azimuth | Inclination | Depth (m) |
| (m) | (m) | (m) | (degrees) | (degrees) | ||
| Target 1 | ||||||
| RE26-016 | 288999 | 2824048 | 1191 | 160 | -63 | 501 |
| RE26-017 | 289066 | 2824050 | 1178 | 154 | -72 | 537 |
| LS26-008 | 289703 | 2824063 | 1088 | 200 | -60 | 351 |
| LS26-009 | 289728 | 2824453 | 1077 | 160 | -45 | 372 |
| EP26-001 | 288097 | 2824801 | 1105 | 155 | -45 | 651 |
| EP26-002 | 288025 | 2824144 | 948 | 165 | -55 | 492 |
| GA26-001 | 287771 | 2823853 | 945 | 190 | -60 | 162 |
| GA26-002 | 287968 | 2823975 | 913 | 180 | -60 | 300 |
| LG26-001 | 288143 | 2823670 | 984 | 190 | -48 | 228 |
| Target 4 | ||||||
| CO26-001 | 290285 | 2823175 | 887 | 195 | -52 | 120 |
| CO26-002 | 290052 | 2823308 | 1004 | 220 | -63 | 288 |
| CO26-003 | 290325 | 2823185 | 902 | 170 | -45 | 120 |
| Target 5 | ||||||
| MA26-002 | 288867 | 2822995 | 725 | 217 | -45 | 234 |
| LI26-001 | 288718 | 2822450 | 826 | 235 | -70 | 219 |
| LI26-002 | 288837 | 2822319 | 844 | 240 | -45 | 153 |
| LI26-003 | 288842 | 2822317 | 843 | 220 | -45 | 141 |
| AP26-001 | 287756 | 2822648 | 814 | 41 | -60 | 255 |
| AP26-002 | 287703 | 2822648 | 843 | 42 | -55 | 300 |
| AP26-003 | 287654 | 2822716 | 865 | 40 | -55 | 310 |
Note: Some collar locations may be reported with approximate handheld GPS coordinates, while surveying with differential GPS is pending completion
Table 3: All drill results reported greater than or equal to 0.1 g/t AuEq
| Hole ID | From (m) | To (m) | Length (m) | Au g/t | Ag g/t | AuEq g/t | AgEq g/t |
| Target 1 | |||||||
| RE26-017 | 402.00 | 402.60 | 0.60 | 2.63 | 10.1 | 2.77 | 194 |
| RE26-017 | 402.60 | 403.30 | 0.70 | 0.08 | 1.5 | 0.11 | 7 |
| RE26-017 | 404.95 | 405.50 | 0.55 | 7.54 | 17.4 | 7.79 | 545 |
| RE26-017 | 405.50 | 406.00 | 0.50 | 0.07 | 2.6 | 0.11 | 8 |
| RE26-017 | 432.00 | 434.00 | 2.00 | 0.12 | 1.2 | 0.13 | 9 |
| RE26-017 | 434.00 | 435.00 | 1.00 | 0.11 | 8.0 | 0.22 | 16 |
| RE26-017 | 437.00 | 438.00 | 1.00 | 0.10 | 4.3 | 0.16 | 11 |
| RE26-017 | 444.30 | 445.30 | 1.00 | 0.01 | 5.9 | 0.1 | 7 |
| LS26-008 | 30.40 | 31.00 | 0.60 | 0.11 | 12.0 | 0.28 | 19 |
| LS26-008 | 31.00 | 32.20 | 1.20 | 0.06 | 7.2 | 0.16 | 12 |
| LS26-008 | 32.20 | 33.25 | 1.05 | 0.17 | 25.0 | 0.52 | 37 |
| LS26-008 | 33.25 | 33.75 | 0.50 | 0.31 | 36.3 | 0.83 | 58 |
| LS26-008 | 33.75 | 34.35 | 0.60 | 0.13 | 6.9 | 0.23 | 16 |
| LS26-008 | 34.35 | 34.85 | 0.50 | 0.13 | 6.3 | 0.22 | 15 |
| LS26-008 | 34.85 | 35.35 | 0.50 | 0.19 | 8.4 | 0.31 | 22 |
| LS26-008 | 35.35 | 36.00 | 0.65 | 0.85 | 13.6 | 1.04 | 73 |
| LS26-008 | 36.00 | 36.50 | 0.50 | 0.57 | 18.2 | 0.83 | 58 |
| LS26-008 | 36.50 | 37.00 | 0.50 | 0.48 | 25.9 | 0.85 | 60 |
| LS26-008 | 37.00 | 37.90 | 0.90 | 0.47 | 11.0 | 0.63 | 44 |
| LS26-008 | 37.90 | 38.45 | 0.55 | 0.16 | 4.2 | 0.22 | 15 |
| LS26-008 | 38.45 | 39.20 | 0.75 | 0.06 | 2.7 | 0.1 | 7 |
| LS26-008 | 39.20 | 40.10 | 0.90 | 2.34 | 17.3 | 2.59 | 181 |
| LS26-008 | 40.10 | 40.65 | 0.55 | 0.12 | 2.1 | 0.15 | 10 |
| LS26-008 | 40.65 | 41.20 | 0.55 | 0.62 | 4.7 | 0.69 | 48 |
| LS26-008 | 41.20 | 41.70 | 0.50 | 27.90 | 156.0 | 30.13 | 2109 |
| LS26-008 | 41.70 | 42.25 | 0.55 | 0.08 | 13.8 | 0.27 | 19 |
| LS26-008 | 43.00 | 43.85 | 0.85 | 2.29 | 1.1 | 2.31 | 161 |
| LS26-008 | 46.00 | 47.00 | 1.00 | 0.07 | 4.9 | 0.14 | 10 |
| LS26-008 | 49.00 | 50.50 | 1.50 | 0.08 | 5.3 | 0.15 | 11 |
| LS26-008 | 52.00 | 53.00 | 1.00 | 0.37 | 3.5 | 0.42 | 29 |
| LS26-008 | 55.75 | 57.00 | 1.25 | 0.03 | 5.6 | 0.11 | 7 |
| LS26-008 | 58.05 | 59.15 | 1.10 | 0.08 | 25.6 | 0.45 | 31 |
| LS26-008 | 60.65 | 61.40 | 0.75 | 0.03 | 5.9 | 0.11 | 8 |
| LS26-008 | 85.20 | 86.30 | 1.10 | 0.12 | 2.4 | 0.16 | 11 |
| LS26-008 | 86.30 | 87.35 | 1.05 | 0.18 | 2.5 | 0.21 | 15 |
| LS26-008 | 87.35 | 87.85 | 0.50 | 0.85 | 8.2 | 0.97 | 68 |
| LS26-008 | 104.00 | 104.80 | 0.80 | 0.14 | 1.7 | 0.17 | 12 |
| LS26-008 | 104.80 | 105.65 | 0.85 | 0.44 | 1.5 | 0.46 | 32 |
| LS26-008 | 106.95 | 107.60 | 0.65 | 0.09 | 1.9 | 0.12 | 8 |
| LS26-008 | 157.40 | 157.90 | 0.50 | 0.03 | 5.5 | 0.11 | 8 |
| LS26-008 | 164.00 | 164.50 | 0.50 | 0.08 | 5.6 | 0.16 | 11 |
| LS26-008 | 234.30 | 234.90 | 0.60 | 0.05 | 5.3 | 0.13 | 9 |
| LS26-008 | 236.10 | 236.75 | 0.65 | 0.08 | 5.7 | 0.16 | 11 |
| LS26-008 | 239.35 | 240.10 | 0.75 | 0.06 | 9.4 | 0.2 | 14 |
| LS26-008 | 244.25 | 245.30 | 1.05 | 0.38 | 0.6 | 0.39 | 27 |
| LS26-009 | 76.55 | 78.55 | 2.00 | 0.36 | 0.3 | 0.37 | 26 |
| LS26-009 | 80.45 | 81.10 | 0.65 | 0.15 | 6.5 | 0.25 | 17 |
| LS26-009 | 81.10 | 81.60 | 0.50 | 0.47 | 4.5 | 0.53 | 37 |
| LS26-009 | 81.60 | 82.20 | 0.60 | 0.77 | 3.2 | 0.81 | 57 |
| LS26-009 | 82.20 | 82.80 | 0.60 | 1.29 | 3.2 | 1.33 | 93 |
| LS26-009 | 82.80 | 83.50 | 0.70 | 0.73 | 4.9 | 0.8 | 56 |
| LS26-009 | 123.00 | 124.30 | 1.30 | 0.11 | 1.4 | 0.13 | 9 |
| LS26-009 | 124.80 | 125.30 | 0.50 | 0.08 | 7.1 | 0.18 | 13 |
| LS26-009 | 125.30 | 125.80 | 0.50 | 1.31 | 49.5 | 2.01 | 141 |
| LS26-009 | 125.80 | 126.30 | 0.50 | 1.05 | 97.0 | 2.43 | 170 |
| LS26-009 | 126.30 | 126.80 | 0.50 | 0.39 | 64.5 | 1.31 | 92 |
| LS26-009 | 127.30 | 128.10 | 0.80 | 0.12 | 7.2 | 0.22 | 16 |
| LS26-009 | 128.10 | 129.00 | 0.90 | 0.02 | 5.4 | 0.1 | 7 |
| LS26-009 | 129.60 | 130.40 | 0.80 | 0.13 | 7.8 | 0.24 | 17 |
| LS26-009 | 130.40 | 131.00 | 0.60 | 0.14 | 6.8 | 0.23 | 16 |
| LS26-009 | 131.00 | 131.70 | 0.70 | 0.14 | 5.1 | 0.21 | 15 |
| LS26-009 | 136.00 | 137.00 | 1.00 | 0.09 | 3.4 | 0.14 | 10 |
| LS26-009 | 137.00 | 137.50 | 0.50 | 0.31 | 6.5 | 0.4 | 28 |
| LS26-009 | 145.00 | 145.65 | 0.65 | 0.11 | 3.6 | 0.16 | 11 |
| LS26-009 | 145.65 | 147.00 | 1.35 | 0.05 | 4.5 | 0.11 | 8 |
| LS26-009 | 151.50 | 153.00 | 1.50 | 0.11 | 6.5 | 0.2 | 14 |
| LS26-009 | 153.00 | 153.55 | 0.55 | 0.14 | 7.1 | 0.24 | 17 |
| LS26-009 | 176.00 | 177.00 | 1.00 | 0.02 | 6.1 | 0.11 | 8 |
| LS26-009 | 214.00 | 214.90 | 0.90 | 0.08 | 7.4 | 0.18 | 13 |
| LS26-009 | 310.40 | 310.90 | 0.50 | 0.05 | 3.4 | 0.1 | 7 |
| LS26-009 | 312.60 | 313.35 | 0.75 | 0.04 | 5.0 | 0.11 | 8 |
| EP26-002 | 275.40 | 275.90 | 0.50 | 0.03 | 5.1 | 0.1 | 7 |
| EP26-002 | 297.00 | 298.00 | 1.00 | 0.02 | 5.5 | 0.1 | 7 |
| EP26-002 | 299.00 | 299.90 | 0.90 | 0.02 | 5.7 | 0.1 | 7 |
| EP26-002 | 299.90 | 300.60 | 0.70 | 0.02 | 8.7 | 0.15 | 10 |
| EP26-002 | 309.30 | 310.00 | 0.70 | 0.03 | 5.1 | 0.11 | 7 |
| LG26-001 | 9.00 | 10.20 | 1.20 | 0.03 | 5.3 | 0.11 | 7 |
| LG26-001 | 10.20 | 12.00 | 1.80 | 0.10 | 10.7 | 0.25 | 18 |
| LG26-001 | 20.30 | 21.00 | 0.70 | 0.07 | 3.7 | 0.12 | 8 |
| LG26-001 | 21.00 | 21.90 | 0.90 | 0.06 | 3.1 | 0.1 | 7 |
| GA26-001 | 86.45 | 87.00 | 0.55 | 0.10 | 5.4 | 0.17 | 7 |
| Target 4 | |||||||
| CO26-001 | 7.00 | 8.00 | 1.00 | 0.02 | 12.1 | 0.2 | 14 |
| CO26-001 | 22.00 | 22.90 | 0.90 | 0.18 | 23.5 | 0.52 | 36 |
| CO26-001 | 22.90 | 23.40 | 0.50 | 1.09 | 221.0 | 4.25 | 297 |
| CO26-001 | 23.40 | 24.00 | 0.60 | 2.67 | 456.0 | 9.18 | 643 |
| CO26-001 | 24.00 | 24.90 | 0.90 | 0.07 | 14.0 | 0.27 | 19 |
| CO26-001 | 24.90 | 26.00 | 1.10 | 0.27 | 212.0 | 3.3 | 231 |
| CO26-001 | 26.00 | 27.00 | 1.00 | 0.14 | 67.4 | 1.11 | 77 |
| CO26-001 | 27.00 | 27.90 | 0.90 | 0.07 | 32.3 | 0.53 | 37 |
| CO26-001 | 27.90 | 28.40 | 0.50 | 0.02 | 12.2 | 0.19 | 14 |
| CO26-001 | 28.40 | 29.10 | 0.70 | 7.92 | 1260.0 | 25.92 | 1814 |
| CO26-001 | 29.10 | 29.95 | 0.85 | 0.03 | 20.0 | 0.32 | 22 |
| CO26-001 | 29.95 | 30.70 | 0.75 | 0.73 | 489.0 | 7.72 | 540 |
| CO26-001 | 30.70 | 31.20 | 0.50 | 0.47 | 353.0 | 5.51 | 386 |
| CO26-001 | 31.20 | 31.80 | 0.60 | 4.81 | 3540.0 | 55.38 | 3877 |
| CO26-001 | 31.80 | 32.30 | 0.50 | 0.35 | 141.0 | 2.36 | 166 |
| CO26-001 | 32.30 | 32.80 | 0.50 | 0.09 | 43.4 | 0.71 | 50 |
| CO26-001 | 32.80 | 33.70 | 0.90 | 0.10 | 54.7 | 0.88 | 61 |
| CO26-001 | 34.90 | 35.50 | 0.60 | 0.01 | 8.1 | 0.13 | 9 |
| CO26-002 | 53.50 | 54.00 | 0.50 | 0.06 | 5.1 | 0.13 | 9 |
| CO26-002 | 58.30 | 58.85 | 0.55 | 0.08 | 24.9 | 0.43 | 30 |
| CO26-002 | 58.85 | 59.45 | 0.60 | 0.04 | 6.6 | 0.13 | 9 |
| CO26-002 | 77.65 | 78.15 | 0.50 | 0.19 | 16.7 | 0.43 | 30 |
| CO26-002 | 88.85 | 89.85 | 1.00 | 3.17 | 438.0 | 9.43 | 660 |
| CO26-002 | 89.85 | 90.85 | 1.00 | 1.06 | 125.0 | 2.85 | 199 |
| CO26-002 | 90.85 | 92.00 | 1.15 | 1.97 | 388.0 | 7.51 | 526 |
| CO26-002 | 92.00 | 93.00 | 1.00 | 0.36 | 52.0 | 1.1 | 77 |
| CO26-002 | 93.00 | 94.00 | 1.00 | 2.11 | 194.0 | 4.88 | 342 |
| CO26-002 | 94.00 | 95.00 | 1.00 | 0.67 | 105.0 | 2.17 | 152 |
| CO26-002 | 95.00 | 96.00 | 1.00 | 1.88 | 493.0 | 8.92 | 624 |
| CO26-002 | 96.00 | 97.00 | 1.00 | 1.29 | 121.0 | 3.02 | 211 |
| CO26-002 | 97.00 | 98.00 | 1.00 | 7.03 | 1255.0 | 24.96 | 1747 |
| CO26-002 | 98.00 | 99.00 | 1.00 | 3.61 | 302.0 | 7.92 | 555 |
| CO26-002 | 99.00 | 100.00 | 1.00 | 0.21 | 23.7 | 0.54 | 38 |
| CO26-002 | 100.00 | 101.00 | 1.00 | 0.37 | 92.4 | 1.69 | 118 |
| CO26-002 | 101.00 | 102.00 | 1.00 | 0.32 | 21.3 | 0.63 | 44 |
| CO26-002 | 102.00 | 102.80 | 0.80 | 0.23 | 14.5 | 0.44 | 31 |
| CO26-002 | 105.00 | 106.00 | 1.00 | 0.03 | 7.1 | 0.13 | 9 |
| CO26-002 | 106.00 | 106.85 | 0.85 | 0.04 | 7.2 | 0.14 | 10 |
| CO26-002 | 106.85 | 108.20 | 1.35 | 0.17 | 5.3 | 0.24 | 17 |
| CO26-002 | 110.00 | 110.50 | 0.50 | 0.10 | 12.5 | 0.28 | 20 |
| CO26-002 | 110.50 | 111.15 | 0.65 | 0.25 | 32.7 | 0.72 | 50 |
| CO26-002 | 111.15 | 112.00 | 0.85 | 0.15 | 6.6 | 0.25 | 17 |
| CO26-002 | 160.05 | 161.05 | 1.00 | 0.07 | 2.4 | 0.1 | 7 |
| CO26-002 | 161.05 | 161.70 | 0.65 | 0.29 | 11.8 | 0.46 | 32 |
| CO26-002 | 161.70 | 162.45 | 0.75 | 0.09 | 3.0 | 0.13 | 9 |
| CO26-002 | 162.45 | 163.00 | 0.55 | 0.08 | 3.5 | 0.13 | 9 |
| CO26-002 | 163.00 | 164.10 | 1.10 | 0.15 | 9.4 | 0.28 | 20 |
| CO26-002 | 164.10 | 164.65 | 0.55 | 0.15 | 14.9 | 0.36 | 25 |
| CO26-002 | 167.60 | 168.10 | 0.50 | 0.10 | 5.5 | 0.18 | 12 |
| CO26-002 | 168.10 | 169.25 | 1.15 | 0.28 | 16.1 | 0.51 | 36 |
| CO26-002 | 170.15 | 171.00 | 0.85 | 0.05 | 4.5 | 0.12 | 8 |
| CO26-003 | 60.20 | 61.00 | 0.80 | 0.54 | 148.0 | 2.65 | 186 |
| CO26-003 | 61.00 | 61.75 | 0.75 | 0.73 | 177.0 | 3.26 | 228 |
| CO26-003 | 61.75 | 63.00 | 1.25 | 0.04 | 6.4 | 0.13 | 9 |
| CO26-003 | 81.00 | 81.60 | 0.60 | 0.07 | 9.0 | 0.20 | 14 |
| CO26-003 | 93.40 | 94.00 | 0.60 | 0.31 | 105.0 | 1.81 | 126 |
| CO26-003 | 96.00 | 96.50 | 0.50 | 0.40 | 760.0 | 11.25 | 788 |
| CO26-003 | 96.50 | 97.00 | 0.50 | 0.05 | 66.5 | 1.00 | 70 |
| CO26-003 | 97.00 | 97.50 | 0.50 | 1.07 | 1815.0 | 27.00 | 1890 |
| CO26-003 | 97.50 | 98.00 | 0.50 | 0.36 | 427.0 | 6.46 | 452 |
| CO26-003 | 98.00 | 98.85 | 0.85 | 0.26 | 416.0 | 6.20 | 434 |
| CO26-003 | 98.85 | 99.90 | 1.05 | 0.04 | 21.2 | 0.34 | 24 |
| CO26-003 | 99.90 | 101.00 | 1.10 | 0.01 | 7.3 | 0.11 | 8 |
| Target 5 | |||||||
| MA26-002 | 7.25 | 7.75 | 0.50 | 0.01 | 8.5 | 0.13 | 9 |
| MA26-002 | 102.85 | 103.35 | 0.50 | 0.07 | 21.2 | 0.37 | 26 |
| MA26-002 | 168.25 | 168.75 | 0.50 | 12.20 | 848.0 | 24.31 | 1702 |
| LI26-001 | 6.00 | 7.00 | 1.00 | 0.04 | 4.0 | 0.1 | 7 |
| LI26-001 | 25.00 | 26.00 | 1.00 | 0.04 | 5.8 | 0.12 | 9 |
| LI26-001 | 27.60 | 28.10 | 0.50 | 0.26 | 61.0 | 1.13 | 79 |
| LI26-001 | 30.20 | 31.35 | 1.15 | 0.03 | 10.3 | 0.18 | 12 |
| LI26-001 | 68.00 | 68.50 | 0.50 | 0.10 | 3.7 | 0.15 | 11 |
| LI26-001 | 85.10 | 85.60 | 0.50 | 0.09 | 5.1 | 0.16 | 11 |
| LI26-001 | 89.60 | 90.55 | 0.95 | 0.09 | 3.2 | 0.14 | 10 |
| LI26-001 | 94.30 | 95.40 | 1.10 | 0.10 | 8.2 | 0.22 | 15 |
| LI26-001 | 103.15 | 103.65 | 0.50 | 0.10 | 2.6 | 0.13 | 9 |
| LI26-001 | 109.50 | 110.10 | 0.60 | 0.21 | 5.0 | 0.28 | 19 |
| LI26-001 | 110.10 | 110.70 | 0.60 | 0.22 | 1.2 | 0.23 | 16 |
| LI26-001 | 207.45 | 208.45 | 1.00 | 0.09 | 20.8 | 0.39 | 27 |
| LI26-001 | 208.45 | 209.00 | 0.55 | 0.10 | 29.5 | 0.52 | 37 |
| LI26-002 | 43.75 | 44.30 | 0.55 | 0.06 | 4.8 | 0.13 | 9 |
| LI26-002 | 69.40 | 70.00 | 0.60 | 0.11 | 1.8 | 0.14 | 10 |
| LI26-002 | 70.00 | 70.95 | 0.95 | 0.10 | 1.1 | 0.12 | 8 |
| LI26-002 | 70.95 | 71.65 | 0.70 | 0.10 | 14.0 | 0.3 | 21 |
| LI26-002 | 74.35 | 75.00 | 0.65 | 0.48 | 53.7 | 1.25 | 88 |
| LI26-002 | 99.00 | 100.00 | 1.00 | 0.09 | 4.3 | 0.15 | 10 |
| LI26-003 | 71.50 | 72.45 | 0.95 | 0.03 | 12.3 | 0.21 | 15 |
| LI26-003 | 111.00 | 111.70 | 0.70 | 0.08 | 6.0 | 0.17 | 12 |
| LI26-003 | 111.70 | 112.25 | 0.55 | 0.09 | 6.0 | 0.18 | 13 |
| AP26-001 | 162.30 | 162.85 | 0.55 | 0.08 | 25.3 | 0.45 | 31 |
| AP26-001 | 166.45 | 166.95 | 0.50 | 0.22 | 54.1 | 0.99 | 70 |
| AP26-001 | 230.50 | 231.05 | 0.55 | 0.03 | 9.7 | 0.17 | 12 |
| AP26-001 | 231.70 | 232.35 | 0.65 | 0.03 | 7.2 | 0.13 | 9 |
| AP26-001 | 232.35 | 233.10 | 0.75 | 0.02 | 10.5 | 0.17 | 12 |
| AP26-001 | 235.00 | 235.50 | 0.50 | 0.03 | 9.1 | 0.16 | 11 |
| AP26-002 | 25.30 | 25.85 | 0.55 | 0.12 | 39.2 | 0.68 | 48 |
| AP26-002 | 28.95 | 29.45 | 0.50 | 0.06 | 8.4 | 0.18 | 13 |
| AP26-002 | 29.45 | 30.60 | 1.15 | 0.04 | 4.4 | 0.1 | 7 |
| AP26-002 | 30.60 | 31.10 | 0.50 | 0.40 | 58.7 | 1.24 | 86 |
| AP26-002 | 31.10 | 31.90 | 0.80 | 0.05 | 6.7 | 0.14 | 10 |
| AP26-002 | 39.75 | 40.25 | 0.50 | 0.08 | 1.9 | 0.1 | 7 |
| AP26-002 | 177.90 | 178.40 | 0.50 | 0.02 | 6.4 | 0.12 | 8 |
| AP26-002 | 224.25 | 224.85 | 0.60 | 0.67 | 4.5 | 0.73 | 51 |
| AP26-002 | 241.90 | 242.70 | 0.80 | 0.04 | 9.9 | 0.18 | 13 |
| AP26-002 | 242.70 | 243.20 | 0.50 | 0.02 | 11.1 | 0.18 | 13 |
| AP26-002 | 243.20 | 243.70 | 0.50 | 0.05 | 22.0 | 0.37 | 26 |
| AP26-002 | 282.15 | 283.15 | 1.00 | 0.02 | 5.9 | 0.11 | 7 |
| AP26-002 | 283.15 | 283.65 | 0.50 | 0.02 | 6.5 | 0.11 | 8 |
| AP26-003 | 14.10 | 14.75 | 0.65 | 0.26 | 48.0 | 0.94 | 66 |
| AP26-003 | 14.75 | 15.50 | 0.75 | 0.17 | 24.5 | 0.52 | 36 |
| AP26-003 | 105.00 | 105.50 | 0.50 | 0.03 | 8.2 | 0.14 | 10 |
| AP26-003 | 200.00 | 200.50 | 0.50 | 0.01 | 8.4 | 0.13 | 9 |
| AP26-003 | 200.50 | 201.00 | 0.50 | 0.03 | 17.3 | 0.28 | 20 |
| AP26-003 | 205.20 | 205.70 | 0.50 | 0.03 | 13.5 | 0.22 | 15 |
| AP26-003 | 205.70 | 206.20 | 0.50 | 0.02 | 17.9 | 0.27 | 19 |
| AP26-003 | 219.00 | 219.50 | 0.50 | 0.10 | 12.7 | 0.28 | 20 |
| AP26-003 | 225.00 | 226.00 | 1.00 | 0.07 | 9.3 | 0.21 | 14 |
| AP26-003 | 226.00 | 226.50 | 0.50 | 0.21 | 27.4 | 0.6 | 42 |
*See gold equivalent (AuEq) formula in the ABOUT THE COPALQUIN SILVER GOLD PROJECT section
COPALQUIN – TARGET 1 UPGRADED MRE
(For full detail of the Target 1 MRE Upgrade see ASX announcement 3 July 2026 – "Amended Announcement Copalquin Project Target 1 Deposit MRE")
The MRE for Target 1 (Table 4) was generated as a base case assuming bulk underground mining method (long hole open stoping – LHOS) with mining widths averaging approximately 4 metres. The MSO work identified areas where more selective underground mining methods such as cut and fill (higher cost than LHOS) could be utilised to reduce dilution and increase mined grades. Table 5 provides the highlighted base case for undiluted mineralisation reporting within the underground mining shapes (mine stope optimiser – MSO) at a cut-off grade of 1.5 g/t AuEq plus sensitivities to gold prices.
The difference between the undiluted grade of 6.85 g/t AuEq (Table 5 Indicated base case) and the diluted grade of 4.26 g/t AuEq (Table 4, Total Indicated Target 1 MRE) reflects this conservative mining dilution assumption whereby lower grade mineralisation surrounding the high-grade core would be extracted within geometry of a minable shape adding more tonnes and ounces at a lower average grade. More detailed mining study work will fully assess the mining methods across the Target 1 MRE.
Table 4 Upgraded Copalquin Target 1 Mineral Resource Estimate (underground mining shape constrained & diluted)
| Target 1Area | Class | Tonnes | Gold | Silver | GoldEq. | Gold | Silver | GoldEq. |
| (kt) | (g/t) | (g/t) | (g/t) | (koz) | (koz) | (koz) | ||
| El Refugio | Ind | 2,557 | 3.38 | 73.7 | 4.44 | 278 | 6,061 | 365 |
| Inf | 1,217 | 2.17 | 82.1 | 3.35 | 85 | 3,214 | 131 | |
| La Soledad | Ind | 834 | 2.43 | 90.2 | 3.72 | 65 | 2,418 | 100 |
| Inf | 219 | 2.54 | 26.1 | 2.92 | 18 | 184 | 21 | |
| Total | Ind | 3,391 | 3.15 | 77.8 | 4.26 | 343 | 8,479 | 464 |
| Inf | 1,436 | 2.23 | 73.6 | 3.28 | 103 | 3,398 | 151 |
Notes to Table 4:
- Diluted to a minimum 2 m shape width with a 92% mining recovery.
- Metallurgical recoveries of 96% for Au and 91% for Ag, from metallurgical test work on Target 1 composite samples. Longhole Open Stope mining with a total Mining+Processing+General and Administration (G&A) cost of $97/t processed operating cost comprised of $60/t incremental mining, $25/t processing, $10/t G&A, and $2/t sustaining.
- The mineable shapes reported are valued greater than the incremental cost to mine, which equates to approximately 1.0 g/t AuEq on a fully diluted basis.
Table 5 Gold price sensitivity to constraining shapes, reported at 1.5 g/t AuEq cut-off (constrained and undiluted)
| Au Prices | Classification | Tonnes | Gold | Silver | Gold Eq. | Gold | Silver | Gold Eq. |
| (USD) | (kt) | (g/t) | (g/t) | (g/t) | (koz) | (koz) | (koz) | |
| 2,700 | Ind | 1,888 | 5.28 | 126.1 | 7.08 | 321 | 7,654 | 430 |
| Inf | 831 | 3.46 | 113.7 | 5.08 | 92 | 3,038 | 136 | |
| 3,000 | Ind | 1,941 | 5.18 | 124.2 | 6.96 | 323 | 7,752 | 434 |
| Inf | 863 | 3.39 | 111.7 | 4.98 | 94 | 3,099 | 138 | |
| 3,300 | Ind | 1,990 | 5.10 | 122.4 | 6.85 | 326 | 7,832 | 438 |
| Inf | 900 | 3.32 | 109.1 | 4.87 | 96 | 3,155 | 141 | |
| 3,500 | Ind | 2,038 | 5.01 | 120.9 | 6.74 | 329 | 7,922 | 442 |
| Inf | 923 | 3.27 | 107.5 | 4.81 | 97 | 3,189 | 143 | |
| 4,000 | Ind | 2,074 | 4.96 | 119.7 | 6.67 | 330 | 7,984 | 445 |
| Inf | 949 | 3.23 | 105.9 | 4.74 | 98 | 3,233 | 145 |
Notes to Table 5:
-ENDS- Released with the authority of the Board.For further information contact:
| John SkeetManaging Director and CEOjskeet@mithrilsilvergold.com +61 435 766 809 | NIKLI COMMUNICATIONSCorporate Communicationsliz@mithrilsilvergold.com nicole@mithrilsilvergold.com |
The Australian Securities Exchange has not reviewed and does not accept responsibility for the accuracy or adequacy of this release.
Neither TSX Venture Exchange nor its Regulation Services Provider (as that term is defined in policies of the TSX Venture Exchange) accepts responsibility for the adequacy or accuracy of this release.
Competent Persons Statement (JORC), and Qualified Persons (NI 43-101) Statement
The information in this announcement that relates to metallurgical test results, mineral processing and project development and study work has been compiled, reviewed and approved by Mr John Skeet who is Mithril's CEO and Managing Director. Mr Skeet is a Fellow of the Australasian Institute of Mining and Metallurgy. This is a Recognised Professional Organisation (RPO) under the Joint Ore Reserves Committee (JORC) Code and Acceptable Foreign Association under NI 43-101.
Mr Skeet has sufficient experience of relevance to the styles of mineralisation and the types of deposits under consideration, and to the activities undertaken, to qualify as a Competent Person (non-independent) as defined in the 2012 Edition of the Joint Ore Reserves Committee (JORC) Australasian Code for Reporting of Exploration Results, Mineral Resources and Ore Reserves, and as a Qualified Person (non-independent) as defined by NI 43-101. Mr Skeet consents to the inclusion in this report of the matters based on information in the form and context in which it appears. The Australian Securities Exchange has not reviewed and does not accept responsibility for the accuracy or adequacy of this release.
The information in this announcement that relates to sampling techniques, sample data, exploration results and geological interpretation for Mithril's Mexican project, has been compiled, reviewed and approved by Mr James Barr who is Mithril's Vice President – Exploration. Mr Barr is a registered member and Professional Geologist (P.Geo.) of the Engineers and Geoscientists of British Columbia. This is a Recognised Professional Organisation (RPO) under the Joint Ore Reserves Committee (JORC) Code and recognized Canadian Professional Association under NI 43-101.
Mr Barr has sufficient experience of relevance to the styles of mineralisation and the types of deposits under consideration, and to the activities undertaken, to qualify as a Competent Person (non-independent) as defined in the 2012 Edition of the Joint Ore Reserves Committee (JORC) Australasian Code for Reporting of Exploration Results, Mineral Resources and Ore Reserves, and as a Qualified Person (non-independent) as defined by NI 43-101. Mr Barr consents to the inclusion in this report of the matters based on information in the form and context in which it appears.
The information in this announcement that relates to Mineral Resources has been compiled, reviewed and approved by Mr John Sims, a Certified Registered Geologist (CPG) with the American Institute of Professional Geologists (AIPG). This is a Recognised Professional Organisation (RPO) under the Joint Ore Reserves Committee (JORC) Code and Acceptable Foreign Association under NI 43-101.
Mr Sims is acting as the Competent Person (independent), as defined in the 2012 Edition of the Joint Ore Reserves Committee (JORC) Australasian Code for Reporting of Exploration Results, Mineral Resources and Ore Reserves, and as the Qualified Person (independent) as defined by NI 43-101, for the reporting of the Upgraded Copalquin Target 1 Mineral Resource Estimate, with effective date of June 29, 2026. A site visit was carried out by Mr Sims, between 5 May 2025 and 7 May 2025 to observe the drilling, logging, sampling and assay database. Mr Sims has reviewed and approved the contents of this report, and consents to the inclusion in this report of the matters based on information in the form and context in which it appears.
The relevant sections of "JORC Code, 2012 Edition – Table 1" as defined by the Joint Ore Reserves Committee (JORC) Code are incorporated into the Public Report announced as an amended version on ASX dated 3 July 2026 – Amended Announcement Copalquin Project Target 1 Deposit MRE.
A NI 43-101 Technical Report entitled "Technical Report and Upgraded Mineral Resource Estimate for the Copalquin Target 1 Area, Durango, Mexico" will be filed on SEDAR+ within 45 days of the release.
Qualified Persons – NI 43-101
Scientific and technical information in this Report has been reviewed and approved by Mr John Skeet (FAUSIMM, CP) Mithril's Managing Director and Chief Executive Officer. Mr John Skeet is a qualified person within the meaning of NI 43-101.
Samples are sent to ALS Global with sample preparation performed in Chihuahua City, Mexico and assaying of sample pulps performed in North Vancouver, BC, Canada.
JORC Code, 2012 Edition – Table 1 Section 1 Sampling Techniques and Data
| Criteria | JORC Code explanation | Commentary |
| Sampling techniques |
|
|
| Drilling techniques |
|
|
| Drill sample recovery |
|
|
| Logging |
|
|
| Sub-sampling techniques and sample preparation |
|
|
| Quality of assay data and laboratory tests |
|
|
| Verification of sampling and assaying |
|
|
| Location of data points |
|
|
| Data spacing and distribution |
|
|
| Orientation of data in relation to geological structure |
|
|
| Sample security |
|
|
| Audits or reviews |
|
|
Section 2 Reporting of Exploration Results
| Criteria | JORC Code explanation | Commentary | ||||||||||
| Mineral tenement and land tenure status |
|
|
||||||||||
| No. | Concession | Concession Title number | Area (Ha) | Location | ||||||||
| 1 | LA SOLEDAD | 52033 | 6 | Tamazula, Durango, Mexico | ||||||||
| 2 | EL COMETA | 164869 | 36 | Tamazula, Durango, Mexico | ||||||||
| 3 | SAN MANUEL | 165451 | 36 | Tamazula, Durango, Mexico | ||||||||
| 4 | COPALQUIN | 178014 | 20 | Tamazula, Durango, Mexico | ||||||||
| 5 | EL SOL | 236130 | 6,000 | Tamazula, Durango and Badiraguato, Sinaloa, México | ||||||||
| 6 | EL CORRAL | 236131 | 907.3243 | Tamazula, Durango and Badiraguato, Sinaloa, México | ||||||||
| Exploration done by other parties |
|
|
||||||||||
| Geology |
|
|
||||||||||
| Drill hole Information |
|
|
||||||||||
| Data aggregation methods |
|
|
||||||||||
| AuRaw | Agraw | Length(m) | Au*length | Ag*length | ||||||||
| 7.51 | 678 | 0.5 | 3.755 | 339 | ||||||||
| 11.85 | 425 | 0.55 | 6.5175 | 233.75 | ||||||||
| 0 | 0 | 0 | 0 | 0 | ||||||||
| 0.306 | 16 | 1 | 0.306 | 16 | ||||||||
| 0.364 | 31.7 | 1 | 0.364 | 31.7 | ||||||||
| 3.15 | 241 | 0.5 | 1.575 | 120.5 | ||||||||
| 10.7 | 709 | 0.5 | 5.35 | 354.5 | ||||||||
| 15.6 | 773 | 0.5 | 7.8 | 386.5 | ||||||||
| From | To | Length | Au g/t | Ag g/t | ||||||||
| 4.55 | 25.667 | 1481.9 | 91.95 | 96.5 | 4.55 | 5.64 | 325.7 | |||||
|
||||||||||||
| Relationship between mineralisation widths and intercept lengths |
|
|
||||||||||
| Diagrams |
|
|
||||||||||
| Balanced reporting |
|
|
||||||||||
| Other substantive exploration data |
|
|
||||||||||
| Further work |
|
|
||||||||||
1 AgEq calculated using metal prices of USD $3,300/oz Au and $50/oz Ag where AgEq g/t = Ag g/t + (Au g/t x (Au price/Ag price) x (Au recovery/Ag recovery)) with metallurgical recoveries of 96% Au and 91% Ag.2 See ASX Announcement dated 19 August 2024, “MTH Drills 17.95 Metres at 5.16 g/t Gold and 78.0 g/t Silver”3 See ASX Announcement dated 28 August 2025, “MTH ACCELERATES EXPLORATION WITH NEW DRILLING AT TARGET 5”4 See Copalquin – 'Upgraded Target 1 MRE' section at the end of this announcement 5 See Announcement 5 December 2025, MITHRIL TO ACQUIRE THE LA DURA GOLD-SILVER PROPERTY6 See Announcement 25 February 2026, MITHRIL LIDAR STUDY REVEALS 1.5 KM TREND & HISTORIC MINES7 AuEq calculated using metal prices of USD $3,300/oz Au and $50/oz Ag where AuEq g/t = Au g/t + (Ag g/t x (Ag price/Au price) x (Ag recovery/Au recovery)) with metallurgical recoveries of 96% Au and 91% Ag.8 AgEq calculated using metal prices of USD $3,300/oz Au and $50/oz Ag where AgEq g/t = Ag g/t + (Au g/t x (Au price/Ag price) x (Au recovery/Ag recovery)) with metallurgical recoveries of 96% Au and 91% Ag.9 See announcement dated June 10, 2026, "Mithril Drills 4.01 g/t gold, 225 g/t silver over 7.25 m including 15.25 g/t gold, 533 g/t silver over 0.5 m at Target 1, Copalquin"10 see announcement dated April 9, 2026, "Mithril Confirms high-grade and widespread silver and gold at Target 3, Copalquin Project"11 See ASX announcement dated 25 February 2022, "Further Excellent Metallurgy Results – Copalquin District, Mexico"
To view the source version of this press release, please visit https://www.newsfilecorp.com/release/311734
VANCOUVER, BC / ACCESS Newswire / August 27, 2026 / Stillwater Critical Minerals Corp. (TSXV:PGE)(OTCQB:PGEZF)(FSE:J0G) ("Stillwater" or the "Company") is pleased to announce an updated and expanded Mineral Resource estimate (the "2026 MRE") for its flagship Stillwater West critical minerals project in Montana, USA. The updated estimate includes 805.1 million tonnes of Inferred Mineral Resources grading 0.34% total nickel equivalent ("NiTEq") (see Tables 1 and 2) containing 4.8 billion pounds ("Blbs") of nickel, copper and cobalt, and 7.4 million ounces ("Moz") of platinum, palladium, gold and rhodium in a base-case model using a 0.20% NiTEq cut-off grade. The resource also includes a further 29.4 million tonnes of Indicated Mineral Resources grading 0.38% NiTEq containing 190 million pounds ("Mlbs") of nickel, copper and cobalt, and 0.359 Moz of platinum, palladium, gold and rhodium. Higher cut-off grades at 0.35% and 0.50% NiTEq are also presented as a sensitivity representing higher-grade zones.
The 2026 MRE reflects a substantial advancement in the Company's understanding of the Stillwater West mineral system, incorporating additional drilling, robust verification of historical data, refined geological and structural interpretations supported by comprehensive geophysical survey coverage, and an updated geologic and resource model. The updated estimate provides a stronger technical foundation for continued resource expansion, planned metallurgical testing and mining studies to support the advancement of one of North America's largest undeveloped polymetallic critical mineral systems.
2026 Mineral Resource Estimate Highlights
-
Resource estimate comprises 29.4 million tonnes of Indicated and 805.1 million tonnes of Inferred Mineral Resources containing 3.01 Blbs nickel, 1.52 Blbs copper, 283 Mlbs cobalt, 2.28 Moz platinum, 3.97 Moz palladium, 864 thousand ounces ("Koz") gold, and 310 Koz rhodium at 0.20% NiTEq cut-off (see Tables 1 and 2 for grades and additional details).
-
First definition of an Indicated Mineral Resource, marking an important milestone in the advancement of the Stillwater West project and reflecting substantially increased geological confidence.
-
Significantly expanded resource estimate for priority critical minerals including nickel, copper, cobalt, and rhodium, making Stillwater West the largest known rhodium deposit in North America and the largest nickel and cobalt deposit in an active US mining district.
-
Expansion of Inferred chromium resource to 6.6 Blbs confirming the Stillwater complex as one of the only past producing and current significant resources in the United States. No economic or recovery assumptions have been made about chromium which co-occurs with the other metals, and it is not included in the NiTEq calculations.
-
Four zones are modeled across the central 10-kilometers of the project area, with the updated geological modelcombining the previously separate CZ and Central deposits at Iron Mountain.
Michael Rowley, President and CEO of Stillwater Critical Minerals, commented: "This updated Mineral Resource estimate marks an important step forward for Stillwater West. Beyond the substantial increase in the estimated tonnage and contained metal, the establishment of our first Indicated Mineral Resource and the continued refinement of our geological model significantly enhance our understanding of this large and evolving mineral system. The 2026 resource estimate provides a stronger technical foundation for advancing metallurgical studies, engineering and future economic evaluation, while reinforcing our belief that Stillwater West ranks among North America's most significant undeveloped polymetallic critical mineral projects."
Dr. Danie Grobler, Vice-President Exploration, commented: "The 2026 resource estimate reflects the integration of new drill results, historical data, structural interpretation, and geophysical information into an increasingly robust geological model. That work has significantly improved our understanding of the continuity and geometry of mineralization across the district, supporting the classification of the Company's first Indicated Mineral Resource and providing a stronger framework for potential future resource expansion, resource confidence category upgrades, and technical studies."
2026 Mineral Resource Estimate
TABLE 1 – Grade at Three NiTEq Cut-off Grades
Stillwater West Indicated and Inferred Mineral Resource Estimates, August 27, 2026
TABLE 2 – Contained Metal at Three NiTEq Cut-off Grades
Stillwater West Indicated and Inferred Mineral Resource Estimates, August 27, 2026
Notes to accompany Mineral Resources Estimates presented in Tables 1 and 2:
Mineral Resources are reported within a constraining pit shell using the 2014 CIM Definition Standards.
Mineral Resources have an effective date of August 27, 2026. The Qualified Person for the estimate is Mr. Timothy O. Kuhl, RM SME, of Mine Technical Services.
A NiTEq is used for reporting Mineral Resources. NiTEq base case cutoff is 0.20%. The NiTEq is determined based on metal prices of US$8.00/lb for Ni, US$4.50/lb for Cu, US$11.00/lb for Co, US$1250.00/oz for Pt, US$1250.00/oz for Pd, US$3000.00/oz for Au and US$6500/oz for Rh. Recoveries of 80% were used for Ni, Co, Pt, Pd, Au, Rh and the Cu recovery used was 85%. NiTEq% is calculated based on the above metal prices and recoveries, resulting in NiTEq = Ni% + (Cu% × 0.598) + (Co% × 1.375) + (Pt g/t × 0.228) + (Pd g/t × 0.228) + (Au g/t × 0.547) + (Rh g/t × 1.185).
Open pit mining is assumed. Assumptions used to develop pit shell include: mining cost of $2.50/t and a processing cost of $18/t of ore. The processing cost includes costs for G&A, smelter and shipping charges. A 50° pit slope is assumed.
Tonnage and grade estimates are in metric units.
Mineral Resource tonnage and contained metal have been rounded to reflect the accuracy of the estimate, and numbers may not add due to rounding.
Equivalent contained metal and grades do not include Cr.
There are no legal, political, environmental or other risks known to the Qualified Persons consider would materially affect the Mineral Resource estimates.
The 2026 MRE incorporates new drilling, selected historical drilling, refined geological interpretation and structural modelling. The estimate was prepared by Mr. Tim Kuhl of Mine Technical Services ("MTS"), an independent Qualified Person, in accordance with National Instrument 43-101. Mr. Kuhl and his team gained significant experience with Platreef-style mineralization during their time at Wood, AMEC Foster Wheeler, and AMEC and over the past two decades working under the late Dr. Harry Parker. This experience informed the approach applied to the thick mineralized zones of the Stillwater West project, where dynamic anisotropy search geostatistical techniques using locally varying anisotropy were applied across the different structural domains identified in the updated geological model. This is the first time this approach has been used at Stillwater West. There are no known legal, political, environmental or other risks that the Qualified Persons consider could materially affect the potential development of the Mineral Resources.
The updated estimate incorporates 14 new drill holes (5,781 meters) from the 2023 and 2025 drilling campaigns as well as historic drillholes not included in the previous Mineral Resource estimate as a result of detailed QA/QC review. Dr. Ted Eggleston, P.Geo., of MTS, a Qualified Person who is also independent of the Company, verified the current and historical assay and geological data through a detailed review of QA/QC information and original laboratory certificates. The Qualified Persons also conducted two field visits to the Stillwater drill sites and core facility. The Qualified Persons reviewed the historical metallurgical data and benchmarking information provided by the Company on analogue deposit metallurgical performance, and reviewed information provided by the Company on aspects of mineral claims, surface rights, royalties, permitting and environmental considerations. The Qualified Persons identified no material limitations in the data verification process that would affect the Mineral Resource estimate.
The results of the 2026 MRE show separate resource areas at Chrome Mountain and Iron Mountain, with the latter comprising the CZ-Central-HGR-Crescent mineralized system. Together, Chrome Mountain and Iron Mountain represent two large, polymetallic areas of mineralization that begin at surface. Figures 2 through 7 illustrate the extensive mineralization in these areas including areas with higher-grade zones. The 2026 drilling campaign is focused on extending the Chrome Mountain mineralization extent (see Figures 2, 3, 4, and 5) and joining the CZ-Central deposits with the HGR deposit at Iron Mountain (see Figures 2, 3, 4, and 6).
Advancing the Geological Model
The 2026 MRE represents the culmination of multiple exploration campaigns and a significantly improved understanding of the Stillwater West mineral system. The Company's technical team has progressively refined its geological model through the integration of tens of thousands of meters of drilling, detailed geological mapping, geophysical surveys and ongoing data validation and interpretation. The resulting model provides greater confidence in the continuity and geometry of mineralization across the district, supporting the estimate of the Company's first Indicated Mineral Resource and providing a stronger framework for future exploration, resource conversion and technical studies.
Key information used in the 2026 MRE includes:
-
Results from the 2023 and 2025 drill campaigns.
-
Validation and refinement of the Company's district-scale geological model.
-
Updated structural interpretation improving mineralized domain continuity supported by new drilling and multiple property wide geophysical surveys.
-
Metallurgical recovery assumptions based on historical testwork and benchmarked comparable deposit types.
-
Expanded rhodium sample database, updated estimation methodology and resource modelling.
Foundation for Future Development
The 2026 MRE also establishes the detailed grade-block model that will support the next phase of technical studies, including:
-
Future drill targeting and potential resource confidence category upgrades.
-
Implementation of metallurgical testing programs.
-
Mine planning and development scenario evaluations.
-
Continued community relations and engagement.
-
Evaluation of potential mid- to higher-grade zones that might be sequenced earlier in future economic studies.
As the Company advances Stillwater West toward development, this technical framework is expected to improve exploration efficiency while supporting the continued de-risking of one of North America's largest undeveloped polymetallic critical mineral systems.
Development Optionality
The 2026 MRE includes a substantial increase in higher-grade nickel-PGE-copper-cobalt-chromium mineralization, providing greater flexibility as the Company evaluates future potential development scenarios.
The enhanced higher-grade component broadens the range of engineering and mine planning alternatives available for evaluation, including the assessment of potential staged development approaches and early higher-grade sequencing opportunities within a larger district-scale development strategy.
Rhodium Resource Expansion
Recent drilling identified widespread rhodium mineralization at both Chrome Mountain and Iron Mountain. The 2026 MRE expands the project's contained rhodium metal content estimates, reinforcing Stillwater West as the largest known rhodium deposit in North America.
Rhodium is one of the world's rarest platinum group metals and is used in high-performance catalytic and industrial applications. In addition to rhodium, assay results at Stillwater West indicate co-occurrence of the rare platinum group metals iridium, osmium and ruthenium.
District-Scale Potential
While the 2026 MRE significantly expands the mineralization at Stillwater West, the area estimated occupies only a 10-kilometer portion of the Company's 32-kilometer-wide land position across the Stillwater Igneous Complex. Multiple large-scale geophysical and geological targets identified through recent exploration programs remain untested, providing substantial opportunities for future resource growth.
Priority exploration areas include:
-
Chrome Mountain expansion
-
Iron Mountain expansion, including the CZ-Central, HGR and Crescent deposits.
These areas provide opportunities to expand and upgrade known mineralized systems while also testing potential additional mineralized centers elsewhere across the district.
Stillwater West is located immediately adjacent to Sibanye-Stillwater's operating PGE mines and processing infrastructure in Montana and benefits from excellent access to transportation, power, a skilled workforce and other advantages associated with a long-established mining district. The project also aligns with growing U.S. initiatives to secure domestic supplies of nickel, copper, cobalt and platinum group metals that are increasingly important for energy, electrification and national security.
Upcoming Events
Company representatives will be attending the following events and look forward to discussing the 2026 resource estimate and upcoming catalysts:
Commodities Global Expo – Phoenix, AZ, USA, September 18-20, 2026.
Precious Metals Summit – Beaver Creek, CO, USA, September 22-25, 2026.
Better in Our Backyard – Minneapolis, MN, USA, September 29 – October 2, 2026.
AEMA Annual Meeting – Sparks, NV, USA, December 6-11, 2026.
Montana Mining Association Winter Meeting 2026 – Billings, MT, USA, December 8-9, 2026.
About Stillwater Critical Minerals Corp.
Stillwater Critical Minerals (TSX.V:PGE)(OTCQB:PGEZF)(FSE:J0G) is a mineral exploration and development company advancing its 100%-owned Stillwater West Ni-PGE-Cu-Co-Cr + Au project in the Stillwater mining district of Montana, USA. Stillwater West is directly adjacent to Sibanye-Stillwater's operating Stillwater mines and processing infrastructure, the only primary platinum group element-producing complex in the United States. An NI 43-101 Mineral Resource estimate released in August 2026 positions Stillwater West as one of the largest nickel and platinum group element resources in the United States and includes ten metals currently listed as critical. With strategic investments by Glencore and an experienced technical team with expertise in Bushveld- and Platreef-style systems, the Company is advancing Stillwater West through ongoing resource expansion, resource upgrades and technical studies.
Stillwater also holds a 49% interest in the high-grade Drayton-Black Lake-gold project adjacent to Nexgold Mining's development-stage Goliath Gold Complex in northwest Ontario, currently under an earn-in agreement with Heritage Mining, and the Kluane PGE-Ni-Cu-Co critical minerals project on trend with Nickel Creek Platinum's Wellgreen deposit in Canada's Yukon Territory. The Company also holds the Duke Island Cu-Ni-PGE property in Alaska and maintains a back-in right on the high-grade past-producing Yankee-Dundee in BC, following its sale in 2013.
FOR FURTHER INFORMATION, PLEASE CONTACT:
Michael Rowley, President, CEO & Director – Stillwater Critical Minerals
Email: info@criticalminerals.com Phone: (604) 357 4790
Web: http://criticalminerals.com Toll Free: (888) 432 0075
Qualified Persons
The Stillwater West Ni-PGE-Cu-Co + Au project 2026 Mineral Resource estimate was prepared by Timothy O. Kuhl, RM SME, and Dr. Ted Eggleston, Ph.D., RM SME, of Mine Technical Services, who are independent Qualified Persons, in accordance with the guidelines of the Canadian Securities Administrators' National Instrument 43-101 – Standards of Disclosure for Mineral Projects ("NI 43-101") with an effective date of August 27, 2026. Dr. Eggleston and Mr. Kuhl most recently visited the property on September 16, 2025. Dr. Eggleston and Mr. Kuhl reviewed and approved the technical content of this news release with respect to the 2026 Mineral Resource estimate. A technical report will be filed on SEDAR+ within 45 days of this news release.
Mr. Mike Ostenson, P.Geo., is the Company's Qualified Person for the purposes of National Instrument 43-101, and he has reviewed and approved the technical disclosure outside of the 2026 Mineral Resource estimate that is contained in this news release.
Forward-Looking Statements
This news release includes certain statements that may be deemed "forward-looking statements". All statements in this release, other than statements of historical facts including, without limitation, statements regarding potential mineralization, historic production, estimation of mineral resources, the realization of mineral resource estimates, interpretation of prior exploration and potential exploration results, the timing and success of exploration activities generally, the timing and results of future resource estimates, permitting timelines, metal prices and currency exchange rates, availability of capital, government regulation of exploration operations, environmental risks, reclamation, title, statements about expected results of operations, royalties, cash flows, financial position and future dividends, prospects, and future plans and objectives of the Company are forward-looking statements that involve various risks and uncertainties. Although Stillwater Critical Minerals believes the expectations expressed in such forward-looking statements are based on reasonable assumptions, such statements are not guarantees of future performance and actual results or developments may differ materially from those in the forward-looking statements. Forward-looking statements are based on a number of material factors and assumptions. Factors that could cause actual results to differ materially from those in forward-looking statements include failure to obtain necessary approvals, unsuccessful exploration results, unsuccessful operations, changes in project parameters as plans continue to be refined, results of future resource estimates, future metal prices, availability of capital and financing on acceptable terms, general economic, market or business conditions, risks associated with regulatory changes, defects in title, availability of personnel, materials and equipment on a timely basis, accidents or equipment breakdowns, uninsured risks, delays in receiving government approvals, unanticipated environmental impacts on operations and costs to remedy same and other exploration or other risks detailed herein and from time to time in the filings made by the Company with securities regulators. Readers are cautioned that mineral resources that are not mineral reserves do not have demonstrated economic viability. Mineral exploration, development of mines and mining operations is an inherently risky business. Accordingly, the actual events may differ materially from those projected in the forward-looking statements. For more information on Stillwater Critical Minerals and the risks and challenges of their businesses, investors should review their annual filings that are available at sedarplus.ca. Neither the TSX Venture Exchange nor its Regulation Services Provider (as that term is defined in the policies of the TSX Venture Exchange) accepts responsibility for the adequacy or accuracy of this release.
SOURCE: Stillwater Critical Minerals
View the original press release on ACCESS Newswire
Southern Copper Corporation’s SCCO copper production fell 3.5% in the second quarter of 2026, pushing the first-half 2026 production to decline 3.8% year-over-year to 461,206 tons due to a decrease in production at the company’s Peruvian operations. Despite the year-to-date fall in production, the company has slightly hiked its 2026 copper production outlook to 917,000 tons from the initially stated 910,000 tons. The figure, however, implies a 5% year-over-year decline. The downside will be caused by lower ore grades at the Cuajone and Peruvian mines. Southern Copper expects 2027 copper production to remain near the 2026 level. Tía María is expected to begin production in the second half of 2027 and lift total copper output to about 970,000 tons in 2028. The company then expects production to reach 1.06 million tons in 2029.Southern Copper maintains a strong long-term outlook with production expected to increase to 1.6 million tons by 2033 or 2034. To support this growth plan, the company intends to invest $20.5 billion over the next decade, with the bulk of the capital allocated to projects.The pipeline includes Tía María, Los Chancas and Michiquillay in Peru, along with El Pilar, El Arco and other projects in Mexico. The breadth of these projects gives Southern Copper multiple sources of organic production growth beyond current mine grades. Expected grade recovery at Toquepala and Cuajone should also add production after 2027.
Southern Copper Peers’ Production Performance & Outlook
Teck Resources Ltd TECK copper segment’s revenues surged 85% year over year, driven by higher copper prices and sales volumes. This pushed the company’s top line to $2.6 billion, marking a 78% year-over-year rise. However, Teck Resources' Red Dog production fell to 112,000 tons in the second quarter of 2026 from 136,600 tons a year earlier as grades declined in line with the mine plan. Nonetheless, Teck Resources maintains its 2026 copper production guidance of 455-530 thousand tons, whereas it produced 453.5 thousand tons in 2025. This will be driven by higher output at QB, Highland Valley Copper and Antamina. The long-term outlook for copper is positive as demand is expected to grow, partly driven by electric vehicles, renewable energy and infrastructure investments. Freeport-McMoRan Inc.’s FCX revenues declined 7.3% year over year to $7.03 billion in the second quarter of 2026. Freeport-McMoRan’s copper production fell 18.4% year over year to 786 million pounds in the reported quarter. Freeport-McMoRan’s copper sales volumes tumbled approximately 30% year over year in the second quarter to 710 million pounds. While the company’s third-quarter outlook for copper sales volumes of 750 million pounds indicates a sequential improvement, it still suggests a 23% year-over-year decline. The company, in April 2026, lowered its consolidated sales volume projections for 2026 to 3.1 billion pounds of copper from the prior view of 3.4 billion pounds due to an expected delay in achieving full ramp-up of the Grasberg Block Cave mine.
SCCO’s Price Performance, Valuations & Estimates
Southern Copper shares have gained 51.3% year to date compared with the Zacks Mining – Non Ferrous industry’s rise of 38.5%. During this time, the Basic Materials sector has risen 25.1% and the S&P 500 has rallied 12.6%.
Image Source: Zacks Investment Research
The Southern Copper stock is currently trading at a forward 12-month earnings multiple of 29.70X, which is a premium to the industry average of 25.45X.
Image Source: Zacks Investment Research
The Zacks Consensus Estimate for Southern Copper’s 2026 sales is $16.86 billion, indicating a 25.6% year-over-year jump. The consensus mark for the year’s earnings is pegged at $7.61 per share, suggesting a rally of 45.2%.
The Zacks Consensus Estimate for 2027 sales implies an 11.7% year-over-year dip. The same for earnings suggests a fall of 8.2%.Earnings estimates for 2026 have moved 0.1% south over the past 60 days, while the same for 2027 have moved up 0.3% over the past 60 days.
Image Source: Zacks Investment Research
The company currently carries a Zacks Rank #3 (Hold). You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Southern Copper Corporation (SCCO) : Free Stock Analysis Report
Freeport-McMoRan Inc. (FCX) : Free Stock Analysis Report
Teck Resources Ltd (TECK) : Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).
OTTAWA, ON, Aug. 26, 2026 /CNW/ — Northern Shield Resources Inc. ("Northern Shield" or the "Company") (TSXV: NRN) is pleased to report results of the 3D induced polarization ("IP") geophysical survey completed at the Company's flagship Root & Cellar Property ("Root & Cellar" or the "Property") on the Burin Peninsula of eastern Newfoundland. The Property is being explored for porphyry copper ± molybdenum, gold and tellurium, and for epithermal gold-silver-tellurium.
A review of the first 3D inversion modelling of chargeability and resistivity over a 4.6 km² grid covering the Creston copper porphyry target has been completed with four priority targets defined (Figure 1a and b). Three, IP-1, IP-2 and IP-3, appear to be connected, lying in the same zone of elevated chargeability. The fourth, IP-4, is a separate target to the north and possibly related to the Conquest gold zone.
Target IP-1
IP-1 is a near-surface chargeability response of approximately 9.5 mV/V coinciding with a bornite / possible chalcocite occurrence found during ground truthing of the target. It plunges shallowly to the SE into the IP-2 anomaly.
Targets IP-2 & 3
IP-2 extends from near surface to approximately 450 m depth with chargeability responses from 9.8 to 12.5 mV/V, and resistivity averaging approximately 6,875 ohm-m – the strongest combined response in the survey and the highest-priority target from the survey. IP-3 has a modelled chargeability of 9 to 11.2 mV/V at depths between 245 and 570 m and lies on the southern flank of a magnetic high that is interpreted as the porphyry intrusion that is driving the system (Figure 2). IP-2 and -3 combined, have a strike-length of approximately 1,000 m with a trend parallel to both the diatreme breccia complex and the copper (lead-zinc) mineralization in the neighbouring quarries. These anomalies are on the edge of the grid and hence their geometry and magnitude cannot be fully determined. They also lie outside the area of Northern Shield's soil geochemical sampling in an area that has not been evaluated by prior exploration.
Target IP-4
IP-4 measures approximately 240 m by 300 m in plan extending from near surface to approximately 400 m depth. It is characterised by chargeability of 8.5 to 9.0 mV/V coincident with resistivity averaging approximately 9,350 ohm-m, the most resistive area in the survey. This combination of elevated chargeability with strongly elevated resistivity is typical of disseminated sulphides hosted in quartz veins or silicified alteration.
Interpretation
The magnitude of the chargeability responses at Root & Cellar is consistent with expectations for the core of an alkalic porphyry system. Induced polarization responds to the surface area of sulphide rather than to copper grade, and alkalic mineralization is typically sulphide-poor and dominated by high-tenor copper minerals such as bornite and chalcocite. Higher chargeabilities in porphyry systems are usually attributed to the alteration cap that contains abundant disseminated pyrite and not the mineralized core.
"This survey has done exactly what we asked of it. It has taken a copper showing we could stand on and shown us that it is the near-surface expression of something considerably larger, extending several hundred metres to depth, to the southeast and still open. We now have a clear, prioritised basis for drilling. Also, beyond defining the copper target, the survey has identified an untested target that may be part of the Conquest Zone."
– Ian Bliss, President and CEO, Northern Shield
Next Steps
Ground truthing of the targets continues and a permit for 15 new drill hole collars has just been received, in addition to the 14 that remain permitted from last year. Nine of these new drill hole collar locations are in the main Conquest Zone.
The DasVision® 3D IP survey was completed by Abitibi Geophysics Inc. of Val-d'Or, Quebec. The survey used a distributed receiver array employing IRIS Instruments FullWaver technology in a pole-dipole configuration, with 100 m receiver dipole separations and current injections every 100 m over approximately 4.6 km². A total of 148 of 150 planned current injections were completed and 9,464 data points collected.
The technical information in this news release has been reviewed and approved by Mike Muggridge, P. Geo., an independent consultant and "Qualified Person" within the meaning of National Instrument 43-101 – Standards of Disclosure for Mineral Projects.
About Northern Shield Resources
Northern Shield Resources Inc. is a Canadian-based company, a leader in generating high-quality exploration targets, which views greenfield exploration as an opportunity to find a mineable, near surface deposit at relatively low cost. We implement a model driven exploration approach to reduce the risk associated with early-stage projects for ourselves, our shareholders, and the environment. This approach led us to option the Root & Cellar Property from a Newfoundland prospector, who discovered the copper mineralization, and then to its advancement to the large gold-silver-tellurium and porphyry copper system that it has become.
Forward-Looking Statements Advisory
This news release contains statements concerning the exploration plans, results and potential for porphyry copper, epithermal gold, nickel-copper-cobalt and other mineralization at the Company's Root & Cellar and Property, geological, geophysical and geometrical analyses of the properties and comparisons of the properties to known epithermal gold deposits and other expectations, plans, goals, objectives, assumptions, information or statements about future, conditions, results of exploration or performance that may constitute forward-looking statements or information under applicable securities legislation. Such forward-looking statements or information are based on a number of assumptions, which may prove to be incorrect.
Although Northern Shield believes that the expectations reflected in such forward-looking statements or information are reasonable, undue reliance should not be placed on forward looking statements because Northern Shield can give no assurance that such expectations will prove to be correct. Forward-looking statements or information are based on current expectations, estimates and projections that involve a number of risks and uncertainties which could cause actual results to differ materially from those anticipated by Northern Shield and described in the forward looking statements or information. These risks and uncertainties include, but are not limited to, risks associated with geological, geometrical and geophysical interpretation and analysis, the ability of Northern Shield to obtain financing, equipment, supplies and qualified personnel necessary to carry on exploration and the general risks and uncertainties involved in mineral exploration and analysis.
The forward-looking statements or information contained in this news release are made as of the date hereof and Northern Shield undertakes no obligation to update publicly or revise any forward looking statements or information, whether as a result of new information, future events or otherwise, unless so required by applicable securities laws.
Neither TSX Venture Exchange nor its Regulation Services Provider (as that term is defined in policies of the TSX Venture Exchange) accepts responsibility for the adequacy or accuracy of this release.
View original content to download multimedia: http://www.newswire.ca/en/releases/archive/August2026/26/c4383.html
OTTAWA, ON, Aug. 26, 2026 /CNW/ — Northern Shield Resources Inc. ("Northern Shield" or the "Company") (TSXV: NRN) is pleased to report results of the 3D induced polarization ("IP") geophysical survey completed at the Company's flagship Root & Cellar Property ("Root & Cellar" or the "Property") on the Burin Peninsula of eastern Newfoundland. The Property is being explored for porphyry copper ± molybdenum, gold and tellurium, and for epithermal gold-silver-tellurium.
A review of the first 3D inversion modelling of chargeability and resistivity over a 4.6 km² grid covering the Creston copper porphyry target has been completed with four priority targets defined (Figure 1a and b). Three, IP-1, IP-2 and IP-3, appear to be connected, lying in the same zone of elevated chargeability. The fourth, IP-4, is a separate target to the north and possibly related to the Conquest gold zone.
Target IP-1
IP-1 is a near-surface chargeability response of approximately 9.5 mV/V coinciding with a bornite / possible chalcocite occurrence found during ground truthing of the target. It plunges shallowly to the SE into the IP-2 anomaly.
Targets IP-2 & 3
IP-2 extends from near surface to approximately 450 m depth with chargeability responses from 9.8 to 12.5 mV/V, and resistivity averaging approximately 6,875 ohm-m – the strongest combined response in the survey and the highest-priority target from the survey. IP-3 has a modelled chargeability of 9 to 11.2 mV/V at depths between 245 and 570 m and lies on the southern flank of a magnetic high that is interpreted as the porphyry intrusion that is driving the system (Figure 2). IP-2 and -3 combined, have a strike-length of approximately 1,000 m with a trend parallel to both the diatreme breccia complex and the copper (lead-zinc) mineralization in the neighbouring quarries. These anomalies are on the edge of the grid and hence their geometry and magnitude cannot be fully determined. They also lie outside the area of Northern Shield's soil geochemical sampling in an area that has not been evaluated by prior exploration.
Target IP-4
IP-4 measures approximately 240 m by 300 m in plan extending from near surface to approximately 400 m depth. It is characterised by chargeability of 8.5 to 9.0 mV/V coincident with resistivity averaging approximately 9,350 ohm-m, the most resistive area in the survey. This combination of elevated chargeability with strongly elevated resistivity is typical of disseminated sulphides hosted in quartz veins or silicified alteration.
Interpretation
The magnitude of the chargeability responses at Root & Cellar is consistent with expectations for the core of an alkalic porphyry system. Induced polarization responds to the surface area of sulphide rather than to copper grade, and alkalic mineralization is typically sulphide-poor and dominated by high-tenor copper minerals such as bornite and chalcocite. Higher chargeabilities in porphyry systems are usually attributed to the alteration cap that contains abundant disseminated pyrite and not the mineralized core.
"This survey has done exactly what we asked of it. It has taken a copper showing we could stand on and shown us that it is the near-surface expression of something considerably larger, extending several hundred metres to depth, to the southeast and still open. We now have a clear, prioritised basis for drilling. Also, beyond defining the copper target, the survey has identified an untested target that may be part of the Conquest Zone."
– Ian Bliss, President and CEO, Northern Shield
Next Steps
Ground truthing of the targets continues and a permit for 15 new drill hole collars has just been received, in addition to the 14 that remain permitted from last year. Nine of these new drill hole collar locations are in the main Conquest Zone.
The DasVision® 3D IP survey was completed by Abitibi Geophysics Inc. of Val-d'Or, Quebec. The survey used a distributed receiver array employing IRIS Instruments FullWaver technology in a pole-dipole configuration, with 100 m receiver dipole separations and current injections every 100 m over approximately 4.6 km². A total of 148 of 150 planned current injections were completed and 9,464 data points collected.
The technical information in this news release has been reviewed and approved by Mike Muggridge, P. Geo., an independent consultant and "Qualified Person" within the meaning of National Instrument 43-101 – Standards of Disclosure for Mineral Projects.
About Northern Shield Resources
Northern Shield Resources Inc. is a Canadian-based company, a leader in generating high-quality exploration targets, which views greenfield exploration as an opportunity to find a mineable, near surface deposit at relatively low cost. We implement a model driven exploration approach to reduce the risk associated with early-stage projects for ourselves, our shareholders, and the environment. This approach led us to option the Root & Cellar Property from a Newfoundland prospector, who discovered the copper mineralization, and then to its advancement to the large gold-silver-tellurium and porphyry copper system that it has become.
Forward-Looking Statements Advisory
This news release contains statements concerning the exploration plans, results and potential for porphyry copper, epithermal gold, nickel-copper-cobalt and other mineralization at the Company's Root & Cellar and Property, geological, geophysical and geometrical analyses of the properties and comparisons of the properties to known epithermal gold deposits and other expectations, plans, goals, objectives, assumptions, information or statements about future, conditions, results of exploration or performance that may constitute forward-looking statements or information under applicable securities legislation. Such forward-looking statements or information are based on a number of assumptions, which may prove to be incorrect.
Although Northern Shield believes that the expectations reflected in such forward-looking statements or information are reasonable, undue reliance should not be placed on forward looking statements because Northern Shield can give no assurance that such expectations will prove to be correct. Forward-looking statements or information are based on current expectations, estimates and projections that involve a number of risks and uncertainties which could cause actual results to differ materially from those anticipated by Northern Shield and described in the forward looking statements or information. These risks and uncertainties include, but are not limited to, risks associated with geological, geometrical and geophysical interpretation and analysis, the ability of Northern Shield to obtain financing, equipment, supplies and qualified personnel necessary to carry on exploration and the general risks and uncertainties involved in mineral exploration and analysis.
The forward-looking statements or information contained in this news release are made as of the date hereof and Northern Shield undertakes no obligation to update publicly or revise any forward looking statements or information, whether as a result of new information, future events or otherwise, unless so required by applicable securities laws.
Neither TSX Venture Exchange nor its Regulation Services Provider (as that term is defined in policies of the TSX Venture Exchange) accepts responsibility for the adequacy or accuracy of this release.
View original content to download multimedia: http://www.newswire.ca/en/releases/archive/August2026/26/c4383.html
Find winning stocks in any market cycle. Join 7 million investors using Simply Wall St's investing ideas for FREE.
Southern Copper has delivered a very strong share price run over the past five years, yet its current valuation checks suggest the stock is not an obvious bargain at today's levels.
- Southern Copper has returned 367.8% over the past 5 years, which puts more attention on whether the current price still leaves room for attractive future returns.
- Valuation can be supported if the company continues to convert its asset base into reliable cash flows, while any pressure on project execution or capital spending needs may weigh on what investors are willing to pay for that growth.
- Southern Copper currently passes 0 of 6 valuation checks, which points to a stock that leans expensive rather than a clear value idea based on the broader assessment of price against fundamentals, according to this 0/6 score.
The issue now is whether Southern Copper's recent share price strength already reflects most of the good news that investors are hoping for.
Is Southern Copper Getting Expensive on Earnings?
The P/E ratio is a useful way to think about what investors are paying today for each dollar of Southern Copper's earnings. It ties the share price directly to the company’s current profit base.
Right now Southern Copper trades on a P/E of 32.8x. That is above the broader metals and mining industry average of 21.1x and also above the peer group average of 26.5x. The fair multiple estimated for the stock is 23.0x, which is materially lower than where the market values it today. This gap suggests investors are currently willing to pay a premium for Southern Copper relative to both sector benchmarks and the modelled range that factors in its size, margins and risk profile.
On this P/E basis, Southern Copper stock currently screens as overvalued compared with both its industry and the modelled fair multiple.
NYSE:SCCO P/E Ratio as at Aug 2026
See what the numbers say about this price — find out in our valuation breakdown.
The Southern Copper Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the valuation puzzle around Southern Copper leaves off and explain which assumptions on growth, margins and earnings would need to hold for the stock to be worth much more or much less than today’s price on the Community page. Each narrative is framed as a thesis about Southern Copper's business that can be tracked over time, rather than a one off fair value snapshot.
Community views on Southern Copper sit at opposite ends of the valuation spectrum. This gives you two very different scenarios to weigh.
Bull case: roughly fairly valued
"The expanding pipeline of major brownfield and greenfield projects, specifically Tía María and Los Chancas, positions Southern Copper for significant production growth beginning in 2027…"
Read the full Bull Case to see why Southern Copper could be undervalued
Bear case: 71% overvalued
"The anticipated surplus of 100,000 tons of copper in 2024 could pressure copper prices, negatively impacting revenue, especially if demand from key consumers like China remains weak despite expected economic measures…"
Read the full Bear Case to see why Southern Copper could be overvalued
Do you think there's more to the story for Southern Copper? Head over to our Community to see what others are saying!
The Bottom Line
Southern Copper now screens as overvalued on simple earnings multiples, and the broader valuation checks point in the same direction rather than flagging a clear discount. The recent share price move means expectations around project delivery, capital spending and copper market conditions are already doing a lot of work in the current valuation. The crux for you as an investor is whether Southern Copper can translate its project pipeline into resilient cash flows without meaningful execution setbacks, or whether any stumble leaves today’s premium looking too full.
This article by Simply Wall St is general in nature. We provide commentary based on historical datan and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or yourn financial situation. We aim to bring you long-term focused analysis driven by fundamental data.n Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material.n Simply Wall St has no position in any stocks mentioned.
Companies discussed in this article include SCCO.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com
Announces it has taken the necessary steps and completed key planning to pursue an uplist of its securities to the Nasdaq Capital Market. The Company is targeting completion of the uplist in 2026. Ares Strategic Mining Inc shares C.ARS are trading off $0.01 at $0.38.
Read:
- Gold Is at Record Highs and the Money Is Chasing the Drill Bit. This Junior Just Aimed Eight Holes at an Untested Brazilian Gold Core
- The Abitibi Belt's Next Gold Story May Already Be in the Ground. This Silver Miner Just Started Looking.
- Greenland Mines Lands a Site Team at Sarfartoq Within Days of Signing, Setting Up a 2026 Rare Earth Field Program
- Quantum Secure Encryption Scales Commercial Deployment as U.S. Pours Billions Into Quantum Computing
- The $1 Trillion Data Problem Quantum Computing Is About to Make Worse
VANCOUVER, BC / ACCESS Newswire / August 25, 2026 / Faraday Copper Corp. ("Faraday" or the "Company") (TSX:FDY)(OTCQX:CPPKF) is pleased to announce that at the special meeting (the "Meeting") of shareholders of the Company (the "Shareholders") held today, the Shareholders overwhelmingly voted to approve the share issuance resolution (the "Share Issuance Resolution") in connection with the previously announced acquisition of the San Manuel project (the "Transaction") from a wholly owned subsidiary of BHP Group Limited ("BHP").
The Share Issuance Resolution required approval by the affirmative vote of a simple majority of the votes cast at the Meeting by disinterested Shareholders. At the Meeting, 188,256,206 common shares were voted, representing 64.32% of the Company's issued and outstanding common shares (excluding common shares beneficially owned, or over which control or direction is exercised, by BHP or its subsidiaries were not counted in determining whether requisite shareholder approval has been obtained). Detailed results of the Meeting are set out below and filed on SEDAR+ at www.sedarplus.ca.
The voting results for the Share Issuance Resolution are set out below:
|
Votes For |
% Votes For |
Votes Against |
% Votes Against |
|
|
Approval of Share Issuance Resolution |
188,209,061 |
99.97% |
47,145 |
0.03% |
The Transaction remains subject to certain customary closing conditions and is expected to close by the end of the third quarter of 2026.
Satisfaction of Investment Canada Act Condition
Faraday is also pleased to confirm that the Investment Canada Act closing condition under the Transaction has now been satisfied.
About Faraday Copper
Faraday Copper is an exploration company focused on advancing its flagship copper project in Arizona, U.S. The Copper Creek Project is one of the largest undeveloped copper projects in North America with significant district scale exploration potential. Faraday has entered into a definitive purchase and sale agreement with a wholly owned subsidiary of BHP Group for the acquisition of BHP's San Manuel Project, adjacent to the Copper Creek Project. Faraday is well-funded to deliver on its key milestones and benefits from a management team and board of directors with senior mining company experience and expertise. Faraday trades on the TSX under the symbol "FDY".
For additional information please contact:
Stacey Pavlova, CFAVice President, Investor Relations & CommunicationsFaraday Copper Corp.E-mail: info@faradaycopper.comWebsite: www.faradaycopper.com
To receive news releases by e-mail, please register using the Faraday website at www.faradaycopper.com.
Cautionary Note on Forward Looking Statements
Some of the statements in this news release, other than statements of historical fact, are "forward-looking statements" and are based on the opinions and estimates of management as of the date such statements are made and are necessarily based on estimates and assumptions that are inherently subject to known and unknown risks, uncertainties and other factors that may cause actual results, level of activity, performance or achievements of Faraday to be materially different from those expressed or implied by such forward-looking statements. Forward‑looking statements in this news release include, without limitation, statements relating to the completion and timing of the Transaction and the parties' ability to satisfy the remaining conditions to the closing of the Transaction.
Although Faraday believes the expectations expressed in such forward-looking statements are based on reasonable assumptions, such statements should not be in any way construed as guarantees of future performance and actual results or developments may differ materially. Accordingly, readers should not place undue reliance on forward-looking statements or information.
Factors that could cause actual results to differ materially from those in forward-looking statements include without limitation: market prices for metals; the conclusions of detailed feasibility and technical analyses; lower than expected grades and quantities of mineral resources; receipt of regulatory approval; receipt of shareholder approval; mining rates and recovery rates; significant capital requirements; price volatility in the spot and forward markets for commodities; fluctuations in rates of exchange; taxation; controls, regulations and political or economic developments in the countries in which Faraday does or may carry on business; the speculative nature of mineral exploration and development, competition; loss of key employees; rising costs of labour, supplies, fuel and equipment; actual results of current exploration or reclamation activities; accidents; labour disputes; defective title to mineral claims or property or contests over claims to mineral properties; unexpected delays and costs inherent to consulting and accommodating rights of Indigenous peoples and other groups; risks, uncertainties and unanticipated delays associated with obtaining and maintaining necessary licenses, permits and authorizations and complying with permitting requirements, including those associated with the Copper Creek property; and uncertainties with respect to any future acquisitions by Faraday. In addition, there are risks and hazards associated with the business of mineral exploration, development and mining, including environmental events and hazards, industrial accidents, unusual or unexpected formations, pressures, cave-ins, flooding and the risk of inadequate insurance or inability to obtain insurance to cover these risks as well as "Risk Factors" included in Faraday's disclosure documents filed on and available at www.sedarplus.ca.
SOURCE: Faraday Copper Corp.
View the original press release on ACCESS Newswire
VANCOUVER, B.C. – August 25, 2026 (NEWMEDIAWIRE) – Ares Strategic Mining Inc. (CSE: ARS) (OTCQX: ARSMF) (FRA: N8I1) ("Ares" or the "Company") is pleased to announce that it has taken the necessary steps and completed key planning to pursue an uplist of its securities to the Nasdaq Capital Market. The Company is targeting completion of the uplist in 2026.
nn
Company Targets NASDAQ Capital Market Listing in 2026, Enhancing Accessibility for U.S. Institutional and Retail Investors and Avoiding Rollbacks for Canadian Shareholders
n
This initiative responds directly to feedback from potential institutional investors whose brokerages currently restrict trading in OTC securities, as well as the practical challenges some existing U.S. shareholders have experienced when seeking to exercise warrants. By moving to Nasdaq, Ares expects to unlock meaningfully higher trading volume, broaden its investor base, and deliver improved accessibility and liquidity for both current and future shareholders.
n
Sponsored American Depositary Share Program with BNY
n
To facilitate the Nasdaq listing, Ares is establishing a sponsored American Depositary Share ("ADS") program with The Bank of New York Mellon ("BNY") acting as depositary. On July 17, 2026, Ares and BNY entered into an agreement addressing the establishment, administration, and maintenance of the program.
n
The securities intended to be publicly offered and listed on the Nasdaq Capital Market will be American Depositary Shares. Each ADS will represent a fixed number of common shares of the Company. The final ADS-to-common-share ratio will be determined in consultation with BNY, the underwriters, Nasdaq, and the Company's legal and financial advisers. The ratio will be selected with regard to the expected offering price, the prevailing Canadian trading price, foreign-exchange rates, the anticipated number of ADSs to be offered and outstanding, and the applicable Nasdaq distribution and bid-price requirements.
n
The common shares underlying the ADSs will be deposited with BNY or its Canadian custodian. As the Depositary Bank for the Ares ADS program, BNY will administer the program, including, but not limited to, the issuance and cancellation of ADSs, recordkeeping, settlements, distributions, and shareholder communications, in accordance with the registration statement to be filed and subject to applicable law, fees and taxes.
n
Capital will be raised when Ares issues the underlying common shares in the public offering and BNY issues the corresponding ADSs to the underwriters. Subsequent exchanges of outstanding common shares for ADSs, or ADSs for common shares, will generally change only the form in which the securities are held, without altering the Company's total outstanding share capital.
n
Conditions to Completion
n
Completion of the establishment of Ares' ADS program remains subject to finalization and execution of the Form F-6 Registration Statement which includes the Deposit Agreement, establishment of the ADS ratio completion of the Company's Form F-10 and prospectus-supplement process, DTC and CUSIP arrangements, Nasdaq approval, and satisfaction of the conditions to closing of the underwritten offering. Accordingly, the execution of the BNY agreement should not be interpreted as confirmation that the ADS facility is already effective or that Nasdaq has approved the listing.
n
Looking Ahead
n
James Walker, President and Chief Executive Officer of Ares Strategic Mining, commented: "Moving to Nasdaq is a natural and exciting next step for Ares. We have built a fully permitted domestic fluorspar operation in Utah, and secured meaningful U.S. government relationships and contracts. The U.S. listing on Nasdaq supported by a sponsored ADS program with BNY, is designed to open the door for a broader universe of institutional and retail investors who have told us they want to participate but currently face brokerage or warrant-exercise barriers on the OTC market. We are targeting September 30th, 2026, as our completion date and are working diligently with our advisers, underwriters, and BNY to bring this milestone across the finish line. This is about making Ares more accessible, more liquid, and better positioned for the growth chapter that lies ahead."
n
ABOUT ARES STRATEGIC MINING
n
Ares Strategic Mining Inc. is the only domestic fluorspar producer in the United States and is developing a vertically integrated critical minerals platform through its Lost Sheep Mine and processing facilities in Utah. The Company aims to become a significant supplier of high-grade fluorspar to North American markets, supporting industries vital to modern technology and infrastructure.
n
Lost Sheep Fluorspar Project – Delta, Utah
n
100% owned – 5,982 acres – 302 Claims
n
Located in the Spor Mountain area, Juab County, Utah, approximately 214 km south-west of Salt Lake City.
n
Fully Permitted – including mining permits.
n
NI 43-101 Technical Report identified extensive high-grade fluorspar with low levels of impurities.
n
Mining plan approved by BLM.
n
ON BEHALF OF THE BOARD OF DIRECTORS OF ARES STRATEGIC MINING INC.James WalkerChief Executive Officer and PresidentFor further information, please contact James Walker by email at info@aresmining.com
n
DISCLOSURE AND FORWARD-LOOKING STATEMENTS:
n
Companies typically rely on comprehensive feasibility reports on mineral reserve estimates to reduce the risks and uncertainties associated with a production decision. Historically, situations where the issuer decides to put a mineral project into production without first establishing mineral reserves supported by a technical report and completing a feasibility study have a higher risk of economic or technical failure, though some industrial mineral ventures are relatively simple operations with low levels of investment and risk, where the operating entity has determined that a formal prefeasibility or feasibility study in conformance with NI 43-101 and 43-101 CP is not required for a production decision. Based on historical engineering work, geological reports, historical production data and current engineering work completed or in the process by Ares, the Company intends to move forward with the development of its Utah asset.
n
Certain information in this news release may contain forward-looking statements that involve substantial known and unknown risks and uncertainties. Forward-looking statements are often identified by terms such as "will", "may", "should", "anticipate", "expects" and similar expressions. All statements other than statements of historical fact included in this news release are forward-looking statements that involve risks and uncertainties. There can be no assurance that such statements will prove to be accurate and actual results and future events could differ materially from those anticipated in such statements. Important factors that could cause actual results to differ materially from the Company's expectations include the failure to satisfy the conditions of the relevant securities exchange(s), the failure to complete the ADS program or Nasdaq listing on the expected timeline or at all, market conditions, regulatory approvals, and other risks detailed from time to time in the filings made by the Company with securities regulators. The reader is cautioned that assumptions used in the preparation of any forward-looking information may prove to be incorrect. Events or circumstances may cause actual results to differ materially from those predicted, as a result of numerous known and unknown risks, uncertainties, and other factors, many of which are beyond the control of the Company. The reader is cautioned not to place undue reliance on any forward-looking information. Such information, although considered reasonable by management at the time of preparation, may prove to be incorrect and actual results may differ materially from those anticipated. Forward-looking statements contained in this news release are expressly qualified by this cautionary statement. The forward-looking statements contained in this news release are made as of the date of this news release and the Company disclaims any intention or obligation to update or revise such information, except as required by applicable law.
View the original release on www.newmediawire.com
If you would like to receive our free newsletter via email, simply enter your email address below & click subscribe.
 Follow us on Twitter
 Become our facebook fan
CONNECT WITH US
Tweets
Tweet with hash tag #miningfeeds or @miningfeeds and your tweets will be displayed across this site.
MOST ACTIVE MINING STOCKS
Daily Gainers
 Midlands Minerals Corp. |
MEX.V | +66.88% |
| GoviEx Uranium Inc. |
GXU.V | +42.86% |
 Mount Burgess Mining NL |
MTB.AX | +33.33% |
| Tsodilo Resources Ltd. |
TSD.V | +33.33% |
| Casa Minerals Inc. |
CASA.V | +30.00% |
| Cascadero Copper Corp. |
CCD.V | +25.00% |
| Extract Resources Ltd. |
EXT.AX | +25.00% |
| Poseidon Nickel Limited |
POS.AX | +25.00% |
| Iron Road Limited |
IRD.AX | +22.22% |
| Carbine Resources Limited |
CRB.AX | +20.00% |