TORONTO, Jan. 20, 2026 /CNW/ – Bravo Mining Corp. (TSXV: BRVO) (OTCQX: BRVMF) ("Bravo" or the "Company") announces that it has closed the previously announced public offering (the "Offering") of common shares of the Company (the "Common Shares"). Pursuant to the Offering, the Company has issued 19,607,500 Common Shares at a price of C$4.40 per Common Share for gross proceeds of C$86,273,000, which includes the exercise in full of the over-allotment option granted to the Underwriters (as defined below). The Offering was co-led by BMO Capital Markets and National Bank Capital Markets on behalf of a syndicate that included Beacon Securities Limited and Canaccord Genuity Corp. (collectively, the "Underwriters").
In connection with the Offering, the Company has paid the Underwriters a cash commission in the aggregate amount of $4,313,650 equal to 5.0% of the gross proceeds of the Offering.
The Offering was made by way of a prospectus supplement dated January 15, 2026 to the Company's existing Canadian base shelf prospectus dated December 22, 2025, in the United States on a private placement basis pursuant to exemptions from the registration requirements of the United States Securities Act of 1933, as amended (the "U.S. Securities Act"), and in certain other jurisdictions outside of Canada and the United States.
The Common Shares have not been and will not be registered under the U.S. Securities Act and may not be offered or sold in the United States absent registration or an applicable exemption from the registration requirements under the U.S. Securities Act and applicable state securities laws. This news release shall not constitute an offer to sell or the solicitation of an offer to buy nor shall there be any sale of any securities in any jurisdiction in which such offer, solicitation or sale would be unlawful.
About Bravo Mining Corp.
Bravo is a Canadian and Brazil-based mineral exploration and development company focused on advancing its PGM and copper-gold Luanga Project in the Carajás Mineral Province, Pará State, Brazil.
Bravo is one of the most active explorers in Carajás. The team, comprising of local and international geologists, has a proven track record of PGM, nickel, and copper discoveries in the region. They have successfully taken a past IOCG greenfield project from discovery to development and production in the Carajás.
The Luanga Project is situated on mature freehold farming land and benefits from being located close to operating mines and a mining-experienced workforce, with excellent access and proximity to existing infrastructure, including road, rail, and hydroelectric grid power. Bravo's current Environmental, Social and Governance activities include planting more than 50,000 high-value trees in and around the project area and hiring and contracting locally.
Neither TSX Venture Exchange nor its Regulation Services Provider (as that term is defined in policies of the TSX Venture Exchange) accepts responsibility for the adequacy or accuracy of this release.
View original content to download multimedia: http://www.newswire.ca/en/releases/archive/January2026/20/c7613.html
As the U.S. stock market navigates a landscape of mixed bank earnings and fluctuating economic data, major indices have recently edged lower, while gold and silver reach new heights. In such an environment, identifying stocks that may be trading below their intrinsic value can present potential opportunities for investors seeking to capitalize on market inefficiencies.
Top 10 Undervalued Stocks Based On Cash Flows In The United States
| Name | Current Price | Fair Value (Est) | Discount (Est) |
| Workiva (WK) | $84.75 | $166.67 | 49.2% |
| WesBanco (WSBC) | $34.58 | $68.86 | 49.8% |
| UMB Financial (UMBF) | $123.30 | $243.75 | 49.4% |
| Motorcar Parts of America (MPAA) | $13.60 | $26.25 | 48.2% |
| Krystal Biotech (KRYS) | $282.01 | $555.39 | 49.2% |
| Investar Holding (ISTR) | $27.62 | $53.60 | 48.5% |
| Horizon Bancorp (HBNC) | $17.65 | $34.30 | 48.5% |
| Fifth Third Bancorp (FITB) | $49.02 | $95.11 | 48.5% |
| Dime Community Bancshares (DCOM) | $31.13 | $60.91 | 48.9% |
| Aptiv (APTV) | $82.61 | $163.62 | 49.5% |
We’ll examine a selection from our screener results.
Overview: The Kroger Co. operates as a food and drug retailer in the United States with a market cap of approximately $39.53 billion.
Operations: Kroger generates revenue primarily through its retail operations, amounting to $147.23 billion.
Estimated Discount To Fair Value: 22.2%
Kroger’s stock appears undervalued based on discounted cash flow analysis, trading over 20% below its estimated fair value of US$80.33. Despite slower revenue growth expectations compared to the market, Kroger’s earnings are forecasted to grow significantly at 29.7% annually, outpacing the broader market. Recent strategic moves include a significant share buyback plan and expanded delivery partnerships with Uber Eats and Instacart, potentially enhancing customer reach and operational efficiency amidst ongoing legal challenges and regulatory scrutiny.
- Upon reviewing our latest growth report, Kroger’s projected financial performance appears quite optimistic.
- Click to explore a detailed breakdown of our findings in Kroger’s balance sheet health report.
KR Discounted Cash Flow as at Jan 2026Lazard
Overview: Lazard, Inc. is a financial advisory and asset management firm with operations across the Americas, Europe, the Middle East, Africa, and the Asia Pacific, holding a market cap of approximately $4.92 billion.
Operations: Lazard, Inc. generates revenue primarily from its Financial Advisory segment at $1.81 billion and Asset Management segment at $1.22 billion.
Estimated Discount To Fair Value: 30.3%
Lazard’s stock is trading over 20% below its estimated fair value of US$77.11, highlighting potential undervaluation based on cash flows. While the company faces unstable dividend history and high debt levels, its earnings are projected to grow significantly at 29.9% annually, surpassing market averages. Recent leadership appointments in the Global Industrials Group may bolster strategic advisory capabilities across key sectors, potentially supporting revenue growth forecasts of 12.5% per year amidst a competitive landscape.
- Insights from our recent growth report point to a promising forecast for Lazard’s business outlook.
- Navigate through the intricacies of Lazard with our comprehensive financial health report here.
LAZ Discounted Cash Flow as at Jan 2026Sociedad Química y Minera de Chile
Overview: Sociedad Química y Minera de Chile S.A. is a global producer and seller of specialty plant nutrients and iodine derivatives, with a market cap of approximately $23.76 billion.
Operations: The company generates revenue from several segments, including Lithium and Derivatives at $2.08 billion, Iodine and Derivatives at $996.40 million, Specialty Plant Nutrition at $957.03 million, Potassium at $182.60 million, and Industrial Chemicals at $74.26 million.
Estimated Discount To Fair Value: 10.5%
Sociedad Química y Minera de Chile trades at US$79.58, about 10.5% below its fair value estimate of US$88.93, suggesting potential undervaluation based on cash flows. Despite high debt levels and a dividend not well covered by earnings, the company has returned to profitability with earnings projected to grow significantly at 28.6% annually, outpacing market averages. Recent strategic alliances in China may enhance long-term growth prospects amidst steady production and sales guidance for 2025.
- Our comprehensive growth report raises the possibility that Sociedad Química y Minera de Chile is poised for substantial financial growth.
- Dive into the specifics of Sociedad Química y Minera de Chile here with our thorough financial health report.
SQM Discounted Cash Flow as at Jan 2026Seize The Opportunity
- Discover the full array of 185 Undervalued US Stocks Based On Cash Flows right here.
- Are any of these part of your asset mix? Tap into the analytical power of Simply Wall St’s portfolio to get a 360-degree view on how they’re shaping up.
- Simply Wall St is your key to unlocking global market trends, a free user-friendly app for forward-thinking investors.
Contemplating Other Strategies?
- Explore high-performing small cap companies that haven’t yet garnered significant analyst attention.
- Diversify your portfolio with solid dividend payers offering reliable income streams to weather potential market turbulence.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
This article by Simply Wall St is general in nature. We provide commentary based on historical data
and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice.
It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your
financial situation. We aim to bring you long-term focused analysis driven by fundamental data.
Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material.
Simply Wall St has no position in any stocks mentioned.
Companies discussed in this article include KR LAZ and SQM.
This article was originally published by Simply Wall St.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com
Why Sociedad Química y Minera de Chile (NYSE:SQM) is on investors’ radar
Sociedad Química y Minera de Chile (NYSE:SQM) has drawn attention after a strong share price move, with the stock up 2.7% over the past day and 10.8% over the past week.
Over the past month the stock shows a 28.0% return, while the past 3 months add up to an 87.2% gain. This makes recent performance a key focus for investors assessing what is driving sentiment.
See our latest analysis for Sociedad Química y Minera de Chile.
Looking beyond the recent jump, the stock shows building momentum, with an 87.2% 3 month share price return and a 106.6% 1 year total shareholder return. This points to a sharp shift in how the market is pricing Sociedad Química y Minera de Chile’s prospects and risks.
If SQM’s move has you thinking about what else is on the move, this could be a good moment to widen your search with fast growing stocks with high insider ownership.
With SQM up strongly over the past year and trading at a small intrinsic discount of about 6%, the key question is whether the recent optimism leaves any mispricing or if the market already reflects future growth.
Most Popular Narrative: 35.4% Overvalued
Compared with the narrative fair value of about US$61.44, Sociedad Química y Minera de Chile’s last close at US$83.18 implies a rich valuation that leans heavily on future execution.
Strong demand growth in electric vehicles (EVs) and renewable energy storage, particularly in China and Europe, is driving a sustained recovery in lithium prices and providing visible upside to SQM’s revenues and margins as sales volumes are guided to increase by at least 10% in 2025.
Curious what kind of revenue and margin profile could justify a higher future earnings base and still assume a lower P/E multiple than many peers? The narrative sets out a detailed earnings path, specific margin expansion, and a discount rate that together underpin that fair value. The tension between ambitious growth and a compressed future multiple is where the real story sits.
Result: Fair Value of $61.44 (OVERVALUED)
Have a read of the narrative in full and understand what’s behind the forecasts.
However, lithium price volatility and the unresolved Codelco joint venture terms could still upend these assumptions, potentially shifting earnings power and the valuation story quite quickly.
Find out about the key risks to this Sociedad Química y Minera de Chile narrative.
Another View: DCF Points in a Different Direction
While the narrative fair value of about US$61.44 suggests Sociedad Química y Minera de Chile is overvalued at US$83.18, our DCF model paints a different picture, with fair value at roughly US$88.76 and the shares trading at a 6.3% discount. Which set of assumptions do you find more realistic?
Look into how the SWS DCF model arrives at its fair value.
SQM Discounted Cash Flow as at Jan 2026
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Sociedad Química y Minera de Chile for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 884 undervalued stocks based on their cash flows. If you save a screener we even alert you when new companies match – so you never miss a potential opportunity.
Build Your Own Sociedad Química y Minera de Chile Narrative
If you see the data differently or simply prefer to test your own assumptions, you can put together a full narrative in just a few minutes with Do it your way.
A great starting point for your Sociedad Química y Minera de Chile research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
Looking for more investment ideas?
If SQM has caught your eye, do not stop there; broaden your watchlist with a few focused stock ideas that could sharpen your next move.
-
Spot opportunities in smaller names by scanning these 3531 penny stocks with strong financials that pair lower share prices with more robust financial profiles.
-
Position yourself in the AI shift by checking out these 25 AI penny stocks targeting companies tied to artificial intelligence themes.
-
Hunt for value by reviewing these 884 undervalued stocks based on cash flows that screen for stocks pricing in less optimistic cash flow assumptions.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Companies discussed in this article include SQM.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com
Key Insights
- The projected fair value for FMC is US$26.28 based on 2 Stage Free Cash Flow to Equity
- Current share price of US$15.14 suggests FMC is potentially 42% undervalued
- The US$21.21 analyst price target for FMC is 19% less than our estimate of fair value
Today we will run through one way of estimating the intrinsic value of FMC Corporation (NYSE:FMC) by taking the expected future cash flows and discounting them to their present value. This will be done using the Discounted Cash Flow (DCF) model. There's really not all that much to it, even though it might appear quite complex.
Remember though, that there are many ways to estimate a company's value, and a DCF is just one method. If you want to learn more about discounted cash flow, the rationale behind this calculation can be read in detail in the Simply Wall St analysis model.
The Model
We are going to use a two-stage DCF model, which, as the name states, takes into account two stages of growth. The first stage is generally a higher growth period which levels off heading towards the terminal value, captured in the second 'steady growth' period. To begin with, we have to get estimates of the next ten years of cash flows. Where possible we use analyst estimates, but when these aren't available we extrapolate the previous free cash flow (FCF) from the last estimate or reported value. We assume companies with shrinking free cash flow will slow their rate of shrinkage, and that companies with growing free cash flow will see their growth rate slow, over this period. We do this to reflect that growth tends to slow more in the early years than it does in later years.
A DCF is all about the idea that a dollar in the future is less valuable than a dollar today, so we discount the value of these future cash flows to their estimated value in today's dollars:
10-year free cash flow (FCF) estimate
| 2026 | 2027 | 2028 | 2029 | 2030 | 2031 | 2032 | 2033 | 2034 | 2035 | |
| Levered FCF ($, Millions) | US$285.0m | US$354.1m | US$295.0m | US$330.0m | US$338.8m | US$348.4m | US$358.7m | US$369.6m | US$381.2m | US$393.2m |
| Growth Rate Estimate Source | Analyst x5 | Analyst x4 | Analyst x1 | Analyst x1 | Est @ 2.65% | Est @ 2.84% | Est @ 2.96% | Est @ 3.05% | Est @ 3.11% | Est @ 3.16% |
| Present Value ($, Millions) Discounted @ 12% | US$254 | US$281 | US$208 | US$207 | US$190 | US$174 | US$159 | US$146 | US$134 | US$123 |
("Est" = FCF growth rate estimated by Simply Wall St)Present Value of 10-year Cash Flow (PVCF) = US$1.9b
After calculating the present value of future cash flows in the initial 10-year period, we need to calculate the Terminal Value, which accounts for all future cash flows beyond the first stage. The Gordon Growth formula is used to calculate Terminal Value at a future annual growth rate equal to the 5-year average of the 10-year government bond yield of 3.3%. We discount the terminal cash flows to today's value at a cost of equity of 12%.
Terminal Value (TV)= FCF2035 × (1 + g) ÷ (r – g) = US$393m× (1 + 3.3%) ÷ (12%– 3.3%) = US$4.5b
Present Value of Terminal Value (PVTV)= TV / (1 + r)10= US$4.5b÷ ( 1 + 12%)10= US$1.4b
The total value is the sum of cash flows for the next ten years plus the discounted terminal value, which results in the Total Equity Value, which in this case is US$3.3b. The last step is to then divide the equity value by the number of shares outstanding. Relative to the current share price of US$15.1, the company appears quite undervalued at a 42% discount to where the stock price trades currently. Remember though, that this is just an approximate valuation, and like any complex formula – garbage in, garbage out.
NYSE:FMC Discounted Cash Flow January 15th 2026 Important Assumptions
The calculation above is very dependent on two assumptions. The first is the discount rate and the other is the cash flows. You don't have to agree with these inputs, I recommend redoing the calculations yourself and playing with them. The DCF also does not consider the possible cyclicality of an industry, or a company's future capital requirements, so it does not give a full picture of a company's potential performance. Given that we are looking at FMC as potential shareholders, the cost of equity is used as the discount rate, rather than the cost of capital (or weighted average cost of capital, WACC) which accounts for debt. In this calculation we've used 12%, which is based on a levered beta of 1.958. Beta is a measure of a stock's volatility, compared to the market as a whole. We get our beta from the industry average beta of globally comparable companies, with an imposed limit between 0.8 and 2.0, which is a reasonable range for a stable business.
View our latest analysis for FMC
SWOT Analysis for FMCStrength
- Debt is well covered by .
Weakness
- Interest payments on debt are not well covered.
- Dividend is low compared to the top 25% of dividend payers in the Chemicals market.
Opportunity
- Expected to breakeven next year.
- Has sufficient cash runway for more than 3 years based on current free cash flows.
- Good value based on P/S ratio and estimated fair value.
- Significant insider buying over the past 3 months.
Threat
- Debt is not well covered by operating cash flow.
- Paying a dividend but company is unprofitable.
Next Steps:
Whilst important, the DCF calculation ideally won't be the sole piece of analysis you scrutinize for a company. DCF models are not the be-all and end-all of investment valuation. Rather it should be seen as a guide to "what assumptions need to be true for this stock to be under/overvalued?" For example, changes in the company's cost of equity or the risk free rate can significantly impact the valuation. Why is the intrinsic value higher than the current share price? For FMC, we've compiled three additional items you should look at:
PS. The Simply Wall St app conducts a discounted cash flow valuation for every stock on the NYSE every day. If you want to find the calculation for other stocks just search here.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
OTTAWA, ON, Jan. 14, 2026 /CNW/ – Northern Shield Resources Inc. ("Northern Shield" or the "Company") (TSXV: NRN) is pleased to announce that a large area of mineralization has been exposed at the Creston Copper target, on the Company's 100% owned Root & Cellar Property ("Root & Cellar" or the "Property"), Burin Peninsula, southeastern Newfoundland. The Property hosts 5 epithermal gold-silver-(tellurium) zones over a 6-kilometre strike-length, and a large, associated polymetallic porphyry copper-molybdenite-silver-tellurium-gold system.
This new area of mineralization, covering approximately 50 m x 30 m, has been exposed as quarrying continues in one of several aggregate quarries on the Property (Fig 1). Mineralization consists of variable concentrations of pyrite-galena (lead sulphide) -sphalerite (lead-zinc) bearing quartz veinlets, fractures and breccia fillings with minor chalcopyrite, chalcocite, molybdenite and other sulphide minerals hosted in a diatreme breccia and rhyolite dikes that cut the breccia (Fig 2). This zone is adjacent to a recently discovered hydrothermal breccia vent and 50 m from breccia-hosted copper mineralization with grades up to 1.2% Cu, originally discovered by a prospector (see Company news release May 21, 2019). Copper mineralization, +/- molybdenite, gold, silver and tellurium with grades, from previously collected rock grab samples, include 8.5% Cu, 1.1% Mo, 0.13 g/t Au and 54 g/t Ag and 60 ppm Te, (see Company news release April 19, 2023), are exposed in 4 of the 5 aggregate quarries on the Property over a strike-length of 570 metres. The zone, which continues to the northeast, follows a magnetic trend coincident with copper-molybdenite-anomalous soil samples.
Assay results from the new rock grab samples are pending.
Induced polarization (IP) and/or magneto-telluric (MT) geophysical surveys over the expanded Creston target area are out for tender.
"We are excited by the rapid changes in geology and mineralization and the zone of lead-zinc veins and breccias. This is the largest area of mineralization exposed to date at the Creston target and its position adjacent to the copper mineralization is consistent with the outer zone of Cu-Mo-Ag (Au-Te) porphyry systems and is most encouraging. We have been discovering increasingly substantial mineralization since intensifying our focus on the Creston target last summer, and we are eager to see the results of the geophysical surveys." – Ian Bliss, President and CEO, Northern Shield
Technical information in this news release was reviewed and approved by Christine Vaillancourt, P. Geo., the Company's Chief Geologist and a Qualified Person under National Instrument 43-101.
About Northern Shield Resources
Northern Shield Resources Inc. is a Canadian-based company, a leader in generating high-quality exploration targets, that views greenfield exploration as an opportunity to find a mineable, near surface deposit at relatively low cost. We implement a model driven exploration approach to reduce the risk associated with early-stage projects for ourselves, our shareholders, and the environment. This approach led us to option the Root & Cellar Property from a Newfoundland prospector, who discovered the copper mineralization, and then to its advancement to the large gold-silver-tellurium and porphyry copper/moly system that it has become.
Forward-Looking Statements Advisory
This news release contains statements concerning the exploration plans, results and potential for epithermal gold deposits, and other mineralization at the Company's Root & Cellar Property , geological, geophysical and geometrical analyses of the properties and comparisons of the properties to known epithermal gold deposits and other expectations, plans, goals, objectives, assumptions, information or statements about future, conditions, results of exploration or performance that may constitute forward-looking statements or information under applicable securities legislation. Such forward-looking statements or information are based on a number of assumptions, which may prove to be incorrect.
Although Northern Shield believes that the expectations reflected in such forward-looking statements or information are reasonable, undue reliance should not be placed on forward looking statements because Northern Shield can give no assurance that such expectations will prove to be correct. Forward-looking statements or information are based on current expectations, estimates and projections that involve a number of risks and uncertainties which could cause actual results to differ materially from those anticipated by Northern Shield and described in the forward looking statements or information. These risks and uncertainties include, but are not limited to, risks associated with geological, geometrical and geophysical interpretation and analysis, the ability of Northern Shield to obtain financing, equipment, supplies and qualified personnel necessary to carry on exploration and the general risks and uncertainties involved in mineral exploration and analysis.
The forward-looking statements or information contained in this news release are made as of the date hereof and Northern Shield undertakes no obligation to update publicly or revise any forward looking statements or information, whether as a result of new information, future events or otherwise, unless so required by applicable securities laws.
Neither TSX Venture Exchange nor its Regulation Services Provider (as that term is defined in policies of the TSX Venture Exchange) accepts responsibility for the adequacy or accuracy of this release.
Figure 1. Map showing location of recently exposed lead-zinc +/- molybdenite veins relative to copper mineralization and hydrothermal vent breccia. Locations are draped over analytical signature of the total magnetic intensity and satellite image. Figure 1b. Gossanous blocks of rock from the lead-zinc zone. (CNW Group/Northern Shield Resources Inc.)Figure 2a. Quartz-pyrite stockwork veining associated with strong potassium alteration of rhyolite and, Figure 2b, B-type vein (?) with pyrite along centreline, strong potassic altered margins and minor galena or molybdenite. Figure 2c. Crackled brecciated rhyolite with sphalerite-filled fractures (zinc sulphide) and pyrite veins. (CNW Group/Northern Shield Resources Inc.)Figure 2d, Galena (?)-pyrite +/- sphalerite vein within rhyolite dyke and diatreme breccia (2e&f). (CNW Group/Northern Shield Resources Inc.)
Cision
View original content to download multimedia: http://www.newswire.ca/en/releases/archive/January2026/14/c5812.html
With the business potentially at an important milestone, we thought we'd take a closer look at Rock Tech Lithium Inc.'s (CVE:RCK) future prospects. Rock Tech Lithium Inc. engages in the exploration and development of lithium properties. With the latest financial year loss of CA$15m and a trailing-twelve-month loss of CA$12m, the CA$104m market-cap company alleviated its loss by moving closer towards its target of breakeven. Many investors are wondering about the rate at which Rock Tech Lithium will turn a profit, with the big question being “when will the company breakeven?” Below we will provide a high-level summary of the industry analysts’ expectations for the company.
Consensus from 2 of the Canadian Metals and Mining analysts is that Rock Tech Lithium is on the verge of breakeven. They anticipate the company to incur a final loss in 2025, before generating positive profits of CA$10m in 2026. So, the company is predicted to breakeven approximately a year from now or less! At what rate will the company have to grow in order to realise the consensus estimates forecasting breakeven in under 12 months? Using a line of best fit, we calculated an average annual growth rate of -33%,
TSXV:RCK Earnings Per Share Growth January 9th 2026
Given this is a high-level overview, we won’t go into details of Rock Tech Lithium's upcoming projects, though, bear in mind that typically metals and mining companies, depending on the stage of operation and metals mined, have irregular periods of cash flow. So, periods of lower growth in the upcoming years is not out of the ordinary, particularly when a company is in a period of investment.
View our latest analysis for Rock Tech Lithium
Before we wrap up, there’s one aspect worth mentioning. Rock Tech Lithium currently has no debt on its balance sheet, which is rare for a loss-making metals and mining company, which typically has high debt relative to its equity. This means that the company has been operating purely on its equity investment and has no debt burden. This aspect reduces the risk around investing in the loss-making company.
Next Steps:
This article is not intended to be a comprehensive analysis on Rock Tech Lithium, so if you are interested in understanding the company at a deeper level, take a look at Rock Tech Lithium's company page on Simply Wall St. We've also compiled a list of pertinent factors you should further examine:
Valuation: What is Rock Tech Lithium worth today? Has the future growth potential already been factored into the price? The intrinsic value infographic in our free research report helps visualize whether Rock Tech Lithium is currently mispriced by the market.
Management Team: An experienced management team on the helm increases our confidence in the business – take a look at who sits on Rock Tech Lithium’s board and the CEO’s background.
Other High-Performing Stocks: Are there other stocks that provide better prospects with proven track records? Explore our free list of these great stocks here.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
While "the trend is your friend" when it comes to short-term investing or trading, timing entries into the trend is a key determinant of success. And increasing the odds of success by making sure the sustainability of a trend isn't easy.
Often, the direction of a stock's price movement reverses quickly after taking a position in it, making investors incur a short-term capital loss. So, it's important to ensure that there are enough factors — such as sound fundamentals, positive earnings estimate revisions, etc. — that could keep the momentum in the stock going.
Our "Recent Price Strength" screen, which is created on a unique short-term trading strategy, could be pretty useful in this regard. This predefined screen makes it really easy to shortlist the stocks that have enough fundamental strength to maintain their recent uptrend. Also, the screen passes only the stocks that are trading in the upper portion of their 52-week high-low range, which is usually an indicator of bullishness.
There are several stocks that passed through the screen and Impala Platinum Holdings Ltd. (IMPUY) is one of them. Here are the key reasons why this stock is a solid choice for "trend" investing.
A solid price increase over a period of 12 weeks reflects investors' continued willingness to pay more for the potential upside in a stock. IMPUY is quite a good fit in this regard, gaining 37.1% over this period.
However, it's not enough to look at the price change for around three months, as it doesn't reflect any trend reversal that might have happened in a shorter time frame. It's important for a potential winner to maintain the price trend. A price increase of 37.9% over the past four weeks ensures that the trend is still in place for the stock of this company.
Moreover, IMPUY is currently trading at 97.6% of its 52-week High-Low Range, hinting that it can be on the verge of a breakout.
Looking at the fundamentals, the stock currently carries a Zacks Rank #1 (Strong Buy), which means it is in the top 5% of more than the 4,000 stocks that we rank based on trends in earnings estimate revisions and EPS surprises — the key factors that impact a stock's near-term price movements.
The Zacks Rank stock-rating system, which uses four factors related to earnings estimates to classify stocks into five groups, ranging from Zacks Rank #1 (Strong Buy) to Zacks Rank #5 (Strong Sell), has an impressive externally-audited track record, with Zacks Rank #1 stocks generating an average annual return of +25% since 1988. You can see the complete list of today's Zacks Rank #1 (Strong Buy) stocks here >>>>
Another factor that confirms the company's fundamental strength is its Average Broker Recommendation of #1 (Strong Buy). This indicates that the brokerage community is highly optimistic about the stock's near-term price performance.
So, the price trend in IMPUY may not reverse anytime soon.
In addition to IMPUY, there are several other stocks that currently pass through our "Recent Price Strength" screen. You may consider investing in them and start looking for the newest stocks that fit these criteria.
This is not the only screen that could help you find your next winning stock pick. Based on your personal investing style, you may choose from over 45 Zacks Premium Screens that are strategically created to beat the market.
However, keep in mind that the key to a successful stock-picking strategy is to ensure that it produced profitable results in the past. You could easily do that with the help of the Zacks Research Wizard. In addition to allowing you to backtest the effectiveness of your strategy, the program comes loaded with some of our most successful stock-picking strategies.
Click here to sign up for a free trial to the Research Wizard today.
Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Impala Platinum Holdings Ltd. (IMPUY) : Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).
American Resources Corporation AREC, via its minority holding in ReElement Technologies Corporation, has formed a partnership with Transition Equity Partners (“TEP”) for a $200 million strategic equity facility to accelerate global critical mineral and rare earth refining capacity and strengthen U.S. supply chains.
The capital will initially be used to expand the deployment of ReElement’s proprietary modular, multi-mineral refining platform and buildout of its Marion, IN facility, with targeted initial capacity exceeding 10,000 metric tons per year of refined critical minerals, including light and heavy rare earths and defense-related elements, sourced from recycled materials and mined concentrates.
The partnership also envisions the development of additional refining facilities across the United States and select international locations. ReElement’s chromatographic separation technology enables the production of high-purity critical minerals that are currently unavailable at a commercial scale domestically, helping address strategic supply gaps and reduce dependence on foreign suppliers.
The company is reinforcing its U.S. supply chain footprint through collaborations with the U.S. Department of War, Vulcan Elements and POSCO International to support the production of rare earth magnets and defense-critical materials. TEP’s global investment experience and advisory capabilities are expected to support ReElement’s international expansion further while enhancing resilient supply chains for energy, defense and advanced manufacturing markets.
Shares of AREC have rallied 276% in the past six months compared with the industry’s 21.6% rise.
Image Source: Zacks Investment Research
AREC’s Zacks Rank & Key Picks
AREC currently carries a Zacks Rank of #3 (Hold).
Some better-ranked stocks in the Basic Materials space are BHP Group Limited BHP, Impala Platinum Holdings Limited IMPUY and Sibanye Stillwater Limited SBSW. BHP, IMPUY and SBSW sport a Zacks Rank of #1 (Strong Buy). You can see the complete list of today’s Zacks #1 Rank stocks here.
The Zacks Consensus Estimate for BHP’s current fiscal-year earnings is pegged at $4.51 per share, indicating a 23.9% year-over-year increase. Shares of BHP have gained 31.3% over the past six months.
The Zacks Consensus Estimate for IMPUY’s current fiscal-year earnings stands at $1.33 per share, implying a 2,560% year-over-year increase. Shares of IMPUY have gained 86.1% over the past six months.
The Zacks Consensus Estimate for SBSW’s current fiscal-year earnings is pegged at $2.4 per share, indicating a 1,614.3% year-over-year increase. Shares of SBSW have soared 116.7% over the past six months.
Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
BHP Group Limited Sponsored ADR (BHP) : Free Stock Analysis Report
Impala Platinum Holdings Ltd. (IMPUY) : Free Stock Analysis Report
American Resources Corporation (AREC) : Free Stock Analysis Report
Sibanye Gold Limited (SBSW) : Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).
As the Australian market navigates a post-holiday slump, with key indices trending downward despite a rally in the materials sector, investors are keenly watching for opportunities amidst fluctuating commodity prices and geopolitical developments. In this dynamic environment, identifying stocks that can thrive involves looking at companies with strong fundamentals and potential to capitalize on emerging trends, such as those in ethical investment and innovative sectors.
Top 10 Undiscovered Gems With Strong Fundamentals In Australia
|
Name |
Debt To Equity |
Revenue Growth |
Earnings Growth |
Health Rating |
|---|---|---|---|---|
|
Fiducian Group |
NA |
10.00% |
9.57% |
★★★★★★ |
|
Joyce |
NA |
9.93% |
17.54% |
★★★★★★ |
|
Hearts and Minds Investments |
NA |
56.27% |
59.19% |
★★★★★★ |
|
Euroz Hartleys Group |
NA |
1.82% |
-25.32% |
★★★★★★ |
|
Argosy Minerals |
NA |
-12.81% |
-19.89% |
★★★★★★ |
|
Focus Minerals |
NA |
75.35% |
51.34% |
★★★★★★ |
|
Energy World |
NA |
-47.50% |
-44.86% |
★★★★★☆ |
|
Zimplats Holdings |
5.44% |
-9.79% |
-42.03% |
★★★★★☆ |
|
Australian United Investment |
1.90% |
5.23% |
4.56% |
★★★★☆☆ |
|
Reef Casino Trust |
19.84% |
6.96% |
10.88% |
★★★★☆☆ |
Here’s a peek at a few of the choices from the screener.
Simply Wall St Value Rating: ★★★★★★
Overview: Australian Ethical Investment Ltd is a publicly owned investment manager with a market cap of A$581.84 million, focusing on ethical and sustainable investment strategies.
Operations: The company generates revenue primarily from its funds management segment, amounting to A$119.38 million.
Australian Ethical Investment, a smaller player in the financial sector, has been making waves with its impressive performance metrics. Over the past year, earnings surged by 75.1%, outpacing the industry average of 6%. The company is debt-free and boasts high-quality earnings, suggesting a robust financial health. With levered free cash flow reaching A$26.35 million as of June 2025 and no debt for over five years, it seems well-positioned for continued growth. Earnings are projected to grow at an annual rate of 18.34%, painting a promising picture for future prospects in ethical investing.
ASX:AEF Earnings and Revenue Growth as at Jan 2026Advanced Innergy Holdings
Simply Wall St Value Rating: ★★★★☆☆
Overview: Advanced Innergy Holdings Limited specializes in the design, engineering, manufacturing, and installation of essential insulation, buoyancy, cable protection, and fire protection systems for energy and industrial sectors with a market capitalization of approximately A$405.45 million.
Operations: Advanced Innergy Holdings generates revenue through the design, engineering, manufacturing, and installation of insulation, buoyancy, cable protection, and fire protection systems. The company has a market capitalization of approximately A$405.45 million.
Advanced Innergy Holdings, a compact player in the machinery sector, has shown impressive financial strides. Their earnings skyrocketed by 163% over the past year, outpacing the industry’s 13.6% growth rate. Despite a high net debt to equity ratio of 55%, their interest payments are comfortably covered by EBIT at 3.8 times. The company reported A$150 million from its recent IPO and trades at 32% below estimated fair value, suggesting potential upside for investors. With revenue climbing to £150 million and net income more than doubling to £10 million in fiscal year 2025, AIH seems poised for continued expansion with forecasted revenue growth of nearly A$388 million in 2026.
ASX:AIH Debt to Equity as at Jan 2026Ricegrowers
Simply Wall St Value Rating: ★★★★★☆
Overview: Ricegrowers Limited is a rice food company with operations spanning Australia, New Zealand, the Pacific Islands, Europe, the Middle East, Africa, Asia, and North America and has a market cap of A$1.13 billion.
Operations: Ricegrowers Limited generates revenue primarily from its rice food segment, with reported figures reaching A$1.82 billion. The company’s financial performance is influenced by various factors, including market conditions across its diverse geographical operations.
Ricegrowers, a key player in the rice industry, is capitalizing on expanding markets like the Middle East and the U.S., driven by growing demand. The company reported A$882.34 million in sales for the half-year ending October 2025, with net income rising to A$35.95 million from A$31.25 million a year prior. Its earnings per share increased to A$0.534 from A$0.472, indicating strong operational performance despite sales dipping slightly from last year’s figures of A$910.67 million. With a satisfactory net debt to equity ratio of 23%, Ricegrowers is well-positioned for strategic acquisitions and continued growth initiatives.
ASX:SGLLV Debt to Equity as at Jan 2026Next Steps
-
Delve into our full catalog of 60 ASX Undiscovered Gems With Strong Fundamentals here.
-
Are you invested in these stocks already? Keep abreast of every twist and turn by setting up a portfolio with Simply Wall St, where we make it simple for investors like you to stay informed and proactive.
-
Maximize your investment potential with Simply Wall St, the comprehensive app that offers global market insights for free.
Want To Explore Some Alternatives?
-
Explore high-performing small cap companies that haven’t yet garnered significant analyst attention.
-
Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
-
Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Companies discussed in this article include ASX:AEF ASX:AIH and ASX:SGLLV.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com
Denison Mines Corp. DNN recently announced that its flagship Phoenix In-Situ Recovery (ISR) uranium project, located at the Wheeler River in Saskatchewan, is now fully prepared to advance into the construction phase, subject to final regulatory approval, expected in the first quarter of 2026. DNN expects to make a final investment decision (FID) following receipt of final regulatory approvals.
The company noted that major progress was achieved throughout 2025 across regulatory approvals, detailed engineering, procurement and construction planning, including the completion of the Canadian Nuclear Safety Commission’s public hearing process and prior provincial environmental clearance.
Denison reaffirmed that Phoenix is on track to become Canada’s first new large-scale uranium mine since Cigar Lake, with an expected 24-month construction period and first production targeted for mid-2028, assuming permits are finalized and a positive FID. The company updated the post-FID initial capital cost to approximately $600 million on a Class 2 budget basis, reflecting inflation and project refinements compared to the 2023 feasibility study, including roughly $65 million in contingency funds. No further revisions are anticipated before construction commencement.
Construction readiness is supported by largely completed detailed engineering, procurement of long-lead items, near-final construction contracts for 2026, and initial provincial approval for early site works.
Shares of DNN rallied 67.4% over the past six months compared with the industry’s 18.1% rise.
Zacks Investment Research
Image Source: Zacks Investment Research
DNN Zacks Rank & Key Picks
DNN currently carries a Zacks Rank of #3 (Hold).
Some better-ranked stocks in the Basic Materials space areImpala Platinum Holdings Limited IMPUY, BHP Group Limited BHP and Paladin Energy Ltd. PALAF. IMPUY sports a Zacks Rank of #1 (Strong Buy), while BHP and PALAF carry a Zacks Rank of #2 (Buy). You can see the complete list of today’s Zacks #1 Rank stocks here.
The Zacks Consensus Estimate for IMPUY’s current fiscal-year earnings is pegged at $1.33 per share, indicating a 2,560% year-over-year increase. Shares of IMPUY have jumped 67.2% over the past six months.
The Zacks Consensus Estimate for BHP’s current fiscal-year earnings stands at $4.51 per share, implying a 23.9% year-over-year increase. Shares of BHP have gained 25% over the past six months.
The Zacks Consensus Estimate for PALAF’s current fiscal-year earnings is pegged at 5 cents per share, indicating a 139% year-over-year increase. Shares of PALAF have soared 39.9% over the past six months.
Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
BHP Group Limited Sponsored ADR (BHP) : Free Stock Analysis Report
Impala Platinum Holdings Ltd. (IMPUY) : Free Stock Analysis Report
Denison Mine Corp (DNN) : Free Stock Analysis Report
Paladin Energy Ltd. (PALAF) : Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).
As we usher in 2026, the Australian market has been marked by a flat trading session with materials leading gains, while IT sectors lagged behind. In this landscape of cautious optimism and sector-specific movements, identifying hidden opportunities requires a keen eye for stocks that can thrive despite broader market uncertainties.
Top 10 Undiscovered Gems With Strong Fundamentals In Australia
| Name | Debt To Equity | Revenue Growth | Earnings Growth | Health Rating |
|---|---|---|---|---|
| Fiducian Group | NA | 10.00% | 9.57% | ★★★★★★ |
| Joyce | NA | 9.93% | 17.54% | ★★★★★★ |
| Hearts and Minds Investments | NA | 56.27% | 59.19% | ★★★★★★ |
| Euroz Hartleys Group | NA | 1.82% | -25.32% | ★★★★★★ |
| Argosy Minerals | NA | -12.81% | -19.89% | ★★★★★★ |
| Focus Minerals | NA | 75.35% | 51.34% | ★★★★★★ |
| Energy World | NA | -47.50% | -44.86% | ★★★★★☆ |
| Zimplats Holdings | 5.44% | -9.79% | -42.03% | ★★★★★☆ |
| Peet | 53.46% | 12.70% | 31.21% | ★★★★☆☆ |
| Australian United Investment | 1.90% | 5.23% | 4.56% | ★★★★☆☆ |
Here we highlight a subset of our preferred stocks from the screener.
Simply Wall St Value Rating: ★★★★★★
Overview: Cedar Woods Properties Limited is an Australian company that focuses on property development and investment, with a market cap of A$727.40 million.
Operations: Cedar Woods Properties generates revenue primarily from its property development and investment activities, totaling A$465.94 million. The company’s financial performance is influenced by its cost structure, which impacts the net profit margin.
Cedar Woods Properties, a notable player in the Australian property market, has shown consistent earnings growth of 12.1% annually over the past five years. The company’s net debt to equity ratio stands at a satisfactory 25.8%, with interest payments well-covered by EBIT at 7.2 times. Trading at 43.8% below its estimated fair value, Cedar Woods is poised for further growth with an expected earnings increase of 19.8% per year and a robust presales pipeline valued at A$660 million providing revenue stability. Despite challenges like potential interest rate hikes and rising construction costs, recent guidance indicates record profits for financial year 2026, supporting increased dividends and reflecting strong sales volumes.
ASX:CWP Earnings and Revenue Growth as at Jan 2026IVE Group
Simply Wall St Value Rating: ★★★★★☆
Overview: IVE Group Limited, along with its subsidiaries, operates in the marketing sector in Australia and has a market capitalization of A$465.68 million.
Operations: IVE Group generates revenue primarily from its advertising segment, amounting to A$959.25 million.
IVE Group, a small player in Australia’s media and communications sector, has shown impressive financial performance with earnings growth of 69.2% over the past year. This growth outpaced the broader media industry, which saw a contraction of 42.8%. Despite its high net debt to equity ratio at 51.7%, IVE’s interest payments are well covered by EBIT at 5.1 times coverage, indicating solid operational efficiency. The company’s debt to equity ratio has improved from 105.1% to 75.2% over five years, suggesting prudent financial management while trading at a significant discount of 72.8% below estimated fair value offers potential upside for investors.
- Take a closer look at IVE Group’s potential here in our health report.
-
Gain insights into IVE Group’s historical performance by reviewing our past performance report.
ASX:IGL Earnings and Revenue Growth as at Jan 2026Mayfield Group Holdings
Simply Wall St Value Rating: ★★★★★★
Overview: Mayfield Group Holdings Limited, along with its subsidiaries, offers electrical and telecommunications infrastructure products and services in Australia, with a market capitalization of A$376 million.
Operations: Mayfield Group Holdings generates revenue primarily from its electrical and telecommunications infrastructure segment, amounting to A$118.14 million. The company’s financial performance can be analyzed through its net profit margin trends over recent periods.
Mayfield Group Holdings, a notable player in the electrical industry, has seen its earnings grow by 32.5% over the past year, outpacing the industry’s 9.9% growth rate. With a debt to equity ratio that has improved from 8.9% to just 0.2% in five years, it appears financially stable and holds more cash than total debt, easing concerns about interest payments. Despite recent significant insider selling and shareholder dilution due to follow-on equity offerings totaling A$33 million at A$1.90 per share, the company remains profitable with high-quality earnings and positive free cash flow of A$15 million as of June 2024.
- Click to explore a detailed breakdown of our findings in Mayfield Group Holdings’ health report.
-
Explore historical data to track Mayfield Group Holdings’ performance over time in our Past section.
ASX:MYG Debt to Equity as at Jan 2026Where To Now?
- Get an in-depth perspective on all 59 ASX Undiscovered Gems With Strong Fundamentals by using our screener here.
- Have you diversified into these companies? Leverage the power of Simply Wall St’s portfolio to keep a close eye on market movements affecting your investments.
- Simply Wall St is a revolutionary app designed for long-term stock investors, it’s free and covers every market in the world.
Contemplating Other Strategies?
- Explore high-performing small cap companies that haven’t yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data
and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your
financial situation. We aim to bring you long-term focused analysis driven by fundamental data.
Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material.
Simply Wall St has no position in any stocks mentioned.
Companies discussed in this article include ASX:CWP ASX:IGL and ASX:MYG.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com
VANCOUVER, BC / ACCESS Newswire / January 5, 2026 / Apex Critical Metals Corp. (CSE:APXC)(OTCQX:APXCF)(FWB:KL9) ("Apex" or the "Company"), a Canadian mineral exploration company focused on the identification and development of critical and strategic metals, is pleased to announce that it has received approval from the Nebraska Department of Water, Energy and Environment ("NDEE") for its mineral exploration permit ("drill permit") at the Company's flagship Rift Rare Earth Project, located within the Elk Creek Carbonatite Complex in southeastern Nebraska, U.S.A.
Apex CEO, Sean Charland, stated: "We have been very active expanding and consolidating our property position and completing historical re-logging, re-assaying and 3D modelling work in preparation for our inaugural drill campaign at the Rift Rare Earth Project. We are very pleased to receive our drill permit, which marks a significant step forward as we transition from planning and preparation to drill program execution. We are eager to begin verifying and expanding upon the excellent historical results, which we believe can rapidly position the Rift Project as one of the premier rare earth projects in North America."
The Rift Project now covers approximately 3,500 acres across the Elk Creek Carbonatite Complex-an area with extensive historical drilling by previous operators, including Molycorp (1973-1986) and Quantum Rare Earth Developments (2010-2011). Historical programs reported broad, high-grade REE mineralized intervals, including:
-
155.5 metres ("m") of 2.70% REO(1), including 54.9 m at 3.30% REO (EC-93).
-
236.2 m of 2.10% REO, including 68.2 m of 3.32% REO (NEC11-004).
Drill Program Preparations
With a permit now in hand, Apex has begun advancing all pre-drilling activities, with drilling expected to commence during the first half of Q1/2026. Ongoing preparations include:
-
Finalizing discussions with contractors
-
Securing drill mobilization schedules and support services
-
Establishing access routes and planned drill pad locations
-
Completing logistical planning for core handling, sampling, and onsite operations; and
-
Target refinement based on historical data and detailed geological review.
A detailed summary of the drillhole locations and planned meterage will be released as the program commences.
Management cautions that drillhole EC-93 is historical and was originally completed by Molycorp between 1984-1986 with reanalysis performed by Quantum Rare Earth Development Corp. in 2010. The EC-93 results presented herein are from the 2010 reanalysis.
1Rare earth oxide (REO), includes the sum of Ce2O3, La2O3, Pr2O3, Nd2O3, Eu2O3, Sm2O3, Gd2O3, Tb2O3, Dy2O3, Ho2O3, Er2O3, Tm2O3, Yb2O3, Lu2O3, and Y2O3
Qualified Person
The technical content of this news release has been reviewed and approved by Nathan Schmidt, P. Geo., a Qualified Person under NI 43-101 on standards of disclosure for mineral projects. Mr. Schmidt is a Geologist with Dahrouge Geological Consulting Ltd., the consulting firm engaged by Apex Critical Metals Corp. to conduct and oversee all of the Company's exploration work, including the 2026 drill program.
References
Molycorp, Inc. (1973-1986). Elk Creek Carbonatite Exploration Drill Program Reports. Internal company records, archived at the Nebraska Geological Survey, Lincoln, Nebraska, USA.
Daigle, P., P.Geo. (2012).; NI 43-101 Elk Creek NB Project, Nebraska, US – Resource Estimate Update, Prepared for Quantum Rare Earth Development Corp., by Tetra Tech Wardrop, April 23, 2012.
Quantum Rare Earth Developments Corp. (2011). "Quantum Announces Significant Rare Earth Results from Elk Creek, Nebraska." News Release, September 20, 2011.
About Apex Critical Metals Corp. (CSE: APXC) (OTCQX: APXCF) (FWB: KL9)
Apex Critical Metals Corp. is a Canadian exploration company focused on advancing rare earth element (REE) and niobium projects that support the growing demand for critical and strategic metals across the United States and Canada. The Company's flagship Rift Project, located within the highly prospective Elk Creek Carbonatite Complex in Nebraska, U.S.A., hosts extensive rare earth rights surrounding one of North America's most advanced niobium-REE deposits. Historical drilling across the complex has reported broad intervals of high-grade REE mineralization, including intercepts such as 155.5 m of 2.70% REO and 68.2 m of 3.32% REO.
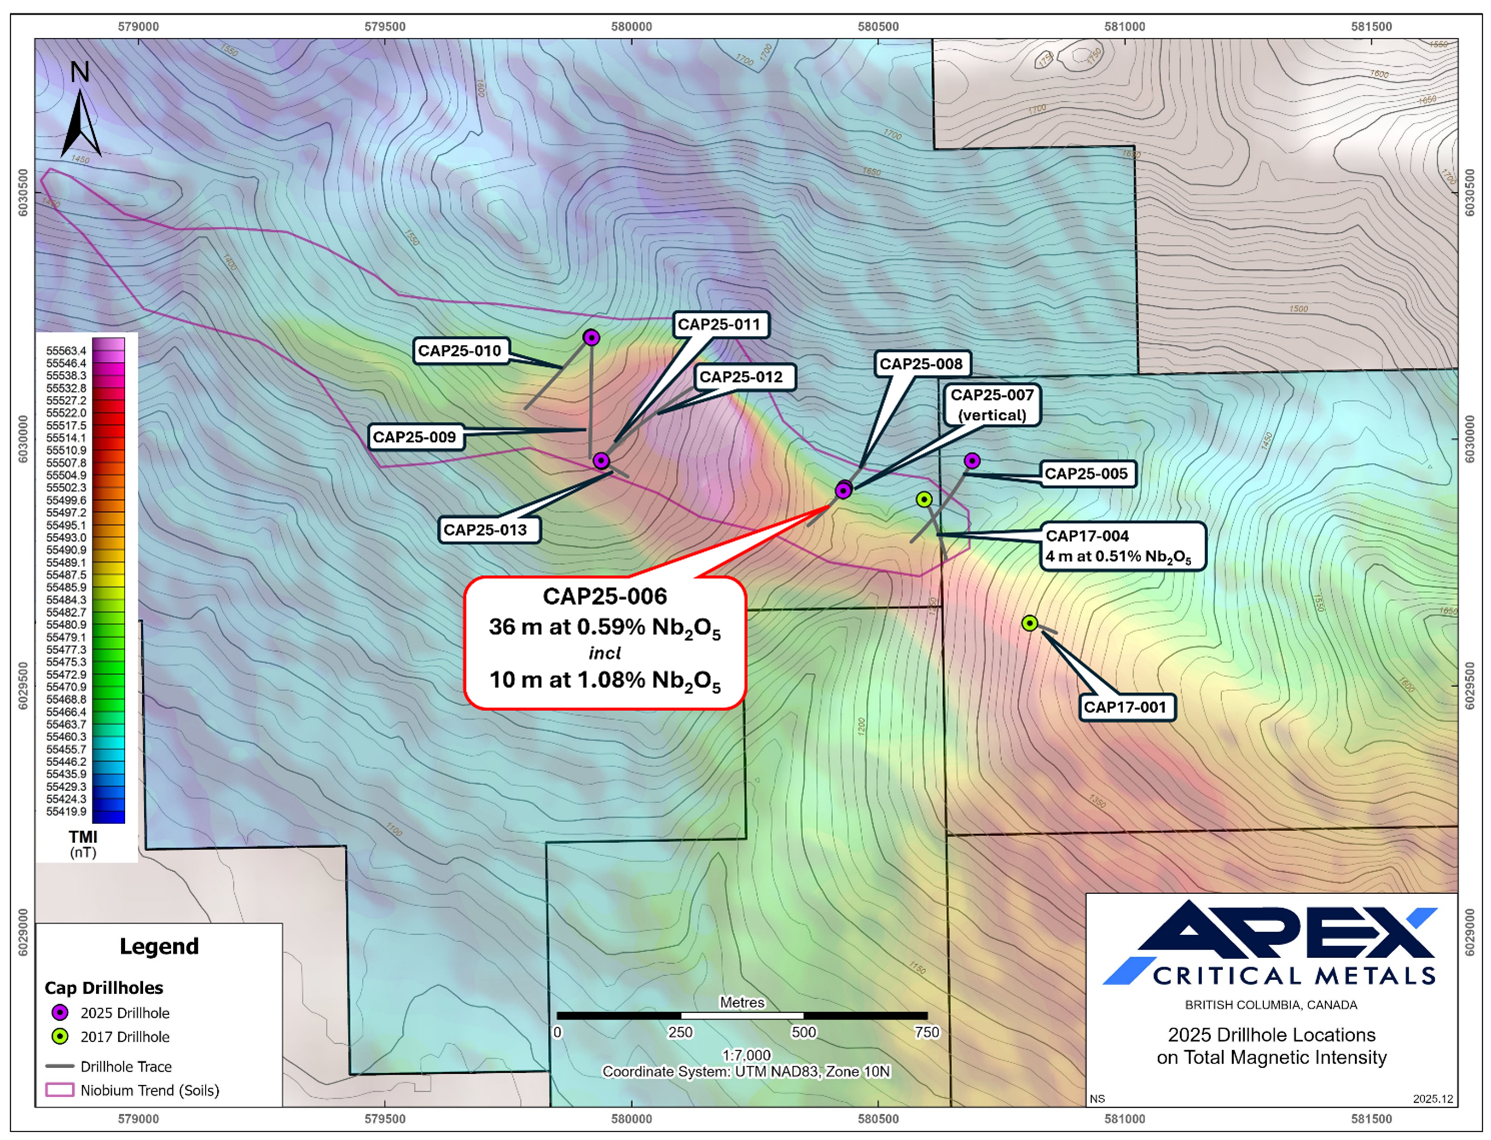
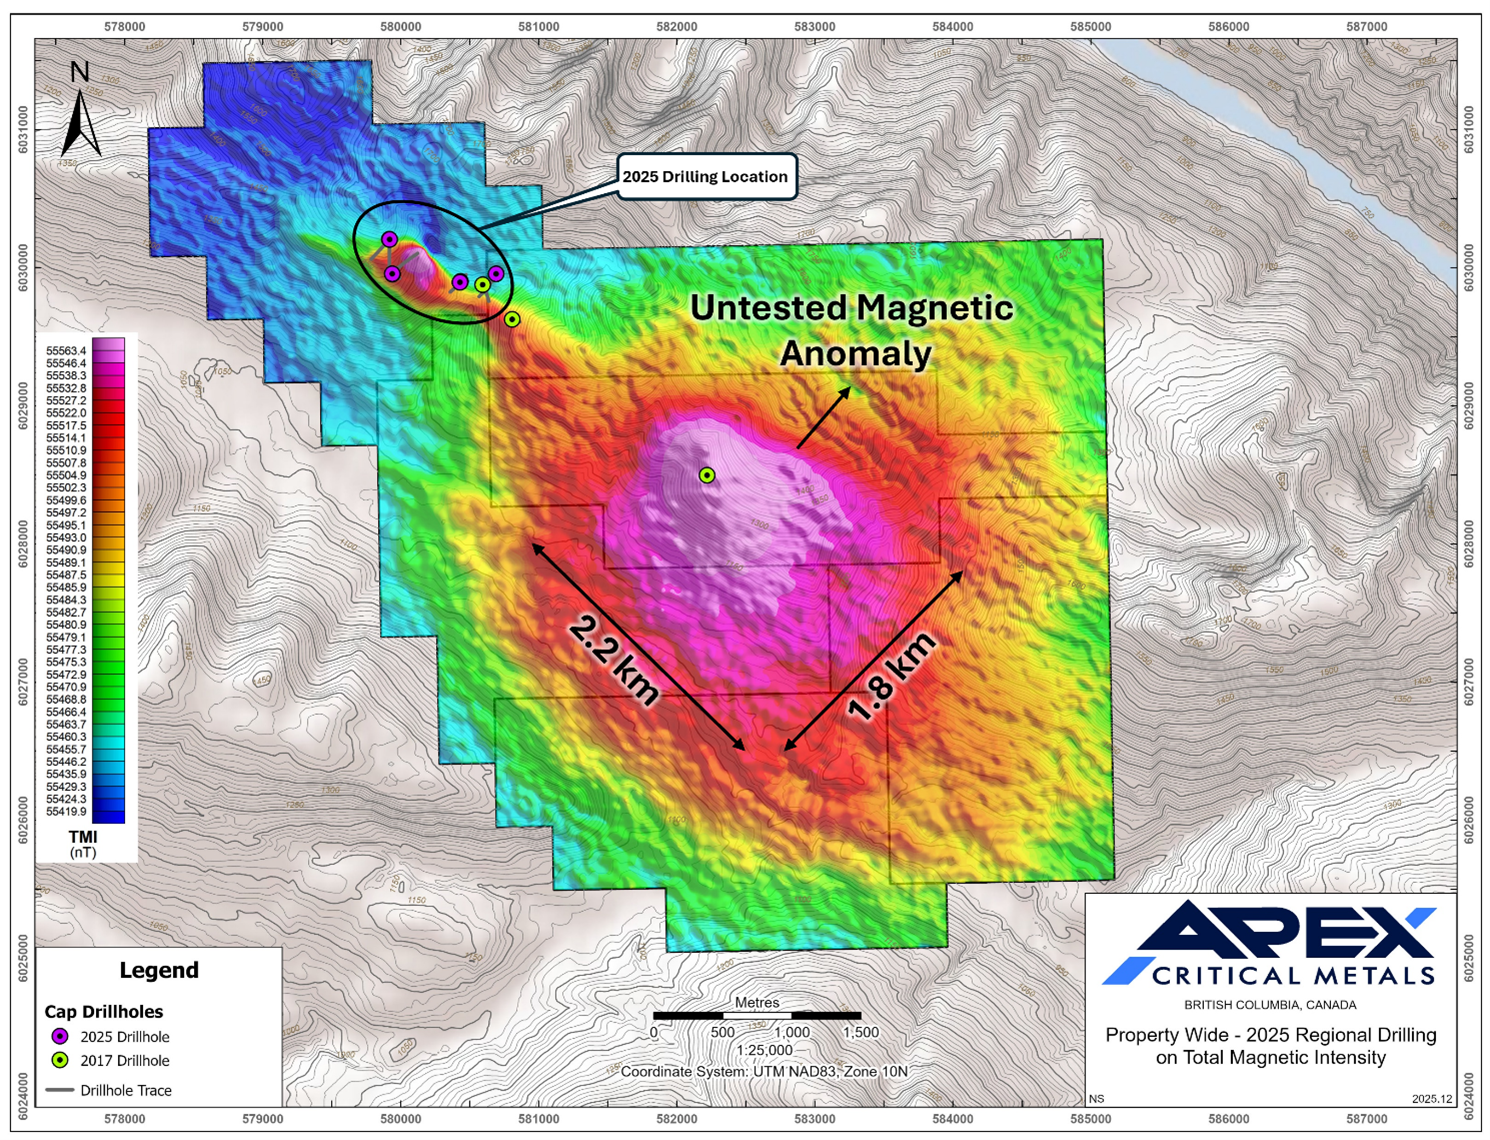
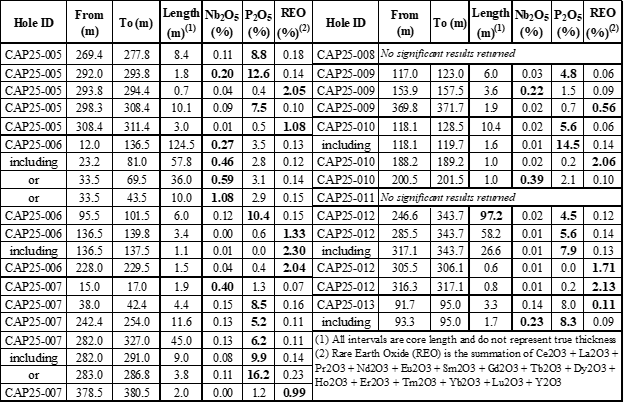
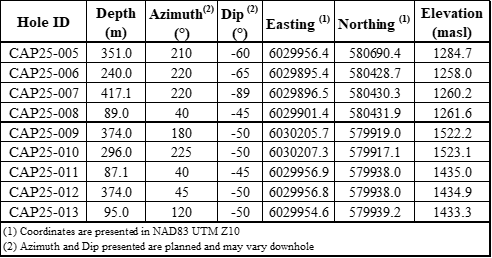
In Canada, Apex continues to advance its 100%-owned Cap Project, located 85 kilometres northeast of Prince George, British Columbia. The 2025 drill program confirmed a significant niobium discovery with 0.59% Nb₂O₅ over 36 metres, including 1.08% Nb₂O₅ over 10 metres, within a 1.8-kilometre-long niobium trend. The Cap Project continues to demonstrate strong potential for niobium mineralization within a large and previously unrecognized carbonatite system.
With a growing portfolio of critical mineral projects in both Canada and the United States, Apex Critical Metals is strategically positioned to help strengthen domestic supply chains for the minerals essential to advanced technologies, clean energy, and national security. Apex is publicly listed in Canada on the Canadian Securities Exchange (CSE) under the symbol APXC and quoted on the OTCQX market in the United States under the symbol APXCF, and in Germany on the Borse Frankfurt under the symbol KL9 and/or WKN: A40CCQ. Find out more at www.apexcriticalmetals.com and to sign up for free news alerts please go to https://apexcriticalmetals.com/news/news-alerts/, or follow us on X (formerly Twitter), Facebook or LinkedIn.
On Behalf of the Board of Directors
APEX CRITICAL METALS CORP.,
Sean CharlandChief Executive OfficerTel: 604.681.1568Email: info@apexcriticalmetals.com
Neither the Canadian Securities Exchange nor its Regulation Services Provider (as that term is defined in the policies of the CSE) accepts responsibility for the adequacy or accuracy of this release.
CAUTIONARY STATEMENT REGARDING FORWARD-LOOKING INFORMATION:
This news release may contain "forward-looking statements" under applicable Canadian securities legislation. Forward-looking statements consist of statements that are not purely historical, including any statements regarding beliefs, plans, expectations or intentions regarding the future. Forward-looking statements in this news release include (without limitation) statements regarding the Company's Canadian and US-based prospective assets (more particularly described above), including the potential for additional acquisitions, statements about the potential for the Rift Project's potential as a premier rare earth project in North America and statements regarding the anticipated drilling program on the Rift Project in 2026. Forward-looking statements are subject to various known and unknown risks and uncertainties that may cause actual results, performance or developments to differ materially from those contained in the statements. Risks that could change or prevent these events, activities or developments from coming to fruition include: the Company's properties are at an early stage of development and no current mineral resources or reserves have been identified by the Company thereof, that we may not be able to fully finance any additional exploration on the Company's properties; that even if we are able to raise capital, costs for exploration activities may increase such that we may not have sufficient funds to pay for such exploration or processing activities; the timing and content of any future work programs; geological interpretations based on drilling that may change with more detailed information; potential process methods and mineral recoveries assumptions based on limited test work and by comparison to what are considered analogous deposits that, with further test work, may not be comparable; testing of our process may not prove successful or samples derived from our properties may not yield positive results, and even if such tests are successful or initial sample results are positive, the economic and other outcomes may not be as expected; the anticipated market demand for REE and other minerals may not be as expected; the availability of labour and equipment to undertake future exploration work and testing activities; geopolitical risks which may result in market and economic instability. There can be no assurance that such statements will prove to be accurate, as actual results and future events could differ materially from those anticipated in such statements. Accordingly, readers should not place undue reliance on forward-looking statements. The forward-looking statements herein are made as of the date hereof, and the Company disclaims any intention or obligation to update or revise any forward-looking statements, whether as a result of new information, future events or otherwise, except as required by law.
SOURCE: Apex Critical Metals Corp.
View the original press release on ACCESS Newswire
After a tough 2025, the global lithium market is gearing up for a new growth cycle. Prices fell about 90% by mid-year from their 2022 peak levels as electric vehicle (EV) demand slowed and supply built up, but 2026 looks very different.
EVs will still drive demand, but new sources are joining the mix. Strong growth in solar power installations across Europe, the United States and the Asia-Pacific region is boosting the use of battery energy storage systems (BESS), which rely on lithium to store electricity from renewable energy.
Artificial intelligence is also creating a new need for lithium. Massive AI data centers use as much electricity as small cities, and many are now adding lithium-ion batteries on-site to handle peak energy use and reduce pressure on local grids. Autonomous machines and humanoid robots could become another steady source of lithium demand over the next decade.
Governments are taking notice, too. Many now treat lithium as strategic, like energy grids or defense equipment. This means governments may support production and investments, adding stability to the market.
Per Fortune Business Insights, the global lithium market is expected to expand from $13.9 billion in 2024 to $55.5 billion by 2032, implying a CAGR of nearly 19%.
While lithium prices have been under pressure, sentiment is turning. Lithium carbonate prices in China have rallied more than 20% so far this month. Major producer Ganfeng Lithium expects global lithium demand to grow 30-40% in 2026 and has flagged high price targets of 150,000-200,000 RMB/ton as the market moves back toward balance.
Against this backdrop, a few lithium stocks — Rio Tinto plc RIO, Lithium Americas Corp. LAC, Albemarle Corporation ALB and Sociedad Quimica y Minera de Chile S.A. SQM — are worth keeping on your watchlist.
Rio Tinto
Rio Tinto is making a serious push into lithium, aiming to become one of the world’s major producers. Earlier this year, the company completed its $6.7 billion acquisition of Arcadium Lithium, giving it access to one of the largest lithium resource bases globally. With Arcadium’s high-quality assets and broad product portfolio, Rio Tinto plans to grow capacity at its Tier 1 lithium operations to more than 200,000 tons of lithium carbonate equivalent per year by 2028.
Rio Tinto is also expanding its lithium footprint in South America. It acquired the Rincon project in Argentina in 2022 and made a $2.5 billion investment in the project in 2024. Rincon is expected to produce up to 60,000 tons of battery-grade lithium carbonate annually, with first production targeted for 2028 and a gradual ramp-up to full capacity.
In Chile, Rio Tinto has formed joint ventures with Codelco and ENAMI this year to develop high-grade lithium projects, strengthening its long-term supply pipeline.
For investors, Rio Tinto offers diversified exposure to lithium alongside its established global mining business. The stock sports a Zacks Rank #1 (Strong Buy). The Zacks Consensus Estimate for RIO’s next year EPS implies a year-over-year uptick of 11%. You can see the complete list of today’s Zacks #1 Rank stocks here.
Lithium Americas
Lithium Americas is making a bold play on the U.S. lithium market with its Thacker Pass project in Nevada, home to the largest lithium resource in the country. This project plays a critical role in securing domestic lithium supply. Thacker Pass is expected to produce up to 40,000 tons of lithium carbonate per year, enough for roughly 800,000 electric vehicles. If fully realized, this output could push the United States to the world’s second-largest lithium producer. Phase 1 of the project is on track, with mechanical construction of the processing plant expected to finish by late 2027.
The project has also attracted strong government backing. In October, the U.S. Department of Energy (“DOE”) acquired a 5% stake in both Lithium Americas and the Thacker Pass joint venture. Lithium Americas also drew the first $435 million from a larger $2.23 billion DOE loan, fueling construction and securing funding for the next stages.
For investors looking at the lithium rebound, LAC stands out as a key domestic play. Its combination of scale, government support and a clear production roadmap positions it well to benefit from rising lithium demand in the coming years.
LAC carries a Zacks Rank #3 (Hold). The Zacks Consensus Estimate for LAC’s next year’s bottom line suggests a year-over-year improvement of 42%.
Albermarle
Albemarle is one of the world’s top lithium producers, well-positioned to benefit from long-term growth in battery-grade lithium. The company is actively boosting its global lithium conversion capacity through strategic projects, focusing on high-return investments that improve productivity and efficiency. Production milestones are supporting growth. In Chile, the Salar yield improvement project has reached a 50% operating rate, while ramp-up at the Meishan lithium conversion facility in China is ahead of schedule. Record output from integrated conversion plants contributed to higher sales volumes in Albemarle’s Energy Storage unit in the third quarter of 2025.
Albemarle is also streamlining operations, cutting costs and optimizing its conversion network to maintain a strong competitive edge. In 2025, these initiatives are expected to deliver around $450 million in cost and productivity gains, exceeding the initial target of $300-400 million.
With robust customer demand, expanded capacity and efficiency improvements, ALB is positioned to capture rising lithium demand globally. Its scale, diversified operations and focus on cost management make it a key player for investors looking to ride on the lithium rebound in 2026.
ALB carries a Zacks Rank #3. The Zacks Consensus Estimate for ALB’s 2026 EPS implies a year-over-year jump of 217%.
Sociedad Quimica
Sociedad Química is one of the noted producers of lithium, supplying battery and energy storage markets worldwide. Its scale and global footprint make it a key player as lithium demand rebounds.
SQM has built a highly diversified lithium platform across Chile, Australia and China. In Chile, the company is expanding operations at the Salar de Atacama, targeting lithium carbonate production of 240,000 metric tons by 2026. It is also ramping up lithium hydroxide capacity to 100,000 metric tons by the end of 2025.
In Australia, SQM is advancing the Mt. Holland project, a 50,000-metric-ton lithium hydroxide operation developed through a joint venture, while pursuing additional exploration projects. In China, the company operates a lithium hydroxide refinery and tolling facility with 40,000 metric tons of capacity, strengthening its downstream reach and global supply chain.
SQM expects long-term lithium demand to outpace supply and has already completed major capacity upgrades. With these improvements in place, the company believes it can grow market share, especially in supplying lithium for EV batteries.
For investors, SQM offers scale, diversification and strong leverage to a lithium market recovery. The stock carries a Zacks Rank #3. The Zacks Consensus Estimate for SQM’s 2026 EPS indicates a year-over-year surge of 117%.
Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Rio Tinto PLC (RIO) : Free Stock Analysis Report
Albemarle Corporation (ALB) : Free Stock Analysis Report
Sociedad Quimica y Minera S.A. (SQM) : Free Stock Analysis Report
Lithium Americas Corp. (LAC) : Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).
Bravo Mining’s (BRVO.V) Chairman and Chief Executive Luis Azevedo on Wednesday issued his annual let
TORONTO, Dec. 31, 2025 /CNW/ – Bravo Mining Corp. (TSX.V: BRVO) (OTCQX: BRVMF), ("Bravo" or the "Company") today issued its Annual Letter to Shareholders as per below (the "Letter").
Dear fellow Shareholders,
It is with immense gratitude and a profound sense of accomplishment that I address you at the close of 2025, a year that will undoubtedly be marked as a watershed moment for Bravo Mining Corp.
This past year represents a clear inflection point in the Company's evolution, one defined by disciplined execution, material de-risking of our flagship asset and consistent value creation; a year that consolidated our Luanga palladium + platinum + rhodium + gold + nickel project ("Luanga Project" or "Luanga PGM+Au+Ni Project") as one of the few large-scale, multi-million-ounce, open-pit PGM+Au+Ni deposits globally, located in a mining-friendly, geopolitically favourable and infrastructure-rich jurisdiction.
Our philosophy has remained consistent: to de-risk and advance Luanga methodically while maintaining disciplined capital allocation, enabling us to endure challenging commodity cycles and remain well positioned to benefit from shifts in market sentiment, as is now the case with PGMs and gold. This approach has allowed us to deliver a series of significant milestones while maintaining a strong financial position providing a solid platform for continued progress in 2026.
Strategic and Operational Milestones in 2025:
This year was punctuated by the delivery of a series of significant milestones that placed Luanga in the premier league of PGM projects globally:
Updated Mineral Resource Estimate1 ("MRE"): Exceeding our own expectations for resource growth, early in the year we reported the follow-on to our 2023 maiden MRE1, delivering significant increases in tonnage, grade, and resource confidence, while keeping the door open for continued resource expansion.
The updated MRE1 outlines total Measured and Indicated ("M&I") resources of 158 million tonnes ("Mt") grading 2.04 grams per tonne ("g/t") PdEq¹, containing 10.4 million ounces ("Moz") of PdEq¹, along with Inferred Resources of 78 Mt grading 2.01 g/t PdEq¹ for an additional 5.0 Moz PdEq¹. Importantly, approximately two-thirds of the total resource is now classified in the M&I category, with 86% of the MRE1 tonnage defined to a depth of only 250 metres, while mineralization has been confirmed to at least 400 metres, clearly indicating strong potential for further growth at depth.
1 Notes and Disclaimers on MRE and Palladium Equivalent – For MRE details, grades by individual metals and details for the basis of the Palladium Equivalent calculation, please see "Luanga Project 2025 MRE" section at the end of this press release.
Preliminary License (LP) Obtained: In February 2025 we secured the Preliminary License (LP) for our Luanga Project, the most critical and time-intensive permit in Brazil's environmental licensing process. Preparation for Luanga's permitting began well before our IPO in July 2022, with early environmental studies, proactive community engagement, and strong collaboration with government agencies.
This dedication culminated in a highly successful public hearing on December 12, 2024, where we received overwhelming community support, paving the way for this achievement.
Preliminary Economic Assessment2 ("PEA") Completed: In June 2025, we completed the PEA2 for the Luanga Project, outlining a potential for 17-year Life of Mine with average annual payable production of approximately 436,000 Ounces of 4 PGE (255,000 oz Palladium, 158,000 oz Platinum, 15,000 oz Rhodium, 8,500 oz Gold) plus 8,549 tonnes of Nickel.
The PEA2 evaluated two development scenarios. The Base Case, based on flotation concentrate sales to a third-party refiner, illustrated potential for an after-tax Net Present Value at 8% ("NPV8%") of US$1.25 billion and an IRR of 49%. The Alternate Case, which contemplates a vertically integrated operation, enhances value with an after-tax NPV8% of US$1.86 billion and a 49% IRR. Such economics were achieved assuming a 4 PGE basket price about 30% lower than prevailing prices (Dec 30, 2025).
The combination of high margins and a low CAPEX-to-NPV ratio underscores the potential of Luanga's open-pit nature over its 8.1km of continuous mineralized strike and favorable setting for project development, where existing infrastructure, such as paved roads alongside the deposit, power lines, cost-effective hydropower, water availability, a skilled mining workforce and tax incentives, result in operating costs that could be meaningfully more competitive than many other PGM deposits worldwide.
2For complete details, forward looking statements and disclaimers of the PEA, please see press release published on July 7, 2025. The PEA is based on the 2025 MRE for the Luanga Project (see later section: Luanga Project 2025 MRE and press release published on February 18, 2025)
Bravo to Anchor New Port of Vila do Conde Export Processing Zone (ZPE): One of the year's most significant strategic advancements was the selection of Bravo as the anchor company for the newly created Barcarena Export Processing Zone (ZPE) at the Port of Vila do Conde, Pará, the first mineral project ever to anchor a ZPE in Brazil. This designation materially strengthens Luanga's vertical integration optionality outlined in the PEA's Alternate Case2, providing a framework to support potential future concentrate processing through a smelter, whether developed by Bravo, in partnership, or by a third party.
The ZPE significantly enhances this opportunity through potential CAPEX savings, import exemptions on equipment and supplies, and tax-free exports from a strategically located deep-sea port. Importantly, the Barcarena industrial corridor hosts multiple fertilizer and chemical producers that currently rely on imported sulphuric acid. Acid generated locally as a by-product of Luanga's potential processing route could be sold directly to fertilizer blenders, creating a meaningful additional revenue stream while helping address Brazil's structural deficit in sulphuric acid supply. To illustrate this opportunity, the PEA conservatively assumed a sulphuric acid sales credit of US$160/t, while recent market prices have reached approximately US$440/t, levels that have forced major fertilizer producers to temporarily suspend production.
While Luanga's Base Case2 already illustrates potential standalone economics, the ZPE-enabled Alternate Case could meaningfully enhance project optionality and resilience. With few viable PGM development projects globally, the ZPE represents a clear differentiator within the "Bravo package", positioning Luanga not only as a compelling PGM and nickel project, but also as a potential mine-to-agro solution aligned with Brazil's strategic minerals and agricultural agendas.
Advancement in Copper-Gold Potential: We continue to make progress in understanding and advancing the copper–gold potential at and around the Luanga Project, adding another track for value creation to Bravo. Both IOCG-style (Iron Oxide Copper Gold) and magmatic Ni–Cu mineralization have now been identified across several of the 17 prioritized targets.
The 2025 exploration program has confirmed extensions of copper-gold mineralization at T5 target, delivered encouraging results from initial scout drilling at T16 and T17, and expanded focus to new targets such as Babylon, which is associated with a large magnetic anomaly.
In parallel, reprocessed geophysical datasets are being used to investigate potential depth extensions of Luanga's PGM+Au+Ni mineralization, while refining drill targeting across both IOCG and magmatic Ni–Cu systems. These efforts are systematically building a robust pipeline of exploration prospects that highlight Luanga's potential well beyond the core PGM+Au+Ni deposit.
Member of the World Platinum Investment Council (WPIC): Bravo became the first pre-production PGM company to join the World Platinum Investment Council (WPIC), gaining access to valuable market intelligence and deeper engagement with both upstream and downstream participants across the global PGM value chain. This membership also provides a platform to increase awareness of the strategic significance and quality of the Luanga Project, reflecting important recognition of Bravo's growing role in the global PGM market.
Commitment to ESG: A Year of Legacy and Impact:
In terms of ESG (Environmental, Social, and Governance), 2025 was a truly remarkable year of great personal significance for me and for the entire Bravo team.
Serra Feliz Project and Partnership with the RCF Foundation: We maintained and extended our support program for children and youth in the Serra Feliz Project. We are immensely grateful to the RCF Foundation, which, part of the same group as one of our key investors, the RCF Opportunities Fund, continues to be an invaluable partner. Together, we positively impacted over 300 children, youth, and adults, promoting education, sports, dance, theater, and leisure, and contributing to improving school performance, reducing absenteeism, and boosting self-esteem and motivation. We closed the year by promoting our usual "Solidarity Christmas" for a "Christmas without Hunger" campaign, distributing basic food baskets ("Cestas Básicas") to 715 families across the communities that surround our operations.
Historic Reforestation Mark: Our reforestation program reached the impressive milestone of 44,510 trees planted. This is a significant leap from the 30,000 trees we had planted by January 2025, with over 10,000 additional ones already in our nursery and planned for the year. We prioritize planting high-value, fruit-bearing trees, such as Brazil nuts, cocoa, açaí, acerola cherry, and other native species, aiming for the rehabilitation of degraded areas within and outside the Luanga project, including in local communities and areas affected by artisanal mining. This effort demonstrates our respect for the environment, support food security for local residents and our commitment to biodiversity.
Safety and Well-being: The safety of our team is paramount. With pride, we surpassed the mark of 650,000 hours without lost-time injuries. This achievement is a testament to our safety culture, continuous training, and diligent supervision of all field activities, building upon the 522,307 hours achieved in January 2025.
Industry and Personal Recognition: For the second time (the first being in 2023), Bravo had the honor of being recognized at the 2025 Brasil Mineral Awards as Mining Company of the Year – Exploration & Prospector (small–mid companies). This distinction validates our strategy, the quality of our team, and the excellence of our work.
In addition, I had the privilege of being honored as Mineral Sector Personality of the Year ("Miner of the Year"), marking the second time I have received this award in my professional career (previously in 2018). This recognition is one I share with our entire team, as it reflects the collective dedication and effort behind Bravo's success.
Gratitude and the Vision Beyond Reflection:
The primary purpose of this letter is to express my sincere gratitude to our shareholders, directors, stakeholders, and the entire Bravo team for your continued support over the past three years. From the outset, our ambition has been clear: to build long-term value anchored by our highly valued and sought-after basket of commodities while creating a legacy of responsible and sustainable mining that benefits the communities surrounding our project and, ultimately, Brazil.
As in prior years, our progress has often been assessed through charts, trends, short-term results, and market comparisons, a constant flow of information that can sometimes reflect little more than momentary sentiment. Throughout this process, the support of our executive team, Board, and shareholders has been instrumental in maintaining focus on the underlying value of Luanga and its potential to become a benchmark asset within our industry.
There were periods when prevailing narratives questioned the future relevance of PGMs, with some characterizing them as commodities in decline and encouraging us to shift course. We listened carefully but remained committed to our long-term strategic view. That conviction has been validated: in 2025, PGMs emerged as one of the strongest-performing commodities. I thank you for the trust, patience, and confidence that allowed us to stay the course and emerge stronger.
Looking Ahead to 2026: Consolidation and Responsible Expansion:
Looking ahead, even as we potentially navigate a more favorable commodity-cycle environment, we will not compromise our principles, convictions, or discipline. We remain focused on de-risking the project with the same cash discipline that preserves our strong capital structure. Our decisions will not be driven solely by commodity prices, but by long-term value creation.
We are advancing toward the delivery of a Pre-Feasibility Study ("PFS"), continuing to optimize metallurgical processes and plant design, while maintaining ongoing dialogue with potential strategic partners capable of enhancing project value and development strategies, not only across PGMs, but also through our copper–gold opportunities. At the same time, we will continue to strengthen our ESG practices and deepen our community and institutional engagement with the government agencies overseeing our development.
With the guidance of our strong Board of Directors, further strengthened in April 2025 by the appointment of the highly regarded Margot Naudie, and with the continued support of our friend and PGM expert Stuart Comline, who remains a consultant to the Company, I am confident that we will deliver on our objectives and translate our success into value for both existing and future shareholders.
Bravo's journey is a story of vision, resilience, and, above all, collaboration. We believe in Luanga's potential to become a key supplier of essential and critical metals, contributing to a greener and technologically advanced global economy, always with the commitment to operate responsibly and generate value for all.
On behalf of the Board of Directors and management, I thank you once again for your invaluable support. Let us toast to an even more promising future.
We are Bravo!
Luis AzevedoChairman and CEOBravo Mining Corp.
About Bravo Mining Corp.
Bravo is a Canadian and Brazil-based mineral exploration and development company focused on advancing its PGM+Au+Ni Luanga Project, as well as our copper-gold exploration opportunities in the world-class Carajás Mineral Province, Para State, Brazil.
Bravo is one of the most active explorers in Carajás. The team, comprising of local and international geologists and engineers, has a proven track record of PGM, nickel, and copper discoveries in the region and elsewhere. The individuals in the team have successfully taken a past iron oxide copper gold (IOCG) greenfield project from discovery to development and production in the Carajás.
The Luanga Project is situated on mature freehold farming land and benefits from being located close to operating mines and a mining-experienced workforce, with excellent access and proximity to existing infrastructure, including road, rail, ports, and hydroelectric grid power. Bravo's current Environmental, Social and Governance activities include planting and donating more than 42,000 high-value trees in and around the project area in the past 30 months, while hiring personnel and contracting services locally.
Technical Disclosure
Technical information in this news release has been reviewed and approved by Simon Mottram, F.AusIMM (Fellow Australia Institute of Mining and Metallurgy), President of Bravo Mining Corp. who serves as the Company's "qualified person" as defined in NI 43-101. Mr. Mottram has verified the technical data and opinions contained in this news release.
Details of the MRE and PEA with cautionary language are provided in a technical report titled "NI 43-101 Preliminary Economic Assessment (PEA) Independent Technical Report for the Luanga PGM + Au + Ni Project Pará, Brazil", with an effective date of July 7, 2025, filed under the Company's SEDAR+. It can also be found in the Company's website in the link: NI 43-101 Preliminary Economic Assessment (PEA) Independent Technical Report for the Luanga PGM + Au + Ni Project, Pará, Brazil
Neither TSX Venture Exchange nor its Regulation Services Provider (as that term is defined in policies of the TSX Venture Exchange) accepts responsibility for the adequacy or accuracy of this release.
Forward Looking Statements.
This news release contains forward-looking information, words and statements which are not comprised of historical facts. Forward-looking information is characterized by words and statements such as "clearly indicating", "potential", "further growth", "materially strengthens", "meaningfully enhances", "continue to strengthen", "will deliver on our objectives", "solid", "assumed", "significant", "success", "translate", "well positioned", similar words, phrases, or statements that certain events or conditions "could", "may", "should", "will" or "would" occur. This news release contains forward-looking information pertaining to the Company's 2025 PEA; the potential for future MRE growth; whether or not current or future discoveries of copper-gold mineralization at Luanga will have sufficient economic merit to consider development; potential repeatability and improvements to the economic assumptions and/or to metallurgical recoveries used in the PEA and MRE in future studies; the potential to convert some or all of the MRE to mineral reserves through economic studies and the timing and results of any such studies; the assumption that onsite vertical integration/downstream processing will be technically and economically feasible and that an experienced/strategic partner will be identified and terms of a relationship be acceptable to Bravo; the ultimate cost of power for any future mine developed; the duration and prices in future commodity cycles; whether more value can be unlocked within the Luanga in the future; changes in the exchange rate between the US$ and Brazilian Real; the results of subsequent stages of permitting, including but not limited to the timing, granting and conditions of the Installation License (LI) and Operation License ("LO") referred to herein; the outcomes of future economic studies and the Company's plans in respect thereof. Forward-looking information involves risks, uncertainties and other factors that could cause actual events, results, and opportunities to differ materially from those expressed or implied by such forward-looking information. Factors that could cause actual results to differ materially from such forward-looking information include, but are not limited to, unexpected results from exploration programs, changes in the state of equity and debt markets, fluctuations in commodity prices, delays in obtaining required regulatory or governmental approvals, environmental risks, limitations on insurance coverage; and other risks and uncertainties involved in the mineral exploration and development industry. Forward-looking information in this news release is based on the opinions and assumptions of management considered reasonable as of the date hereof, including, but not limited to, the assumption that the assay results confirm that the interpreted mineralization contains significant values of nickel, PGMs and Au; that the mineralization remains open at depth, that PGM and/or Ni grades and mineralized thicknesses are improving at depth; that activities will not be adversely disrupted or impeded by regulatory, political, community, economic, environmental and/or healthy and safety risks; that the Luanga Project will not be materially affected by potential supply chain disruptions; and general business and economic conditions will not change in a materially adverse manner. Although the Company believes that the assumptions and factors used in preparing the forward-looking information in this news release are reasonable, undue reliance should not be placed on such information. The Company disclaims any intention or obligation to update or revise any forward-looking information, other than as required by applicable securities laws.
Luanga Project 2025 MRE
Mineral resources that are not mineral reserves do not have demonstrated economic viability. There is no certainty that all mineral resources would be converted into mineral reserves. This MRE includes Inferred Mineral Resources which have not had sufficient work to classify them as Indicated mineral resources. It is uncertain but reasonably expected that inferred mineral resources could be upgraded to indicated mineral resources with continued exploration. For further information please refer to the 2025 MRE NI 43-101 Independent Technical Report (SEDAR+) with an effective date of February 18, 2025.
Note that the assumed PEA production schedule is based on a subset of this 2025 MRE and uses a higher cut-off grade (0.87g/t PdEq for the PEA versus 0.5g/t PdEq for the MRE) to provide what Bravo deems to be an optimal return in the PEA economic model, which also excludes consideration of Oxide material at this point in time.
|
Resource Classification |
Weathering |
Average Grades and Contained Metal Estimates |
||||||||||||
|
Tonnes |
PdEq |
Pd |
Pt |
Rh |
Au |
Ni |
||||||||
|
Mt |
g/t |
Oz |
g/t |
Oz |
g/t |
Oz |
g/t |
Oz |
g/t |
Oz |
% |
Tonnes |
||
|
Measured |
Oxide |
4 |
1.51 |
197 |
0.90 |
117 |
0.88 |
115 |
0.12 |
15 |
0.05 |
7 |
— |
— |
|
High talc |
— |
— |
— |
— |
— |
— |
— |
— |
— |
— |
— |
— |
— |
|
|
Fresh Rock |
32 |
2.06 |
2,144 |
0.97 |
1,009 |
0.67 |
694 |
0.08 |
88 |
0.04 |
46 |
0.11 |
35,282 |
|
|
Total |
36 |
2.00 |
2,340 |
0.96 |
1,126 |
0.69 |
809 |
0.09 |
104 |
0.04 |
53 |
0.10 |
35,282 |
|
|
Indicated |
Oxide |
6 |
1.51 |
314 |
0.97 |
200 |
0.73 |
151 |
0.11 |
23 |
0.04 |
9 |
— |
— |
|
High talc |
2 |
1.83 |
146 |
1.12 |
89 |
0.54 |
43 |
0.08 |
6 |
0.11 |
9 |
0.13 |
3,160 |
|
|
Fresh Rock |
113 |
2.09 |
7,599 |
0.99 |
3,583 |
0.59 |
2,133 |
0.09 |
318 |
0.05 |
193 |
0.14 |
156,406 |
|
|
Total |
122 |
2.06 |
8,058 |
0.99 |
3,872 |
0.59 |
2,326 |
0.09 |
348 |
0.05 |
210 |
0.13 |
159,566 |
|
|
Measured + Indicated |
Oxide |
10 |
1.51 |
510 |
0.94 |
317 |
0.79 |
266 |
0.11 |
38 |
0.04 |
15 |
— |
— |
|
High talc |
2 |
1.83 |
146 |
1.12 |
89 |
0.54 |
43 |
0.08 |
6 |
0.11 |
9 |
0.13 |
3,160 |
|
|
Fresh Rock |
145 |
2.08 |
9,743 |
0.98 |
4,592 |
0.60 |
2,827 |
0.09 |
407 |
0.05 |
239 |
0.13 |
191,688 |
|
|
Total |
158 |
2.04 |
10,399 |
0.98 |
4,998 |
0.62 |
3,135 |
0.09 |
451 |
0.05 |
262 |
0.12 |
194,848 |
|
|
Inferred |
Oxide |
3 |
1.57 |
130 |
0.88 |
73 |
1.04 |
86 |
0.13 |
11 |
0.05 |
4 |
— |
— |
|
High talc |
0.1 |
1.76 |
5 |
1.08 |
3 |
0.53 |
2 |
0.07 |
0 |
0.10 |
0 |
0.14 |
133 |
|
|
Fresh Rock |
75 |
2.02 |
4,878 |
0.97 |
2,344 |
0.58 |
1,389 |
0.08 |
191 |
0.05 |
123 |
0.13 |
97,586 |
|
|
Total |
78 |
2.01 |
5,013 |
0.97 |
2,421 |
0.59 |
1,476 |
0.08 |
202 |
0.05 |
128 |
0.13 |
97,719 |
|
|
Table 8: MRE Declaration at a Cut-off of 0.5g/t PdEq* |
|
Table 11: Luanga Project 2025 MRE |
|
Notes to the MRE: |
|
1. |
The 2025 MRE was prepared by Bernardo Horta de Cerqueira Viana, Geologist, BSc (Geology), FAIG, CEO of GE21 Consultoria Mineral Ltda. and Porfírio Cabaleiro Rodriguez, Mining Engineer, BSc (Mine Eng), FAIG, CKO of GE21 Consultoria Mineral Ltda., both independent Qualified Person ("QP") for the purposes of National Instrument 43-101 Standards of Disclosure for Mineral Projects ("NI 43-101"). The effective date of the MRE is 18 February 2025. |
|
2. |
Mineral resources are reported using the 2014 CIM Definition Standards and were estimated in accordance with the CIM 2019 Best Practices Guidelines, as required by National Instrument 43-101 Standards of Disclosure for Mineral Projects ("NI 43-101"). |
|
3. |
The MRE Estimate is reported/confined within an economic pit shell generated by Dassault Geovia Whittle software, using the following assumptions:
|
|
4. |
The 2025 MRE supersedes and replaces the Previous Estimate (2023), which should be no longer relied upon. |
|
5. |
The QP is not aware of political, environmental, or other risks that could materially affect the potential development of the Mineral Resources other than those typical for mining projects at this stage of development, including those listed in the Technical Report dated October 22nd, 2023, and in the Company's Annual Information Form dated April 22nd, 2024. |
|
6. |
Totals may not sum due to rounding. |
Cision
View original content to download multimedia: http://www.newswire.ca/en/releases/archive/December2025/31/c0187.html
Even if it's not a huge purchase, we think it was good to see that Alexius Chan, the Non-Executive Director of Vital Metals Limited (ASX:VML) recently shelled out AU$84k to buy stock, at AU$0.10 per share. While we're hesitant to get too excited about a purchase of that size, we do note it increased their holding by a solid 32%.
The Last 12 Months Of Insider Transactions At Vital Metals
Notably, that recent purchase by Alexius Chan is the biggest insider purchase of Vital Metals shares that we've seen in the last year. Although we like to see insider buying, we note that this large purchase was at significantly below the recent price of AU$0.17. Because it occurred at a lower valuation, it doesn't tell us much about whether insiders might find today's price attractive.
In the last twelve months Vital Metals insiders were buying shares, but not selling. You can see the insider transactions (by companies and individuals) over the last year depicted in the chart below. If you want to know exactly who sold, for how much, and when, simply click on the graph below!
View our latest analysis for Vital Metals
ASX:VML Insider Trading Volume December 31st 2025
Vital Metals is not the only stock that insiders are buying. For those who like to find small cap companies at attractive valuations, this free list of growing companies with recent insider purchasing, could be just the ticket.
Insider Ownership Of Vital Metals
I like to look at how many shares insiders own in a company, to help inform my view of how aligned they are with insiders. Usually, the higher the insider ownership, the more likely it is that insiders will be incentivised to build the company for the long term. From our data, it seems that Vital Metals insiders own 8.8% of the company, worth about AU$2.2m. We do note, however, it is possible insiders have an indirect interest through a private company or other corporate structure. Whilst better than nothing, we're not overly impressed by these holdings.
So What Does This Data Suggest About Vital Metals Insiders?
The recent insider purchase is heartening. And an analysis of the transactions over the last year also gives us confidence. However, we note that the company didn't make a profit over the last twelve months, which makes us cautious. On this analysis the only slight negative we see is the fairly low (overall) insider ownership; their transactions suggest that they are quite positive on Vital Metals stock. While it's good to be aware of what's going on with the insider's ownership and transactions, we make sure to also consider what risks are facing a stock before making any investment decision. To that end, you should learn about the 5 warning signs we've spotted with Vital Metals (including 3 which shouldn't be ignored).
If you would prefer to check out another company — one with potentially superior financials — then do not miss this free list of interesting companies, that have HIGH return on equity and low debt.
For the purposes of this article, insiders are those individuals who report their transactions to the relevant regulatory body. We currently account for open market transactions and private dispositions of direct interests only, but not derivative transactions or indirect interests.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
As the Australian market approaches the end of the year, it appears to be winding down with a slight dip, likely due to profit-taking ahead of the holiday season. Despite this temporary lull, small-cap stocks continue to attract attention for their potential growth opportunities, especially in sectors like mining and technology where recent developments have shown promising signs.
Top 10 Undiscovered Gems With Strong Fundamentals In Australia
| Name | Debt To Equity | Revenue Growth | Earnings Growth | Health Rating |
|---|---|---|---|---|
| Fiducian Group | NA | 10.00% | 9.57% | ★★★★★★ |
| Joyce | NA | 9.93% | 17.54% | ★★★★★★ |
| Hearts and Minds Investments | NA | 56.27% | 59.19% | ★★★★★★ |
| Euroz Hartleys Group | NA | 1.82% | -25.32% | ★★★★★★ |
| Argosy Minerals | NA | -12.81% | -19.89% | ★★★★★★ |
| Focus Minerals | NA | 75.35% | 51.34% | ★★★★★★ |
| Djerriwarrh Investments | 2.39% | 8.18% | 7.91% | ★★★★★★ |
| Energy World | NA | -47.50% | -44.86% | ★★★★★☆ |
| Zimplats Holdings | 5.44% | -9.79% | -42.03% | ★★★★★☆ |
| Australian United Investment | 1.90% | 5.23% | 4.56% | ★★★★☆☆ |
Let’s dive into some prime choices out of from the screener.
Simply Wall St Value Rating: ★★★★★★
Overview: Cogstate Limited is a neuroscience solutions company that develops and commercializes digital brain health assessments globally, with a market capitalization of A$387.87 million.
Operations: Cogstate generates revenue primarily from its Clinical Trials segment, contributing $50.58 million, while the Healthcare segment adds $2.51 million.
Cogstate, a neuroscience tech firm focusing on digital brain health assessments, is capitalizing on strategic partnerships and AI innovation to broaden its market presence. With no debt compared to five years ago when the debt-to-equity ratio was 16.4%, Cogstate’s financial health seems robust. The company’s earnings growth of 86% over the past year surpasses the industry average of 20%. Analysts forecast an annual revenue increase of 7.6% over three years and project profit margins rising from 19.1% to 21.5%. Trading at A$1.69, with a target price of A$2.19, suggests potential upside amid competitive pressures and regulatory challenges.
ASX:CGS Debt to Equity as at Dec 2025GenusPlus Group
Simply Wall St Value Rating: ★★★★★★
Overview: GenusPlus Group Ltd specializes in the installation, construction, and maintenance of power and communication systems in Australia, with a market capitalization of A$1.14 billion.
Operations: GenusPlus Group generates revenue through three primary segments: Infrastructure (A$405.10 million), Energy & Engineering (A$224.06 million), and Services (A$122.11 million).
With a strong foothold in Australia’s renewable energy sector, GenusPlus Group is poised to benefit from the country’s grid upgrades and diverse project pipeline that reduces geographic risks. The company has strategically reduced its debt to equity ratio from 7% to 6.3% over five years, while maintaining profitability with more cash than total debt. Earnings growth of 83.6% last year outpaced the industry average by a significant margin, showcasing high-quality earnings potential. However, challenges such as integration issues from acquisitions and reliance on government infrastructure spending could impact future performance despite projected annual revenue growth of 14.2%.
ASX:GNP Debt to Equity as at Dec 2025Tasmea
Simply Wall St Value Rating: ★★★★★☆
Overview: Tasmea Limited specializes in providing shutdown, maintenance, emergency breakdown, and capital upgrade services across Australia with a market capitalization of A$1.10 billion.
Operations: Tasmea generates revenue primarily from Electrical Services (A$212.71 million), Civil Services (A$103.07 million), and Mechanical Services (A$144.87 million). Water & Fluid services contribute A$87.06 million to the total revenue.
Tasmea, a smaller player in the construction sector, showcases impressive earnings growth of 74.9% over the past year, significantly outpacing the industry average of 6.5%. Despite its high net debt to equity ratio at 59.8%, Tasmea’s interest payments are well-covered by EBIT at 10.5 times, indicating robust financial health in this regard. The company recently completed a follow-on equity offering worth A$27.5 million and announced an acquisition of WorkPac, suggesting strategic expansion plans. Trading nearly half below its estimated fair value and with forecasted earnings growth of 15.96% annually, Tasmea seems poised for further development despite its debt concerns.
- Dive into the specifics of Tasmea here with our thorough health report.
-
Evaluate Tasmea’s historical performance by accessing our past performance report.
ASX:TEA Debt to Equity as at Dec 2025Summing It All Up
- Gain an insight into the universe of 59 ASX Undiscovered Gems With Strong Fundamentals by clicking here.
- Hold shares in these firms? Setup your portfolio in Simply Wall St to seamlessly track your investments and receive personalized updates on your portfolio’s performance.
- Discover a world of investment opportunities with Simply Wall St’s free app and access unparalleled stock analysis across all markets.
Looking For Alternative Opportunities?
- Explore high-performing small cap companies that haven’t yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data
and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your
financial situation. We aim to bring you long-term focused analysis driven by fundamental data.
Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material.
Simply Wall St has no position in any stocks mentioned.
Companies discussed in this article include ASX:CGS ASX:GNP and ASX:TEA.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com
VANCOUVER, BC / ACCESS Newswire / December 31, 2025 / Apex Critical Metals Corp. (CSE:APXC)(OTCQX:APXCF)(FWB:KL9) ("Apex" or the "Company"), a Canadian mineral exploration company focused on the identification and development of critical and strategic metals, is pleased to provide a summary of all analytical results from its 2025 regional exploration drilling program and 2026 outlook at the 100%-owned Cap Critical Minerals Project ("Cap" or the "Project") in central British Columbia.
Highlights
-
Expanded mineralization from CAP25-006, which returned 124.5 m of 0.27% Nb₂O₅, encompassing the previously announced 36 m of 0.59% Nb₂O₅ that included 10 m at 1.08% Nb₂O₅.
-
The additional drill holes in 2025 were designed to test regional target areas. The niobium enriched discovery in CAP25-006 remains open in multiple directions and a priority area for follow-up drilling in 2026 (see Figure 1).
-
Multiple REE-enriched intervals were returned across the 2025 drilling, including two significant zones grading between 1.08% and 1.33% REO over 3.0 m and 3.4 m in CAP25-005 and CAP25-006, respectively, demonstrating strong rare earth potential within the carbonatite system.
-
Significant phosphate mineralization occurs in both high-grade and broad intervals, with P₂O₅ grades up to 16.2% over 3.8m (CAP25-007) and several intervals exceeding 5% P₂O₅; including 6.2% P₂O₅ over 45 m (CAP25-007) and 4.5% P₂O₅ over 97.2 m (CAP25-012)
-
The new geophysical survey results (see News Release dated November 12, 2025) show a massive buried magnetic anomaly that has yet to be tested at depth (see Figure 2). Testing this high-priority target and following up on the new near-surface niobium discovery will be the dual focus for 2026 drilling.
Sean Charland, CEO of Apex Critical Metals, stated: "The drilling highlight of the 2025 program remains the near-surface, high-grade niobium discovery, with the additional assay results showing a broader interval in CAP25-006 and further niobium, phosphate and REE mineralization in other regional target areas, which reinforces our interpretation of a large, fertile carbonatite system. We are equally excited by the intensity and scale of the untested magnetic anomaly to the southeast of our 2025 regional program, underscoring the opportunity and exploration upside at Cap."
The 2025 exploration program consisted of nine (9) helicopter-supported NQ diamond drillholes totaling 2,323 m (Table 2). The remaining results confirm widespread niobium, rare earth element and phosphate mineralization across multiple drillholes and substantially expand the mineralized interval previously reported from discovery hole CAP25-006. Collectively, the results demonstrate that Cap hosts potential for a large, fertile, multi-phase carbonatite system that remains open and underexplored.
Previously released rush assays from CAP25-006 reported 36 m averaging 0.59% Nb₂O₅, including 10 m at 1.08% Nb₂O₅, beginning at only 33.5 m downhole (see News Release dated August 27, 2025). Complete assays now show that this zone is part of a much broader mineralized interval totaling 124.5 m averaging 0.27% Nb₂O₅, confirming continuity and scale. This niobium enriched zone was not directly followed up on during the 2025 first pass regional drilling campaign and remains open both laterally (see Figure 1 below) and at depth.
Figure 1: Map showing location of 2025 drillholes over total magnetic intensity from 2025 airborne survey
The assay results also demonstrate meaningful rare earth element potential at Cap. As outlined in Table 1, multiple REE-bearing intervals were intersected across the 2025 drilling, including intervals grading between 1.08% and 1.33% REO over 3.0 m and 3.4 m in CAP25-005 and CAP25-006, respectively. Localized samples exceeding 2% REO indicate enrichment and support a broader critical-metal signature within the carbonatite system (Table 1).
Phosphate mineralization is well developed across the Project, with assay results returning both high-grade and broad continuous intervals. Results reach up to 16.2% P₂O₅, over 3.8 m with intervals including 45.0 m at 6.22% from CAP25-007 and 58.2 m at 5.63% from CAP25-012 (Table 1). The distribution of these phosphate-rich zones across multiple drillholes further supports the interpretation of a large carbonatite system.
The Company completed a geophysical survey near the end of the exploration season concurrent to its final drill holes to better detail andto further refine subsurface targeting. The survey outlined a large magnetic anomaly interpreted to represent a buried intrusive body (Figure 2). To date, this anomaly has only been tested by a single historical (2017) drill hole that did not reach the interpreted target depth. The size, strength, and limited drill testing of this feature present a compelling opportunity for follow-up, with several well-positioned drill holes planned for the 2026 exploration season.
Figure 2: Map showing 2025 drilling location and significant untested magnetic anomaly to the southeast, outlined from 2025 airborne geophysical survey
Table 1 Drillhole Assay Summary
The Company will now incorporate the full 2025 assay dataset and newly acquired airborne magnetic survey results into an updated geological model. This work will support the design of the 2026 drill program, which is expected to focus on step-out drilling around the CAP25-006 niobium discovery and initial testing of high-priority targets generated from the 2025 airborne geophysical survey. The 2025 exploration program was a success in advancing the Company's understanding of the carbonatite system at Cap and refining the focus for the year ahead.
The near-term focus remains on the Company's flagship Rift Rare Earth Project in Nebraska, USA, where significant progress is being made towards a fully funded drill program, which is expected to commence in early Q1/2026.
Table 2 Drillhole Locations and Attributes
Quality Assurance / Quality Control
All drilling was completed using a helicopter supported diamond drill rig with NQ size core and all drill core samples have been or will be shipped to Activation Laboratories Ltd. preparation facility in Kamloops, British Columbia, for standard sample preparation (code RX1) which includes drying, crush (< 7 kg) up to 80% passing 2 mm, riffle split (250 g) and pulverize (mild steel) to 95% passing 105 µm. The samples were subsequently analyzed using Code 8 by XRF Nb₂O₅, ZrO2 and Ta2O5 (0.003%), Code 8 – REE Assay (lithium metaborate/tetraborate fusion with subsequent analysis by ICP and ICP/MS). Drill core was saw-cut with half-core sent for geochemical analysis and half-core remaining in the box onsite.
A Quality Assurance/Quality Control protocol was incorporated into the program and included the insertion of certified reference material and silica blanks at a rate of approximately 5% and 5%, respectively.
Qualified Person
The technical content of this news release has been reviewed and approved by Nathan Schmidt, P. Geo., a Qualified Person under NI 43-101 on standards of disclosure for mineral projects (EGBC Licence 48336). Mr. Schmidt is a Geologist with Dahrouge Geological Consulting Ltd. (EGBC Permit to Practice 1003035), the consulting firm engaged by Apex Critical Metals Corp. to conduct and oversee all of the Company's exploration work, including the 2025 drill program.
Mr. Schmidt has verified all scientific and technical data disclosed in this news release including the sampling and QA/QC results, and certified analytical data underlying the technical information disclosed. Mr. Schmidt noted no errors or omissions during the data verification process. The Company and Mr. Schmidt do not recognize any factors of sampling or recovery that could materially affect the accuracy or reliability of the assay data disclosed in this news release.
About Apex Critical Metals Corp. (CSE:APXC)(OTCQX:APXCF)(FWB:KL9)
Apex Critical Metals Corp. is a Canadian exploration company focused on advancing rare earth element (REE) and niobium projects that support the growing demand for critical and strategic metals across the United States and Canada. The Company's flagship Rift Project, located within the highly prospective Elk Creek Carbonatite Complex in Nebraska, U.S.A., hosts extensive rare earth rights surrounding one of North America's most advanced niobium-REE deposits. Historical drilling across the complex has reported broad intervals of high-grade REE mineralization, including intercepts such as 155.5 m of 2.70% REO and 68.2 m of 3.32% REO.
In Canada, Apex continues to advance its 100%-owned Cap Project, located 85 kilometres northeast of Prince George, British Columbia. The 2025 drill program confirmed a significant niobium discovery with 0.59% Nb₂O₅ over 36 metres, including 1.08% Nb₂O₅ over 10 metres, within a 1.8-kilometre-long niobium trend. The Cap Project continues to demonstrate strong potential for niobium mineralization within a large and previously unrecognized carbonatite system.
With a growing portfolio of critical mineral projects in both Canada and the United States, Apex Critical Metals is strategically positioned to help strengthen domestic supply chains for the minerals essential to advanced technologies, clean energy, and national security. Apex is publicly listed in Canada on the Canadian Securities Exchange (CSE) under the symbol APXC and quoted on the OTCQX market in the United States under the symbol APXCF, and in Germany on the Borse Frankfurt under the symbol KL9 and/or WKN: A40CCQ. Find out more at www.apexcriticalmetals.com and to sign up for free news alerts please go to https://apexcriticalmetals.com/news/news-alerts/, or follow us on X (formerly Twitter), Facebook or LinkedIn.
On Behalf of the Board of Directors
APEX CRITICAL METALS CORP.,
Sean CharlandChief Executive OfficerTel: 604.681.1568Email: info@apexcriticalmetals.com
Neither the Canadian Securities Exchange nor its Regulation Services Provider (as that term is defined in the policies of the CSE) accepts responsibility for the adequacy or accuracy of this release.
CAUTIONARY STATEMENT REGARDING FORWARD-LOOKING INFORMATION:
This news release may contain "forward-looking statements" under applicable Canadian securities legislation. Forward-looking statements consist of statements that are not purely historical, including any statements regarding beliefs, plans, expectations or intentions regarding the future. Forward-looking statements in this news release include (without limitation) statements with respect to follow-up drilling on the Cap Project in 2026, the potential for the Cap Project to host a large, fertile multi-phase carbonatite system, statements regarding the Company's growing portfolio of critical mineral projects in Canada and the United States and the potential for exploration. Forward-looking statements are subject to various known and unknown risks and uncertainties that may cause actual results, performance or developments to differ materially from those contained in the statements. Risks that could change or prevent these events, activities or developments from coming to fruition include: the Company's properties are at an early stage of development and no current mineral resources or reserves have been identified by the Company thereof, that we may not be able to fully finance any additional exploration on the Company's properties; that even if we are able to raise capital, costs for exploration activities may increase such that we may not have sufficient funds to pay for such exploration or processing activities; the timing and content of any future work programs; geological interpretations based on drilling that may change with more detailed information; potential process methods and mineral recoveries assumptions based on limited test work and by comparison to what are considered analogous deposits that, with further test work, may not be comparable; testing of our process may not prove successful or samples derived from our properties may not yield positive results, and even if such tests are successful or initial sample results are positive, the economic and other outcomes may not be as expected; the anticipated market demand for REE and other minerals may not be as expected; the availability of labour and equipment to undertake future exploration work and testing activities; geopolitical risks which may result in market and economic instability. There can be no assurance that such statements will prove to be accurate, as actual results and future events could differ materially from those anticipated in such statements. Accordingly, readers should not place undue reliance on forward-looking statements. The forward-looking statements herein are made as of the date hereof, and the Company disclaims any intention or obligation to update or revise any forward-looking statements, whether as a result of new information, future events or otherwise, except as required by law.
SOURCE: Apex Critical Metals Corp.
View the original press release on ACCESS Newswire
As the Australian market approaches the holiday season, it is witnessing a slight downturn, with the ASX experiencing a 0.2% drop amidst profit-taking activities and early closures for Christmas. Despite this lull, small-cap stocks continue to capture interest due to their potential for growth in sectors like precious metals and defense technologies. In this context, identifying undervalued companies with strong fundamentals and innovative strategies can offer promising opportunities for investors seeking to uncover hidden gems in Australia’s vibrant market landscape.
Top 10 Undiscovered Gems With Strong Fundamentals In Australia
|
Name |
Debt To Equity |
Revenue Growth |
Earnings Growth |
Health Rating |
|---|---|---|---|---|
|
Fiducian Group |
NA |
10.00% |
9.57% |
★★★★★★ |
|
Joyce |
NA |
9.93% |
17.54% |
★★★★★★ |
|
Hearts and Minds Investments |
NA |
56.27% |
59.19% |
★★★★★★ |
|
Spheria Emerging Companies |
NA |
-1.31% |
0.28% |
★★★★★★ |
|
Euroz Hartleys Group |
NA |
1.82% |
-25.32% |
★★★★★★ |
|
Argosy Minerals |
NA |
-12.81% |
-19.89% |
★★★★★★ |
|
Focus Minerals |
NA |
75.35% |
51.34% |
★★★★★★ |
|
Energy World |
NA |
-47.50% |
-44.86% |
★★★★★☆ |
|
Zimplats Holdings |
5.44% |
-9.79% |
-42.03% |
★★★★★☆ |
|
Australian United Investment |
1.90% |
5.23% |
4.56% |
★★★★☆☆ |
Below we spotlight a couple of our favorites from our exclusive screener.
Simply Wall St Value Rating: ★★★★☆☆
Overview: Australian United Investment Company Limited is a publicly owned investment manager with a market cap of A$1.41 billion.
Operations: The company generates revenue primarily from investments, amounting to A$57 million. It has a market cap of approximately A$1.41 billion.
Australian United Investment (AUI) showcases a strong financial foundation with its net debt to equity ratio at a satisfactory 1.5%, reflecting prudent financial management. Over the past five years, AUI has reduced its debt to equity from 9.1% to 1.9%, indicating effective debt reduction strategies. The company’s high-quality earnings are complemented by robust interest coverage, with EBIT covering interest payments 22.8 times over, ensuring financial stability and resilience in challenging market conditions. Despite a modest annual earnings growth of 4.6% over the last five years, AUI remains profitable with positive free cash flow and no immediate cash runway concerns.
ASX:AUI Debt to Equity as at Dec 2025Fiducian Group
Simply Wall St Value Rating: ★★★★★★
Overview: Fiducian Group Ltd operates in Australia offering a range of financial services through its subsidiaries and has a market cap of approximately A$378.81 million.
Operations: The company’s primary revenue streams include financial planning (A$29.66 million), funds management (A$25.59 million), corporate services (A$17.67 million), and platform administration (A$16.45 million).
Fiducian Group, a nimble player in the financial landscape, stands out with its debt-free status over the past five years. This lack of debt removes any concerns about interest coverage and highlights its robust financial health. The company has demonstrated impressive earnings growth of 23.5% over the last year, significantly outpacing the broader Capital Markets industry growth of 6%. With high-quality earnings and a favorable price-to-earnings ratio of 20.4x compared to the Australian market’s 21.7x, Fiducian seems well-positioned for continued success in its sector.
-
Unlock comprehensive insights into our analysis of Fiducian Group stock in this health report.
-
Gain insights into Fiducian Group’s historical performance by reviewing our past performance report.
ASX:FID Debt to Equity as at Dec 2025Omni Bridgeway
Simply Wall St Value Rating: ★★★★★☆
Overview: Omni Bridgeway Limited operates as a global provider of dispute and litigation finance services across multiple regions including Australia, the United States, and Europe, with a market capitalization of A$432.40 million.
Operations: Omni Bridgeway generates revenue primarily from funding and providing services related to legal dispute resolution, amounting to A$87.77 million.
Omni Bridgeway, a promising player in the Australian market, recently turned profitable, making it stand out in the financial sector. The company’s price-to-earnings ratio of 1.2x positions it attractively against the broader Australian market at 21.7x. Despite a forecasted earnings decline averaging 148% annually over three years, revenue is expected to grow by nearly 24% per year. Omni Bridgeway’s debt management shines with a reduction in its debt-to-equity ratio from 18.7% to just 2.3% over five years and having more cash than total debt ensures financial stability moving forward into potential growth opportunities.
ASX:OBL Earnings and Revenue Growth as at Dec 2025Seize The Opportunity
-
Reveal the 59 hidden gems among our ASX Undiscovered Gems With Strong Fundamentals screener with a single click here.
-
Are you invested in these stocks already? Keep abreast of every twist and turn by setting up a portfolio with Simply Wall St, where we make it simple for investors like you to stay informed and proactive.
-
Take control of your financial future using Simply Wall St, offering free, in-depth knowledge of international markets to every investor.
Ready For A Different Approach?
-
Explore high-performing small cap companies that haven’t yet garnered significant analyst attention.
-
Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
-
Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Companies discussed in this article include ASX:AUI ASX:FID and ASX:OBL.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com
THIS NEWS RELEASE IS NOT FOR DISTRIBUTION TO U.S. NEWSWIRE SERVICES OR FOR DISSEMINATION IN THE UNITED STATES
VANCOUVER, BC / ACCESS Newswire / December 30, 2025 / Stillwater Critical Minerals Corp. (TSX.V:PGE)(OTCQB:PGEZF)(FSE:J0G) (the "Company", or "Stillwater") is pleased to announce the closing of its previously announced "bought deal" private placement (the "Offering") for gross proceeds of C$17,000,220, which includes the exercise in full of an over-allotment option. Pursuant to the Offering, the Company sold 36,957,000 units of the Company (each, a "Unit") at a price of C$0.46 per Unit (the "Offering Price"). Under the Offering, Red Cloud Securities Inc. acted as co-lead underwriter and sole bookrunner along with Research Capital Corporation (collectively, the "Underwriters") as co-lead underwriter.
Each Unit consists of one common share of the Company (each, a "Common Share") and one-half of one common share purchase warrant (each whole warrant, a "Warrant"). Each Warrant entitles the holder thereof to purchase one Common Share (a "Warrant Share") at a price of C$0.64 at any time on or before December 30, 2028.
The Company intends to use the net proceeds of the Offering for the exploration and advancement of the Company's flagship Stillwater West Ni-PGE-Cu-Co+Au project in the Stillwater mining district in Montana, U.S., as well as for general corporate purposes and working capital, as is more fully described in the Amended Offering Document (as defined herein).
In accordance with National Instrument 45-106 – Prospectus Exemptions ("NI 45-106"), the Units were issued to Canadian purchasers pursuant to the listed issuer financing exemption under Part 5A of NI 45-106, as amended by Coordinated Blanket Order 45-935 – Exemptions from Certain Conditions of the Listed Issuer Financing Exemption (the "Listed Issuer Financing Exemption"). The Common Shares and the Warrant Shares underlying the Units are immediately freely tradeable in accordance with applicable Canadian securities legislation if sold to purchasers resident in Canada. The Units were also sold to purchasers in offshore jurisdictions and in the United States on a private placement basis pursuant to one or more exemptions from the registration requirements of the United States Securities Act of 1933, as amended(the "U.S. Securities Act"). All securities not issued pursuant to the Listed Issuer Financing Exemption are subject to a hold period in accordance with applicable Canadian securities law, expiring four months and one day following the issue date.
"As a result of strong support demonstrated in this placement, we are ending 2025 with funds in place for a robust 2026 season" said Michael Rowley, President and CEO. "We look forward to near-term catalysts including drill results and updates on government initiatives as well as the planned update to our mineral resource estimate as we advance Stillwater West as a primary source of ten minerals designated as critical in the U.S."
As consideration for their services in the Offering, the Underwriters received aggregate cash fees of C$987,114 and 2,145,900 non-transferable common share purchase warrants (the "Broker Warrants"). Each Broker Warrant is exercisable into one Common Share at the Offering Price for a period of thirty-six (36) months from the date of issuance. The Broker Warrants are subject to a hold period in accordance with applicable Canadian securities law, expiring four months and one day following the issue date, being May 1, 2026.
There is an amended and restated offering document (the "Amended Offering Document") related to the Offering that can be accessed under the Company's profile at www.sedarplus.ca and on the Company's website at www.criticalminerals.com.
The closing of the Offering remains subject to the final approval of the TSX Venture Exchange (the "TSXV").
The securities referred to in this news release have not been, and will not be, registered under the United States Securities Act of 1933, as amended (the "U.S. Securities Act"), or any U.S. state securities laws, and may not be offered or sold in the United States or to, or for the account or benefit of, U.S. persons (as defined under the U.S. Securities Act) absent registration or any applicable exemption from the registration requirements of the U.S. Securities Act and applicable U.S. state securities laws. This news release shall not constitute an offer to sell or the solicitation of an offer to buy securities in the United States, nor shall there be any sale of these securities in any jurisdiction in which such offer, solicitation or sale would be unlawful.About Stillwater Critical Minerals Corp.
Stillwater Critical Minerals (TSX.V: PGE | OTCQB: PGEZF | FSE: J0G) is a mineral exploration and development company focused on its flagship Stillwater West Ni-PGE-Cu-Co + Au project in the iconic and famously productive Stillwater mining district in Montana, USA. With the addition of two renowned Bushveld and Platreef geologists to the team and strategic investments by Glencore plc, the Company is well positioned to advance the next phase of large-scale critical mineral supply from this world-class American district, building on past production of nickel, copper, and chromium, and the on-going production of platinum group, nickel, and other metals by neighboring Sibanye-Stillwater. An expanded NI 43-101 mineral resource estimate, released January 2023, positions Stillwater West with the largest nickel resource in an active U.S. mining district as part of a compelling suite of ten minerals now listed as critical in the USA.
Stillwater also holds a 49% interest in the high-grade Drayton-Black Lake-gold project adjacent to Nexgold
Mining's development-stage Goliath Gold Complex in northwest Ontario, currently under an earn-in agreement with Heritage Mining, and the Kluane PGE-Ni-Cu-Co critical minerals project on trend with Nickel Creek Platinum‘s Wellgreen deposit in Canada‘s Yukon Territory. The Company also holds the Duke Island Cu-Ni-PGE property in Alaska and maintains a back-in right on the high-grade past-producing Yankee-Dundee in BC, following its sale in 2013.FOR FURTHER INFORMATION, PLEASE CONTACT:
Michael Rowley, President, CEO & Director – Stillwater Critical MineralsEmail: info@criticalminerals.com Phone: (604) 357 4790Web: http://criticalminerals.com Toll Free: (888) 432 0075Forward-Looking Statements
This news release includes certain statements that may be deemed "forward-looking statements". In particular, this press release contains forward-looking information relating to, among other things, the Offering, the intended use of proceeds of the Offering and the receipt of final approval of the Offering from the TSXV. All statements in this release, other than statements of historical facts including, without limitation, statements regarding potential mineralization, historic production, estimation of mineral resources, the realization of mineral resource estimates, interpretation of prior exploration and potential exploration results, the timing and success of exploration activities generally, the timing and results of future resource estimates, permitting time lines, metal prices and currency exchange rates, availability of capital, government regulation of exploration operations, environmental risks, reclamation, title, and future plans and objectives of the company are forward-looking statements that involve various risks and uncertainties. Although Stillwater Critical Minerals believes the expectations expressed in such forward-looking statements are based on reasonable assumptions, such statements are not guarantees of future performance and actual results or developments may differ materially from those in the forward-looking statements. Forward-looking statements are based on a number of material factors and assumptions. Factors that could cause actual results to differ materially from those in forward-looking statements include failure to obtain necessary approvals, unsuccessful exploration results, changes in project parameters as plans continue to be refined, results of future resource estimates, future metal prices, availability of capital and financing on acceptable terms, general economic, market or business conditions, risks associated with regulatory changes, defects in title, availability of personnel, materials and equipment on a timely basis, accidents or equipment breakdowns, uninsured risks, delays in receiving government approvals, unanticipated environmental impacts on operations and costs to remedy same, and other exploration or other risks detailed herein and from time to time in the filings made by the companies with securities regulators. Readers are cautioned that mineral resources that are not mineral reserves do not have demonstrated economic viability. Mineral exploration and development of mines is an inherently risky business. Accordingly, the actual events may differ materially from those projected in the forward-looking statements. For more information on Stillwater Critical Minerals and the risks and challenges of their businesses, investors should review their annual filings that are available at www.sedarplus.ca.
Neither the TSXV nor its Regulation Services Provider (as that term is defined in the policies of the TSXV) accepts responsibility for the adequacy or accuracy of this release.
SOURCE: Stillwater Critical Minerals
View the original press release on ACCESS Newswire
Toronto, Ontario–(Newsfile Corp. – December 29, 2025) – Minnova Corp. (TSXV: MCI) ("Minnova" or the "Company") is pleased to announce it has directed A&B Global Mining, lead engineer on the Preliminary Economic Assessment, to evaluate and design a significant expansion of the PL Gold Mine's current 1,000 tonnes per day ("tpd") nameplate processing capacity. The current plan involves recommencing mining operations through open pit mining methods, with run-of-mine ("ROM") throughput aligned to process plant's nameplate capacity. On going work related to process plant refurbishment has recognized that the existing "front-end" crushing plant infrastructure potentially possesses capacity well in excess of 1,000 tpd.
Preliminary assessments of the primary Traylor Jaw and secondary Symons Short Head Cone crushers indicate that these robust components can support significantly higher volumes. Initial work on an expansion plan will consist of a Technical Audit & Capacity Analysis ("TACA"), including;
- Crushing Audit – verify existing crushers can sustain a crushing rate to achieve minimum 2,000 tpd.
- Motor/Drive Review – assess existing 100 HP motor on jaw crusher and 150 HP motor on the cone crusher to handle ore at increased throughput.
- Choke Point Identification – assess existing dust collection, ore chutes and transfer point capacities.
- Power Requirements – assess motor control center and transformer requirements at increased throughput rate.
Photo 1: Crushing and Screening Building and Mill Feed Infrastructure
To view an enhanced version of this graphic, please visit:https://images.newsfilecorp.com/files/3654/279121_986ddcfdd4a5583c_001full.jpg
Photo 2: Crushing and Screening Building and Mill Feed Infrastructure
To view an enhanced version of this graphic, please visit:https://images.newsfilecorp.com/files/3654/279121_986ddcfdd4a5583c_002full.jpg
Should the TACA assessment confirm the current crushing capacity exceeds 2,000 tpd, the expansion initiative will proceed to the Design & Engineering phase, with a target minimum ROM mill feed rate of 2,000 tpd. Achieving this goal will necessitate a comprehensive redesign of specific crusher plant processes, as well as the duplication of the following components: a) fine ore storage capacity, b) ore conveyor systems, and c) milling, gravity, flotation and concentrate leaching processes along with the existing Merrill-Crowe gold recovery circuit. All new equipment will be installed in parallel with the established infrastructure.
By doubling the processing plant ROM throughput capacity, Minnova aims to leverage existing infrastructure and dramatically enhance the project's economics in the current high gold price environment. This expansion initiative reflects the Company's commitment to maximizing the value of its existing infrastructure. The successful restart of the PL Gold Mine at a targeted 2,000 tpd throughput rate from open mining operations will position Minnova as a more significant gold producer, providing a robust operational foundation for the eventual transition to underground mining operations.
Option Grant
Pursuant to the Company's LTIP the Company announces that its board of directors has approved an option grant of 2,500,000 options to purchase common shares of the Company exercisable at a price of $0.20 per common share for a period of 5 years, to certain directors, officers, employees, and consultants. The common shares issuable upon exercise of the options are subject to a four month hold period from the original date of grant. These stock options vest immediately.
Qualified Person
Chris Buchanan, MSc, PGeo, is an independent consultant of the company and a qualified person under National Instrument 43-101, has reviewed and approved the scientific and technical information in this news release.
About Minnova Corp.
Minnova Corp. is a near term gold producer focused on the restart and expansion of its 100%-owned PL Gold Mine in the prolific Flin Flon Greenstone Belt of Central Manitoba. The project is situated on a past producing mine site and benefits from significant existing infrastructure, including a 1,000 tpd processing plant and valid underground mining permit (Environment Act License 1207E).
A positive 2018 Feasibility Study, based on an underground development plan and a gold price of US$1,250 per ounce, outlined a robust 5-year mine life with an annual production rate of 46,493 ounces. Considering current high gold price Minnova is revising the mine development plan to prioritize lower-cost open pit mining methods for the initial years of production before transitioning to underground methods.
A revised mine development plan that leverages the full 1,000 tpd process plant capacity and targets reduced operating costs compared to the previous underground-only model is underway and will be the subject of a Preliminary Economic Assessment and Feasibility Study to be completed in 2026. The current global gold resource remains open to expansion, as does the reserve. The Mineral Resource Estimate will be revised in 2026, using current consensus gold price assumption and will incorporate all drilling conducted after the 2018 Feasibility Study, including a 15,000-meter drill program currently in progress.
For more information please contact:
Minnova Corp.Gorden GlennPresident & Chief Executive OfficerTel: (647) 985-2785
For further information, please contact Investor Relations at info@minnovacorp.ca.
Visit our website at www.minnovacorp.ca.
Forward Looking Statements
Neither the TSX Venture Exchange nor its Regulation Services Provider (as that term is defined in the policies of the TSX Venture Exchange) accepts responsibility for the adequacy or accuracy of this release.
This news release contains certain "forward-looking information" within the meaning of applicable securities laws. Forward looking information is frequently characterized by words such as "plan", "expect", "project", "intend", "believe", "anticipate", "estimate", "may", "will", "would", "potential", "proposed" and other similar words, or statements that certain events or conditions "may" or "will" occur. These statements are only predictions. Forward-looking information is based on the opinions and estimates of management at the date the information is provided, and is subject to a variety of risks and uncertainties and other factors that could cause actual events or results to differ materially from those projected in the forward-looking information. For a description of the risks and uncertainties facing the Company and its business and affairs, readers should refer to the Company's Management's Discussion and Analysis. The Company undertakes no obligation to update forward-looking information if circumstances or management's estimates or opinions should change, unless required by law. The reader is cautioned not to place undue reliance on forward-looking information.
Not for distribution to U.S. Newswire Services or for dissemination in the United States. Any failure to comply with this restriction may constitute a violation of U.S. Securities laws.
NOT FOR DISSEMINATION INTO THE UNITED STATES
To view the source version of this press release, please visit https://www.newsfilecorp.com/release/279121
As the Australian market winds down for the holiday season with a slight dip, largely due to profit-taking and in anticipation of Wall Street’s highs, investors are turning their attention to commodities like gold and copper which have recently seen notable gains. In this environment, identifying promising small-cap stocks requires a keen eye for companies that can capitalize on these sector trends while navigating broader market sentiment.
Top 10 Undiscovered Gems With Strong Fundamentals In Australia
| Name | Debt To Equity | Revenue Growth | Earnings Growth | Health Rating |
|---|---|---|---|---|
| Fiducian Group | NA | 10.00% | 9.57% | ★★★★★★ |
| Joyce | NA | 9.93% | 17.54% | ★★★★★★ |
| Hearts and Minds Investments | NA | 56.27% | 59.19% | ★★★★★★ |
| Spheria Emerging Companies | NA | -1.31% | 0.28% | ★★★★★★ |
| Euroz Hartleys Group | NA | 1.82% | -25.32% | ★★★★★★ |
| Argosy Minerals | NA | -12.81% | -19.89% | ★★★★★★ |
| Focus Minerals | NA | 75.35% | 51.34% | ★★★★★★ |
| Energy World | NA | -47.50% | -44.86% | ★★★★★☆ |
| Zimplats Holdings | 5.44% | -9.79% | -42.03% | ★★★★★☆ |
| Australian United Investment | 1.90% | 5.23% | 4.56% | ★★★★☆☆ |
Let’s dive into some prime choices out of from the screener.
Simply Wall St Value Rating: ★★★★★☆
Overview: Carlton Investments Limited is a publicly owned asset management holding company with a market capitalization of A$911.96 million.
Operations: Carlton Investments generates revenue primarily through the acquisition and long-term holding of shares and units, amounting to A$41.60 million.
Carlton Investments, a relatively small player in the market, has shown a steady earnings growth of 8.7% annually over the past five years. Despite its modest size, it boasts high-quality earnings and maintains an impressive interest coverage ratio of 3390 times through EBIT. The company has effectively managed its debt levels, reducing the debt-to-equity ratio from 0.03% to 0.02% over five years, indicating prudent financial management. While recent earnings growth at 0.09% lagged behind industry standards of 6%, Carlton remains free cash flow positive with A$39 million recorded recently, suggesting solid operational health and potential for future stability.
- Click here to discover the nuances of Carlton Investments with our detailed analytical health report.
-
Evaluate Carlton Investments’ historical performance by accessing our past performance report.
ASX:CIN Debt to Equity as at Dec 2025Metals X
Simply Wall St Value Rating: ★★★★★★
Overview: Metals X Limited is an Australian company focused on tin production, with a market capitalization of A$975.03 million.
Operations: The primary revenue stream for Metals X Limited is its 50% stake in the Renison Tin Operation, generating A$271.38 million. The company focuses on tin production in Australia.
Metals X, a nimble player in the mining sector, boasts a remarkable earnings growth of 708% over the past year, outpacing the industry average of 10%. This performance is bolstered by its debt-free status, contrasting with a debt-to-equity ratio of 58% five years ago. With a price-to-earnings ratio at just 6.9x, it offers compelling value against the broader Australian market’s 21.7x. However, recent financials include a significant A$38M one-off gain that might skew perceptions of ongoing profitability. Despite these fluctuations and forecasts suggesting declining earnings ahead, Metals X remains financially sound with positive free cash flow and no debt concerns.
- Take a closer look at Metals X’s potential here in our health report.
-
Explore historical data to track Metals X’s performance over time in our Past section.
ASX:MLX Debt to Equity as at Dec 2025Wagners Holding
Simply Wall St Value Rating: ★★★★★☆
Overview: Wagners Holding Company Limited is involved in the production and sale of construction and related building materials across several countries, including Australia, the United States, and New Zealand, with a market capitalization of A$703.03 million.
Operations: Wagners generates revenue primarily from Construction Materials (A$257.69 million), Project Services (A$105.71 million), and Composite Fibre Technology (A$68.45 million). The company’s net profit margin reflects its financial performance, influenced by its diverse revenue streams across multiple regions.
Wagners Holding, a small Australian player in the construction sector, is making waves with its focus on sustainable materials and infrastructure. Over the past year, earnings surged by 121%, outpacing industry growth of 3%. The company has reduced its debt to equity ratio from 66% to 28% over five years, showcasing financial prudence. With a net debt to equity ratio at a satisfactory 13%, Wagners seems well-positioned for future expansion. Analysts forecast an annual revenue growth of 6% for the next three years, although capital expenditure and raw material costs could impact earnings stability. Current share price sits at A$2.57 with an anticipated target of A$2.75.
ASX:WGN Debt to Equity as at Dec 2025Make It Happen
- Reveal the 59 hidden gems among our ASX Undiscovered Gems With Strong Fundamentals screener with a single click here.
- Already own these companies? Link your portfolio to Simply Wall St and get alerts on any new warning signs to your stocks.
- Enhance your investing ability with the Simply Wall St app and enjoy free access to essential market intelligence spanning every continent.
Seeking Other Investments?
- Explore high-performing small cap companies that haven’t yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data
and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your
financial situation. We aim to bring you long-term focused analysis driven by fundamental data.
Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material.
Simply Wall St has no position in any stocks mentioned.
Companies discussed in this article include ASX:CIN ASX:MLX and ASX:WGN.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com
Zimplats Holdings' (ASX:ZIM) stock is up by a considerable 41% over the past month. However, we wonder if the company's inconsistent financials would have any adverse impact on the current share price momentum. Specifically, we decided to study Zimplats Holdings' ROE in this article.
Return on Equity or ROE is a test of how effectively a company is growing its value and managing investors’ money. In other words, it is a profitability ratio which measures the rate of return on the capital provided by the company's shareholders.
How Is ROE Calculated?
The formula for ROE is:
Return on Equity = Net Profit (from continuing operations) ÷ Shareholders' Equity
So, based on the above formula, the ROE for Zimplats Holdings is:
2.2% = US$40m ÷ US$1.8b (Based on the trailing twelve months to June 2025).
The 'return' is the income the business earned over the last year. One way to conceptualize this is that for each A$1 of shareholders' capital it has, the company made A$0.02 in profit.
View our latest analysis for Zimplats Holdings
Why Is ROE Important For Earnings Growth?
Thus far, we have learned that ROE measures how efficiently a company is generating its profits. Depending on how much of these profits the company reinvests or "retains", and how effectively it does so, we are then able to assess a company’s earnings growth potential. Generally speaking, other things being equal, firms with a high return on equity and profit retention, have a higher growth rate than firms that don’t share these attributes.
A Side By Side comparison of Zimplats Holdings' Earnings Growth And 2.2% ROE
It is quite clear that Zimplats Holdings' ROE is rather low. Even when compared to the industry average of 9.2%, the ROE figure is pretty disappointing. Given the circumstances, the significant decline in net income by 42% seen by Zimplats Holdings over the last five years is not surprising. However, there could also be other factors causing the earnings to decline. For example, the business has allocated capital poorly, or that the company has a very high payout ratio.
However, when we compared Zimplats Holdings' growth with the industry we found that while the company's earnings have been shrinking, the industry has seen an earnings growth of 12% in the same period. This is quite worrisome.
ASX:ZIM Past Earnings Growth December 27th 2025
Earnings growth is a huge factor in stock valuation. It’s important for an investor to know whether the market has priced in the company's expected earnings growth (or decline). Doing so will help them establish if the stock's future looks promising or ominous. Is Zimplats Holdings fairly valued compared to other companies? These 3 valuation measures might help you decide.
Is Zimplats Holdings Using Its Retained Earnings Effectively?
While the company did payout a portion of its dividend in the past, it currently doesn't pay a regular dividend. This implies that potentially all of its profits are being reinvested in the business.
Summary
In total, we're a bit ambivalent about Zimplats Holdings' performance. While the company does have a high rate of profit retention, its low rate of return is probably hampering its earnings growth. Up till now, we've only made a short study of the company's growth data. You can do your own research on Zimplats Holdings and see how it has performed in the past by looking at this FREE detailed graph of past earnings, revenue and cash flows.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
As the U.S. stock market continues to reach new heights, with the S&P 500 setting all-time records, investors are increasingly interested in exploring opportunities beyond large-cap stocks. Amidst this backdrop of strong market performance and economic indicators, identifying promising small-cap stocks can offer potential for growth, particularly when these companies demonstrate solid fundamentals and insider confidence through recent buying activity.
Top 10 Undervalued Small Caps With Insider Buying In The United States
| Name | PE | PS | Discount to Fair Value | Value Rating |
|---|---|---|---|---|
| Merchants Bancorp | 7.8x | 2.6x | 48.74% | ★★★★★★ |
| First United | 10.2x | 3.1x | 42.96% | ★★★★★☆ |
| Shore Bancshares | 10.6x | 2.8x | 39.92% | ★★★★☆☆ |
| Union Bankshares | 9.5x | 2.1x | 21.74% | ★★★★☆☆ |
| Angel Oak Mortgage REIT | 12.4x | 6.2x | 43.79% | ★★★★☆☆ |
| Farmland Partners | 6.4x | 7.9x | -90.27% | ★★★★☆☆ |
| Stock Yards Bancorp | 14.6x | 5.2x | 34.92% | ★★★☆☆☆ |
| MVB Financial | 10.3x | 2.0x | -10.87% | ★★★☆☆☆ |
| Omega Flex | 18.4x | 3.0x | 0.99% | ★★★☆☆☆ |
| Vestis | NA | 0.3x | -9.73% | ★★★☆☆☆ |
We’ll examine a selection from our screener results.
Simply Wall St Value Rating: ★★★★★☆
Overview: FMC is a global agricultural sciences company that provides innovative solutions for crop protection, with a market cap of $13.22 billion.
Operations: FMC’s revenue is primarily derived from its Innovative Solutions segment, which amounted to $3.61 billion. The company’s cost of goods sold (COGS) was $2.23 billion, resulting in a gross profit of $1.38 billion and a gross profit margin of 38.15%. Operating expenses include R&D costs, with recent figures showing an allocation of approximately $270.6 million towards research and development activities.
PE: -3.5x
FMC, a smaller player in the market, has seen its share price fluctuate significantly over the past three months. Despite this volatility, insider confidence is evident with recent purchases indicating potential value recognition. However, financial challenges persist as interest payments aren’t well covered by earnings and liabilities are entirely funded through external borrowing. Recent amendments to their credit agreement aim to manage leverage and dividend constraints until December 2028. With projected earnings growth of 65.93% annually, FMC’s future prospects remain intriguing despite current setbacks.
FMC Share price vs Value as at Dec 2025Granite Ridge Resources
Simply Wall St Value Rating: ★★★☆☆☆
Overview: Granite Ridge Resources is engaged in the development, exploration, and production of oil and natural gas with a market capitalization of $1.52 billion.
Operations: Granite Ridge Resources generates revenue primarily from oil and natural gas development, exploration, and production, with recent quarterly revenue reaching $427.83 million. The company’s cost of goods sold (COGS) has increased to $80.33 million in the latest quarter, impacting its gross profit margin which stands at 81.22%. Operating expenses are substantial at $230.93 million, contributing to a net income of $37.49 million for the same period.
PE: 16.3x
Granite Ridge Resources, a small-cap company in the U.S., exhibits potential for value with insider confidence shown through recent share purchases. Despite facing financial challenges like high debt and reliance on external borrowing, Granite’s earnings have improved, reporting US$14.52 million net income for Q3 2025 versus US$9.05 million a year ago. Their involvement in Conduit Power’s natural gas project highlights strategic growth opportunities in Texas’ energy sector, aiming to enhance grid reliability by 2026.
- Get an in-depth perspective on Granite Ridge Resources’ performance by reading our valuation report here.
-
Assess Granite Ridge Resources’ past performance with our detailed historical performance reports.
GRNT Share price vs Value as at Dec 2025Herbalife
Simply Wall St Value Rating: ★★★★★☆
Overview: Herbalife is a global nutrition company that develops and sells dietary supplements, personal care products, and weight management solutions, with a market capitalization of approximately $1.27 billion.
Operations: India and the United States are key markets, contributing $857.70 million and $1.01 billion respectively to revenue, while Mexico adds $534 million. The gross profit margin has shown a range from 43.92% to 53.32% over recent periods, indicating variability in cost management relative to revenue generation. Operating expenses are primarily driven by general and administrative costs, with fluctuations impacting net income margins which have varied between 1.63% and 9.28%.
PE: 4.6x
Herbalife, a player in the nutrition industry, has seen insider confidence with recent share purchases. Despite a challenging financial position where interest payments aren’t well-covered by earnings and forecasts suggest declining earnings over the next three years, the company continues to innovate. Their Liftoff energy line expansion taps into a growing US$41.4 billion energy drink market projected for 2033. Recent investments include a US$7 million Center of Excellence in California to bolster product development and quality assurance efforts.
- Delve into the full analysis valuation report here for a deeper understanding of Herbalife.
-
Gain insights into Herbalife’s past trends and performance with our Past report.
HLF Share price vs Value as at Dec 2025Make It Happen
- Get an in-depth perspective on all 80 Undervalued US Small Caps With Insider Buying by using our screener here.
- Shareholder in one or more of these companies? Ensure you’re never caught off-guard by adding your portfolio in Simply Wall St for timely alerts on significant stock developments.
- Unlock the power of informed investing with Simply Wall St, your free guide to navigating stock markets worldwide.
Want To Explore Some Alternatives?
- Explore high-performing small cap companies that haven’t yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data
and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your
financial situation. We aim to bring you long-term focused analysis driven by fundamental data.
Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material.
Simply Wall St has no position in any stocks mentioned.
Companies discussed in this article include FMC GRNT and HLF.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com
FMC Corporation's (NYSE:FMC) dividend is being reduced from last year's payment covering the same period to $0.08 on the 15th of January. Despite the cut, the dividend yield of 2.4% will still be comparable to other companies in the industry.
While the dividend yield is important for income investors, it is also important to consider any large share price moves, as this will generally outweigh any gains from distributions. FMC's stock price has reduced by 62% in the last 3 months, which is not ideal for investors and can explain a sharp increase in the dividend yield.
FMC's Future Dividend Projections Seem Positive
We like to see a healthy dividend yield, but that is only helpful to us if the payment can continue. Even though FMC is not generating a profit, it is still paying a dividend. Along with this, it is also not generating free cash flows, which raises concerns about the sustainability of the dividend.
According to analysts, EPS should be several times higher next year. Assuming the dividend continues along recent trends, we think the payout ratio will be 21%, which makes us pretty comfortable with the sustainability of the dividend.
NYSE:FMC Historic Dividend December 23rd 2025
View our latest analysis for FMC
Dividend Volatility
The company's dividend history has been marked by instability, with at least one cut in the last 10 years. Since 2015, the annual payment back then was $0.66, compared to the most recent full-year payment of $0.32. Doing the maths, this is a decline of about 7.0% per year. Declining dividends isn't generally what we look for as they can indicate that the company is running into some challenges.
Dividend Growth May Be Hard To Achieve
Given that the track record hasn't been stellar, we really want to see earnings per share growing over time. Over the past five years, it looks as though FMC's EPS has declined at around 3.0% a year. A modest decline in earnings isn't great, and it makes it quite unlikely that the dividend will grow in the future unless that trend can be reversed. However, the next year is actually looking up, with earnings set to rise. We would just wait until it becomes a pattern before getting too excited.
We're Not Big Fans Of FMC's Dividend
Overall, the dividend looks like it may have been a bit high, which explains why it has now been cut. The company seems to be stretching itself a bit to make such big payments, but it doesn't appear they can be consistent over time. The dividend doesn't inspire confidence that it will provide solid income in the future.
Market movements attest to how highly valued a consistent dividend policy is compared to one which is more unpredictable. At the same time, there are other factors our readers should be conscious of before pouring capital into a stock. For example, we've identified 3 warning signs for FMC (2 make us uncomfortable!) that you should be aware of before investing. Looking for more high-yielding dividend ideas? Try our collection of strong dividend payers.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Toronto, Ontario–(Newsfile Corp. – December 22, 2025) – Minnova Corp. (TSXV: MCI) ("Minnova" or the "Company") is pleased to announce it has engaged Amps Powerline Inc. ("AMPS"), a Manitoba based industrial power contractor specializing in the construction, maintenance, and design of high voltage industrial systems. AMPS will work closely with ABGM, lead engineer and mine development consultant overseeing planned Preliminary Economic Assessment ("PEA") and updated Feasibility Studies ("FS") in 2026 for the re-start of the Company's PL Gold Mine located in Manitoba, Canada.
This engagement marks another significant step in advancing the PL Gold Mine towards production. AMPS will provide input into:
Reconnection and energization of the PL Mine site to the MB Hydro grid utilizing the Company's existing twenty-two kilometer power line infrastructure connecting the PL Gold Mine to MB Hydro grid power.
Site power distribution and refurbishment of crushing and process plant electrical power systems.
The power line infrastructure consists of a partially refurbished twenty-two kilometer, 3-phase 25kVa power line that connects the mine sites electric distribution grid to the Manitoba Hydro electric grid at a sub-station located at Sherridon MB.
Figure 1: Photos of Existing Power Line Infrastructure
To view an enhanced version of this graphic, please visit:https://images.newsfilecorp.com/files/3654/278858_minnova.jpg
About Minnova Corp.
Minnova Corp. is a near term gold producer focused on the restart and expansion of its 100%-owned PL Gold Mine in the prolific Flin Flon Greenstone Belt of Central Manitoba. The project is situated on a past-producing mine site and benefits from significant existing infrastructure, including a 1,000 tpd processing plant and valid underground mining permit (Environment Act License 1207E).
A positive 2018 Feasibility Study, based on an underground development plan and a gold price of US$1,250 per ounce, outlined a robust 5-year mine life with an annual production rate of 46,493 ounces. Considering current high gold price Minnova is revising the mine development plan to prioritize lower-cost open pit mining methods for the initial years of production before transitioning to underground methods. The new mine plan leverages the full 1,000 tpd mill capacity and targets reduced operating costs compared to the previous underground-only model. A revised mine development plan is underway and will be the subject of a Preliminary Economic Assessment and Feasibility Study to be completed in 2026.
The current global gold resource remains open to expansion, as does the reserve. The Mineral Resource Estimate will be revised in 2026, using current consensus gold price assumption and will incorporate all drilling conducted after the 2018 Feasibility Study, including the upcoming 15,000-meter drill program scheduled for 2025 and 2026.
For more information please contact:
Minnova Corp.Gorden GlennPresident & Chief Executive OfficerTel: (647) 985-2775
For further information, please contact Investor Relations at info@minnovacorp.ca
Visit our website at www.minnovacorp.ca
Forward-Looking Statements
Neither the TSX Venture Exchange nor its Regulation Services Provider (as that term is defined in the policies of the TSX Venture Exchange) accepts responsibility for the adequacy or accuracy of this release.
This news release contains certain "forward-looking information" within the meaning of applicable securities laws. Forward looking information is frequently characterized by words such as "plan", "expect", "project", "intend", "believe", "anticipate", "estimate", "may", "will", "would", "potential", "proposed" and other similar words, or statements that certain events or conditions "may" or "will" occur. These statements are only predictions. Forward-looking information is based on the opinions and estimates of management at the date the information is provided, and is subject to a variety of risks and uncertainties and other factors that could cause actual events or results to differ materially from those projected in the forward-looking information. For a description of the risks and uncertainties facing the Company and its business and affairs, readers should refer to the Company's Management's Discussion and Analysis. The Company undertakes no obligation to update forward-looking information if circumstances or management's estimates or opinions should change, unless required by law. The reader is cautioned not to place undue reliance on forward-looking information.
Not for distribution to U.S. Newswire Services or for dissemination in the United States. Any failure to comply with this restriction may constitute a violation of U.S. Securities laws.
NOT FOR DISSEMINATION INTO THE UNITED STATES
To view the source version of this press release, please visit https://www.newsfilecorp.com/release/278858
PHILADELPHIA, Dec. 22, 2025 /PRNewswire/ — FMC Corporation (NYSE: FMC) announced today it will release its fourth quarter 2025 earnings on Wednesday, February 4, 2026, after the stock market close via PR Newswire and the company's website https://investors.fmc.com.
The company will host a webcast conference call on Thursday, February 5, 2026, at 9:00 a.m. ET that is open to the public via internet broadcast and telephone.
Conference Call Details:
Internet broadcast: https://investors.fmc.com
United States (Local): +1 646 844 6383United States (Toll-Free): +1 833 470 1428Global Dial-In Numbers: Global Dial-in NumberAccess Code: 827087
Pre-Registration Link: https://www.netroadshow.com/events/login/LE9zwo3lV0qrfzM9J1hL1dXMDtQBlK3ULBt
Webcast Details:https://events.q4inc.com/attendee/999618604
A replay of the call will be available via the internet and telephone from 11:00 a.m. ET on February 5, 2026, until February 12, 2026.
Internet replay: https://investors.fmc.comUnited States (Local): +1 929 458 6194United States (Toll-Free): +1 866 813 9403Access Code: 497154
About FMC
FMC Corporation is a global agricultural sciences company dedicated to helping growers produce food, feed, fiber and fuel for an expanding world population while adapting to a changing environment. FMC's innovative crop protection solutions – including biologicals, crop nutrition, digital and precision agriculture – enable growers and crop advisers to address their toughest challenges economically while protecting the environment. FMC is committed to discovering new herbicide, insecticide and fungicide active ingredients, product formulations and pioneering technologies that are consistently better for the planet. Visit fmc.com to learn more and follow us on LinkedIn®.
Cision
View original content to download multimedia:https://www.prnewswire.com/news-releases/fmc-corporation-announces-date-for-fourth-quarter-2025-earnings-release-and-webcast-conference-call-302648177.html
In recent market developments, the S&P 500 and Dow Jones Industrial Average have experienced declines following a surprising rise in unemployment, while the Nasdaq managed to tick higher, breaking its losing streak. Amid these mixed signals from major indices and economic indicators, investors may find opportunities in stocks that are perceived to be undervalued relative to their intrinsic value. Identifying such stocks requires careful analysis of financial health and growth potential within the context of current market conditions.
Top 10 Undervalued Stocks Based On Cash Flows In The United States
|
Name |
Current Price |
Fair Value (Est) |
Discount (Est) |
|
UMB Financial (UMBF) |
$118.98 |
$233.99 |
49.2% |
|
Perfect (PERF) |
$1.72 |
$3.43 |
49.9% |
|
Krystal Biotech (KRYS) |
$235.80 |
$469.93 |
49.8% |
|
Freshworks (FRSH) |
$12.39 |
$23.62 |
47.6% |
|
FirstSun Capital Bancorp (FSUN) |
$38.82 |
$73.56 |
47.2% |
|
First Solar (FSLR) |
$254.03 |
$482.71 |
47.4% |
|
Dingdong (Cayman) (DDL) |
$2.82 |
$5.45 |
48.3% |
|
DexCom (DXCM) |
$65.75 |
$127.60 |
48.5% |
|
Columbia Banking System (COLB) |
$28.95 |
$57.33 |
49.5% |
|
Bloom Energy (BE) |
$76.97 |
$148.02 |
48% |
We’re going to check out a few of the best picks from our screener tool.
Overview: Ligand Pharmaceuticals Incorporated is a biopharmaceutical company that develops and licenses biopharmaceutical assets globally, with a market cap of approximately $3.83 billion.
Operations: The company’s revenue primarily comes from the development and licensing of biopharmaceutical assets, totaling $251.23 million.
Estimated Discount To Fair Value: 15.1%
Ligand Pharmaceuticals appears undervalued based on discounted cash flow analysis, trading at US$194.59 against an estimated fair value of US$229.31. Recent earnings showed a substantial improvement, with third-quarter revenue rising to US$115.46 million and net income reaching US$117.27 million from a loss previously. The company forecasts 2026 revenue between $245 million and $285 million, driven by royalty and Captisol sales, supporting its growth trajectory above the market average.
LGND Discounted Cash Flow as at Dec 2025Kroger
Overview: The Kroger Co. operates as a food and drug retailer in the United States with a market cap of approximately $40.38 billion.
Operations: The company’s revenue is primarily derived from its retail operations, which generate $147.23 billion.
Estimated Discount To Fair Value: 15.1%
Kroger, trading at US$63.81, is undervalued based on discounted cash flow analysis with a fair value estimate of US$75.14. Despite a forecasted significant earnings growth rate of 30.4% annually over the next three years, recent financials reveal challenges including a net loss of US$1.32 billion in Q3 2025 and declining profit margins from last year. Additionally, Kroger faces regulatory scrutiny due to infant formula recalls impacting store operations and legal issues related to patent infringement claims.
-
Insights from our recent growth report point to a promising forecast for Kroger’s business outlook.
-
Take a closer look at Kroger’s balance sheet health here in our report.
KR Discounted Cash Flow as at Dec 2025Sociedad Química y Minera de Chile
Overview: Sociedad Química y Minera de Chile S.A. is a global producer and seller of specialty plant nutrients and iodine derivatives, with a market cap of approximately $18.83 billion.
Operations: The company’s revenue segments include Lithium and Derivatives ($2.08 billion), Iodine and Derivatives ($996.40 million), Specialty Plant Nutrition ($957.03 million), Potassium ($182.60 million), and Industrial Chemicals ($74.26 million).
Estimated Discount To Fair Value: 36.7%
Sociedad Química y Minera de Chile, trading at US$65.92, is undervalued with a fair value estimate of US$104.17 based on discounted cash flow analysis. Recent earnings show strong performance with Q3 sales of US$1.17 billion and net income rising to US$178.42 million from last year’s figures. Despite high debt levels, the company benefits from robust growth forecasts in revenue and profit, supported by strategic partnerships like the one approved with Codelco in China’s lithium market.
SQM Discounted Cash Flow as at Dec 2025Summing It All Up
-
Get an in-depth perspective on all 206 Undervalued US Stocks Based On Cash Flows by using our screener here.
-
Invested in any of these stocks? Simplify your portfolio management with Simply Wall St and stay ahead with our alerts for any critical updates on your stocks.
-
Streamline your investment strategy with Simply Wall St’s app for free and benefit from extensive research on stocks across all corners of the world.
Contemplating Other Strategies?
-
Explore high-performing small cap companies that haven’t yet garnered significant analyst attention.
-
Diversify your portfolio with solid dividend payers offering reliable income streams to weather potential market turbulence.
-
Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Companies discussed in this article include LGND KR and SQM.
This article was originally published by Simply Wall St.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com
Passive investing in index funds can generate returns that roughly match the overall market. But you can significantly boost your returns by picking above-average stocks. To wit, the Sociedad Química y Minera de Chile S.A. (NYSE:SQM) share price is 75% higher than it was a year ago, much better than the market return of around 14% (not including dividends) in the same period. So that should have shareholders smiling. On the other hand, longer term shareholders have had a tougher run, with the stock falling 20% in three years.
So let's investigate and see if the longer term performance of the company has been in line with the underlying business' progress.
While markets are a powerful pricing mechanism, share prices reflect investor sentiment, not just underlying business performance. One way to examine how market sentiment has changed over time is to look at the interaction between a company's share price and its earnings per share (EPS).
Sociedad Química y Minera de Chile went from making a loss to reporting a profit, in the last year.
When a company has just transitioned to profitability, earnings per share growth is not always the best way to look at the share price action.
Unfortunately Sociedad Química y Minera de Chile's fell 9.2% over twelve months. So using a snapshot of key business metrics doesn't give us a good picture of why the market is bidding up the stock.
You can see how earnings and revenue have changed over time in the image below (click on the chart to see the exact values).
NYSE:SQM Earnings and Revenue Growth December 18th 2025
Sociedad Química y Minera de Chile is a well known stock, with plenty of analyst coverage, suggesting some visibility into future growth. If you are thinking of buying or selling Sociedad Química y Minera de Chile stock, you should check out this free report showing analyst consensus estimates for future profits.
A Different Perspective
We're pleased to report that Sociedad Química y Minera de Chile shareholders have received a total shareholder return of 75% over one year. That's including the dividend. That's better than the annualised return of 10% over half a decade, implying that the company is doing better recently. Given the share price momentum remains strong, it might be worth taking a closer look at the stock, lest you miss an opportunity. It's always interesting to track share price performance over the longer term. But to understand Sociedad Química y Minera de Chile better, we need to consider many other factors. For instance, we've identified 2 warning signs for Sociedad Química y Minera de Chile (1 is a bit concerning) that you should be aware of.
But note: Sociedad Química y Minera de Chile may not be the best stock to buy. So take a peek at this free list of interesting companies with past earnings growth (and further growth forecast).
Please note, the market returns quoted in this article reflect the market weighted average returns of stocks that currently trade on American exchanges.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
THIS NEWS RELEASE IS NOT FOR DISTRIBUTION TO U.S. NEWSWIRE SERVICES OR FOR DISSEMINATION IN THE UNITED STATES
VANCOUVER, BC / ACCESS Newswire / December 15, 2025 / Stillwater Critical Minerals Corp. (TSX.V:PGE)(OTCQB:PGEZF)(FSE:J0G) (the "Company", or "Stillwater") is pleased to announce that as a result of strong investor demand, the Company has increased the size of its previously announced "bought deal" private placement (the "Underwritten Offering") from gross proceeds of C$10,000,400 to gross proceeds of C$15,000,140. Pursuant to the upsized Underwritten Offering, Red Cloud Securities Inc. ("Red Cloud"), as co-lead underwriter and sole bookrunner, and Research Capital Corporation (collectively with Red Cloud, the "Underwriters"), as co-lead underwriter, will purchase for resale 32,609,000 units of the Company (each, a "Unit") at a price of C$0.46 per Unit (the "Offering Price").
Each Unit will consist of one common share of the Company (each, a "Common Share") and one-half of one common share purchase warrant (each whole warrant, a "Warrant"). Each Warrant will entitle the holder thereof to purchase one Common Share (a "Warrant Share") at a price of C$0.64 at any time on or before that date which is 36 months following the Closing Date (as herein defined).
The Company will grant to the Underwriters an option, exercisable in full or in part up to 48 hours prior to the Closing Date, to purchase for resale up to an additional 4,348,000 Units at the Offering Price for additional gross proceeds of up to C$2,000,080 (the "Over-Allotment Option"). The Underwritten Offering and the securities issuable upon exercise of the Over-Allotment Option shall be collectively referred to as the "Offering".
The Company intends to use the net proceeds of the Offering for the exploration and advancement of the Company's flagship Stillwater West Ni-PGE-Cu-Co+Au project in the Stillwater mining district in Montana, U.S., as well as for general corporate purposes and working capital, as is more fully described in the Amended Offering Document (as defined herein).
Subject to compliance with applicable regulatory requirements and in accordance with National Instrument 45-106 – Prospectus Exemptions ("NI 45-106"), the Units will be offered for sale to purchasers in certain of the provinces of Canada pursuant to the listed issuer financing exemption under Part 5A of NI 45-106, as amended by Coordinated Blanket Order 45-935 – Exemptions from Certain Conditions of the Listed Issuer Financing Exemption (the "Listed Issuer Financing Exemption"). The Common Shares and the Warrant Shares underlying the Units are expected to be immediately freely tradeable in accordance with applicable Canadian securities legislation if sold to purchasers resident in Canada. The Units may also be sold in offshore jurisdictions and in the United States on a private placement basis pursuant to one or more exemptions from the registration requirements of the United States Securities Act of 1933, as amended(the "U.S. Securities Act"). All securities not issued pursuant to the Listed Issuer Financing Exemption will be subject to a hold period in accordance with applicable Canadian securities law, expiring four months and one day following the Closing Date.
There is an amended and restated offering document (the "Amended Offering Document") related to the Offering that can be accessed under the Company's profile at www.sedarplus.ca and on the Company's website at: www.criticalminerals.com. Prospective investors should read this Amended Offering Document before making an investment decision.
The Offering is scheduled to close on or about December 30, 2025 or such other date as the Company and Red Cloud may agree (the "Closing Date"). Completion of the Offering is subject to certain conditions including, but not limited to, the receipt of all necessary regulatory approvals, including the approval of the TSX Venture Exchange (the "TSXV").
This news release does not constitute an offer to sell or a solicitation of an offer to buy nor shall there be any sale of any of the securities in any jurisdiction in which such offer, solicitation or sale would be unlawful, including any of the securities in the United States of America. The Securities to be issued pursuant to the Offering have not been, and will not be, registered under the U.S. Securities Act or any U.S. state securities laws, and may not be offered or sold in the United States or to, or for the account or benefit of, U.S. persons, absent registration or any applicable exemption from the registration requirements of the U.S. Securities Act and applicable U.S. state securities laws.
About Stillwater Critical Minerals Corp.
Stillwater Critical Minerals (TSX.V: PGE | OTCQB: PGEZF | FSE: J0G) is a mineral exploration and development company focused on its flagship Stillwater West Ni-PGE-Cu-Co + Au project in the iconic and famously productive Stillwater mining district in Montana, USA. With the addition of two renowned Bushveld and Platreef geologists to the team and strategic investments by Glencore plc, the Company is well positioned to advance the next phase of large-scale critical mineral supply from this world-class American district, building on past production of nickel, copper, and chromium, and the on-going production of platinum group, nickel, and other metals by neighboring Sibanye-Stillwater. An expanded NI 43-101 mineral resource estimate, released January 2023, positions Stillwater West with the largest nickel resource in an active U.S. mining district as part of a compelling suite of ten minerals now listed as critical in the USA.
Stillwater also holds a 49% interest in the high-grade Drayton-Black Lake-gold project adjacent to Nexgold
Mining's development-stage Goliath Gold Complex in northwest Ontario, currently under an earn-in agreement with Heritage Mining, and the Kluane PGE-Ni-Cu-Co critical minerals project on trend with Nickel Creek Platinum‘s Wellgreen deposit in Canada‘s Yukon Territory. The Company also holds the Duke Island Cu-Ni-PGE property in Alaska and maintains a back-in right on the high-grade past-producing Yankee-Dundee in BC, following its sale in 2013.
FOR FURTHER INFORMATION, PLEASE CONTACT:
Michael Rowley, President, CEO & Director – Stillwater Critical MineralsEmail: info@criticalminerals.com Phone: (604) 357 4790Web: http://criticalminerals.com Toll Free: (888) 432 0075
Forward-Looking Statements
This news release includes certain statements that may be deemed "forward-looking statements". In particular, this press release contains forward-looking information relating to, among other things, the Offering, the anticipated closing date of the Offering, the intended use of proceeds of the Offering, approval of the TSXV and the filing of the Amended Offering Document. All statements in this release, other than statements of historical facts including, without limitation, statements regarding potential mineralization, historic production, estimation of mineral resources, the realization of mineral resource estimates, interpretation of prior exploration and potential exploration results, the timing and success of exploration activities generally, the timing and results of future resource estimates, permitting time lines, metal prices and currency exchange rates, availability of capital, government regulation of exploration operations, environmental risks, reclamation, title, and future plans and objectives of the company are forward-looking statements that involve various risks and uncertainties. Although Stillwater Critical Minerals believes the expectations expressed in such forward-looking statements are based on reasonable assumptions, such statements are not guarantees of future performance and actual results or developments may differ materially from those in the forward-looking statements. Forward-looking statements are based on a number of material factors and assumptions. Factors that could cause actual results to differ materially from those in forward-looking statements include failure to obtain necessary approvals, unsuccessful exploration results, changes in project parameters as plans continue to be refined, results of future resource estimates, future metal prices, availability of capital and financing on acceptable terms, general economic, market or business conditions, risks associated with regulatory changes, defects in title, availability of personnel, materials and equipment on a timely basis, accidents or equipment breakdowns, uninsured risks, delays in receiving government approvals, unanticipated environmental impacts on operations and costs to remedy same, and other exploration or other risks detailed herein and from time to time in the filings made by the companies with securities regulators. Readers are cautioned that mineral resources that are not mineral reserves do not have demonstrated economic viability. Mineral exploration and development of mines is an inherently risky business. Accordingly, the actual events may differ materially from those projected in the forward-looking statements. For more information on Stillwater Critical Minerals and the risks and challenges of their businesses, investors should review their annual filings that are available at www.sedarplus.ca.
Neither the TSX Venture Exchange nor its Regulation Services Provider (as that term is defined in the policies of the TSX Venture Exchange) accepts responsibility for the adequacy or accuracy of this release.
SOURCE: Stillwater Critical Minerals Corp.
View the original press release on ACCESS Newswire
If you would like to receive our free newsletter via email, simply enter your email address below & click subscribe.
 Follow us on Twitter
 Become our facebook fan
CONNECT WITH US
Tweets
Tweet with hash tag #miningfeeds or @miningfeeds and your tweets will be displayed across this site.
MOST ACTIVE MINING STOCKS
Daily Gainers
 Wallbridge Mining Co. Ltd. |
WM.TO | +1,900.00% |
| Galore Resources Inc. |
GRI.V | +100.00% |
| Midlands Minerals Corp. |
MEX.V | +66.88% |
 Redstone Resources Ltd |
RDS.AX | +50.00% |
| GoviEx Uranium Inc. |
GXU.V | +42.86% |
| Mount Burgess Mining NL |
MTB.AX | +33.33% |
| Casa Minerals Inc. |
CASA.V | +30.00% |
| Poseidon Nickel Limited |
POS.AX | +25.00% |
| Azincourt Energy Corp. |
AAZ.V | +20.00% |
| ALX Uranium Corp. |
AL.V | +16.67% |